Consumer demand overall looks steady even as sentiment has plunged....

Bob Elliott@BobEUnlimited
22 views
Apr 30, 2025
~3 min read
Advertisement
1
Consumer demand overall looks steady even as sentiment has plunged.
Every timely read of spending data indicates no downshift in total household consumption in Apr, suggesting that the March numbers we see today for PCE are a decent proxy for the read on spot demand.
Thread.
Every timely read of spending data indicates no downshift in total household consumption in Apr, suggesting that the March numbers we see today for PCE are a decent proxy for the read on spot demand.
Thread.
2
Today's GDP report is going to be a mess as a surge in imports will likely create distortions in the top read.
As a result its much better to focus on the end demand numbers particularly from households. And further focus on the more timely personal income and spending report.
As a result its much better to focus on the end demand numbers particularly from households. And further focus on the more timely personal income and spending report.
3
Remember the GDP report data is very lagged, with the midpoint effectively just a few weeks after the admin took office. A lifetime ago.
The personal spending numbers (weird release timing at 10am) will give a more timely read of demand in March.
The personal spending numbers (weird release timing at 10am) will give a more timely read of demand in March.
4
The personal consumption numbers had been pretty soft thru the first couple months of the year - with a very weak Jan (in part due to fires & weather) which was only modestly reversed in Feb.
The March numbers are best thought of as the baseline pre-Liberation Day.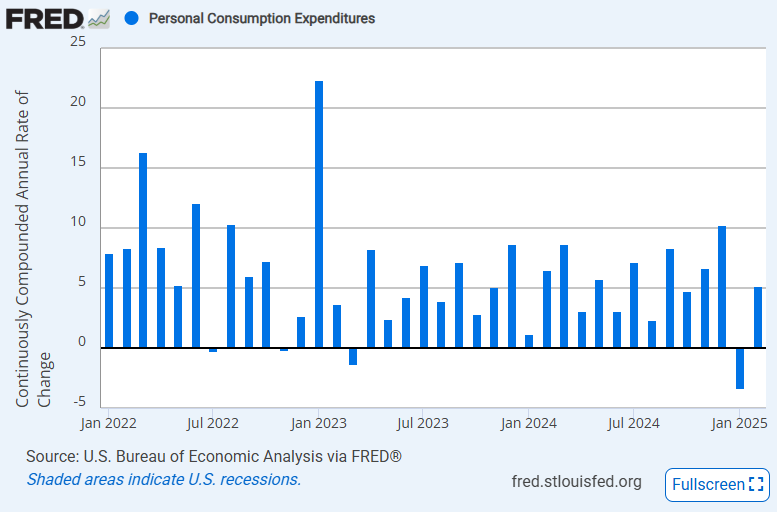
The March numbers are best thought of as the baseline pre-Liberation Day.
5
The retail sales control group read we got earlier in the month did indicate some signs of weakening demand that will likely flow through to the PCE numbers released today. But this only represents a portion of overall consumption.

6
More timely reads suggest that there hasn't been much downshift in spending even post-Liberation Day. Visa's earnings release suggests stable payments Mar->Apr. As an aside, notable that the Jan/Feb path is inverse from above. h/t @JackFarley96 and @eugeneng

7
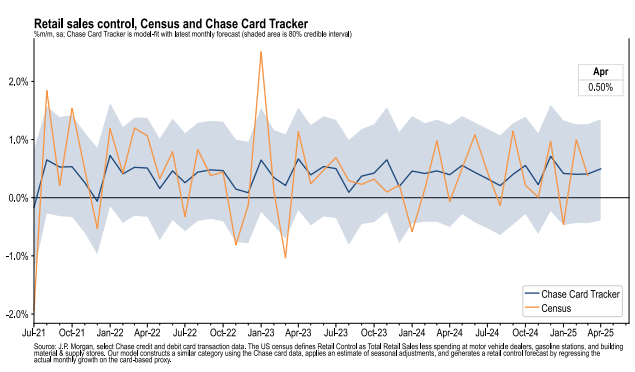
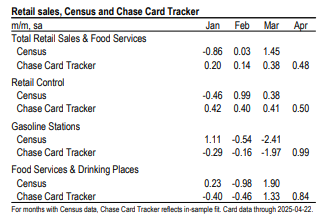
Similarly the Chase card tracker doesn't show much change in the headline numbers.
8
Maybe a little pickup in the control group, but you can see even from a few months read, its not great at tracking the reported data.
9
Those reads are in line with basically all the qualitative comments seen from bank CEOs in earnings reports in recent weeks.
thefinancialbrand.com/news/banking-t…
thefinancialbrand.com/news/banking-t…
10
And what we are seeing in the timely Redbook data which has remained stable as well - maybe a little uptick for a few weeks and a little downtick in the last week, but that's really squinting for signal.

11
These timely reads are best at giving an indication of the *trend* not the actual level of spending since they sample different populations & categories.
And from a trend dimension it looks pretty clear that demand has remained pretty steady pre and post Liberation Day.
And from a trend dimension it looks pretty clear that demand has remained pretty steady pre and post Liberation Day.
12
What is tough to fully disentangle is how much of this stability is a function of a pull forward of goods demand ahead of tariff hikes, and how much is just reflecting a disconnect between sentiment and actual underlying activity.
Weak services demand may give an indication:
Weak services demand may give an indication:
13
The March read on the composition of demand will be particularly important in thinking through the magnitude of the front-running impacts.
Because eventually that pull forward of demand will fade, and with it what looks like an illusion of spending stability in recent months.
Because eventually that pull forward of demand will fade, and with it what looks like an illusion of spending stability in recent months.
14
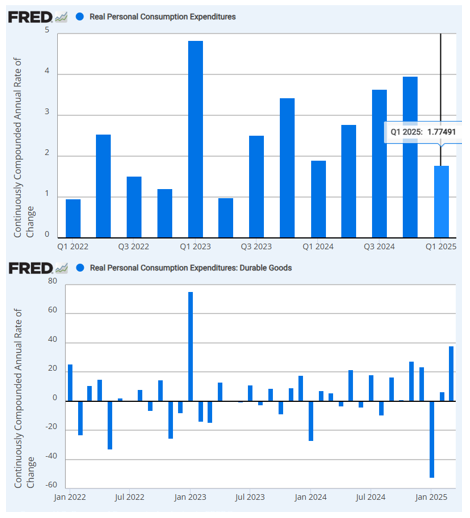
1Q real PCE at 1.8%, significant weakening from the ramp up to strong growth rates we had been seeing at the end of last year. And that's even with a surge in durable demand in March from front-running that we had been hearing anecdotally. A weak baseline for what's ahead.