While the admin & the Fed have a lot of power to create a bond put...

Bob Elliott@BobEUnlimited
27 views
Apr 11, 2025
~2 min read
Advertisement
1
While the admin & the Fed have a lot of power to create a bond put struck not too far from here, they have almost no ability to control dollar depreciation.
With 15 years of US exceptionalism bets built up, the unwind we've seen in recent days is just getting started.
Thread.
With 15 years of US exceptionalism bets built up, the unwind we've seen in recent days is just getting started.
Thread.
2
This week the admin (kinda) blinked on tariff policy in part b/c the long end of the bond curve started to rise pretty rapidly.
The result is that many folks now are holding that there is a "Trump put" on the US bond market which will put a lid on rises much higher than 5%.
The result is that many folks now are holding that there is a "Trump put" on the US bond market which will put a lid on rises much higher than 5%.
3
While the admin doesn't have direct tools to control the bond market, they do have the ability to shift policy in a way that can be supportive (cut spending, shift duration issuance, etc). Further the Fed always has rates and money printing at its disposal. The put is credible.
4
But neither the Fed or the admin can do much with the dollar. International capital flows far outpace any foreign reserves the US has on hand. And admin policies can influence sentiment by foreign investors to some extent, but likely do little to shift flows.
5
If anything the focus on the bond put further exacerbates the USD problem. Increased foreign views of riskiness in the US has to either be resolved with higher expected returns on assets (higher yields) or lower currency. Capping the bond yields, almost require a lower USD.
6
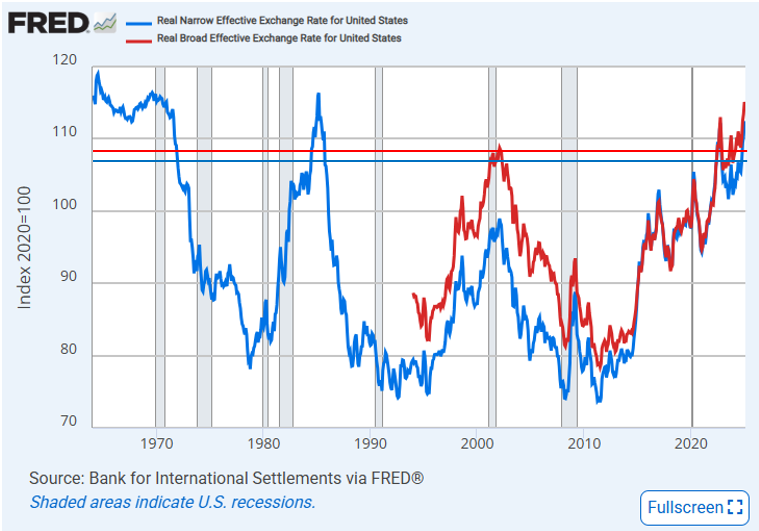
This comes at a time when there has been nearly 15 years of trades built up long US financial assets relative to the rest of the world. While the moves appear big up close, in any secular context the dollar remains very elevated. It'd take much larger moves to unwind all-in USA.
7
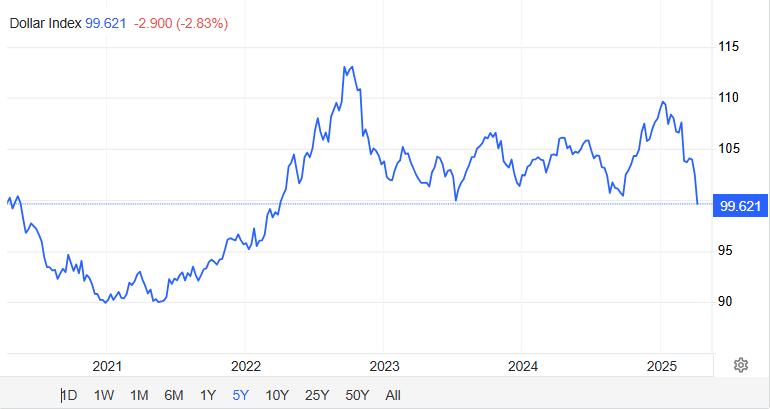
And in any short-term context the moves are pretty modest as well, moving from the high end of the range of the last few years to the low end of the range. It feels big in a drawdown context, but the current levels are far from reflecting the repricing of US exceptionalism.
8
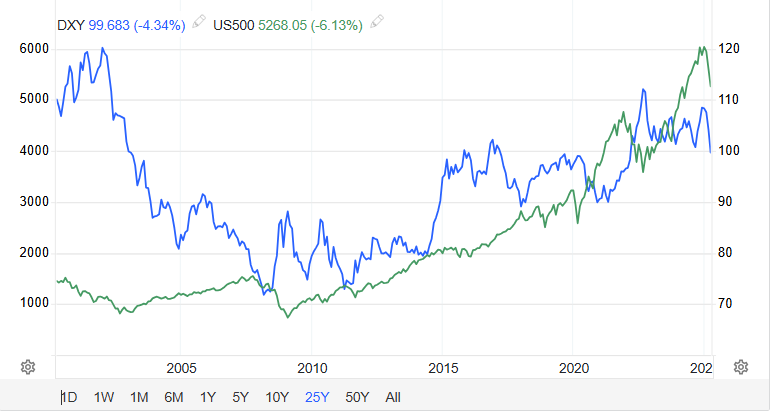
For the first time in decades the dollar / equity correlation flipped acutely positive in recent weeks, marking the first time in decades where the US was no longer the safe haven assets of the world. Liquidity is being pulled from the US, rather than the US pulling liquidity.
9
With decades of build up capital positions in US assets, foreign investors have likely only just started their unwind of US asset exposures. With the US running such a large structural capital need, simply a slowing of large inflows of capital into the US can drive a weaker USD.
10
This downcycle is transitioning from one where growth pricing is too optimistic to where overvalued US assets increasingly lose their bid from abroad, favoring short USD and long gold views.
And the most challenging thing is US policymakers can do little to stop it.
And the most challenging thing is US policymakers can do little to stop it.