$FTNT is down 26% after its Q2 earnings release in Aug. But its...

Kintsugi Investing@kintsugiinvest
72 views
Sep 29, 2025
~2 min read
Advertisement
1
$FTNT is down 26% after its Q2 earnings release in Aug.
But its revenue and profits continue to climb.
Is this an opportunity?
Or is the stock an avoid?
We took a deeper look into its story.
Here’s a 5min summary:🧵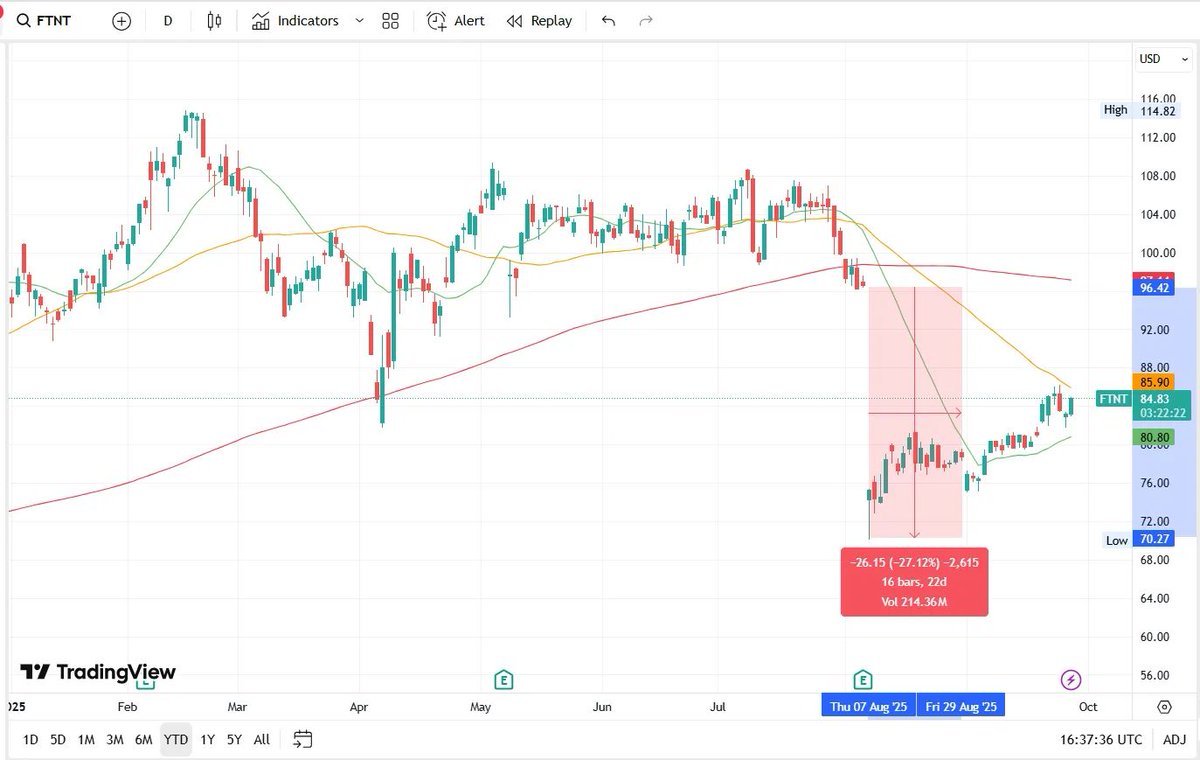
But its revenue and profits continue to climb.
Is this an opportunity?
Or is the stock an avoid?
We took a deeper look into its story.
Here’s a 5min summary:🧵
2
On August 7th, Fortinet stock dropped 26% in a single day.
Not because it missed earnings.
It beat them.
But investors were spooked by one line in the report.
Could this be a long-term opportunity?
Not because it missed earnings.
It beat them.
But investors were spooked by one line in the report.
Could this be a long-term opportunity?
3
Fortinet’s CEO revealed that the hardware refresh cycle—a key growth driver—was already 40–50% complete.
That admission crushed expectations of continued momentum.
Wall Street wanted more.
But here’s what they missed…
That admission crushed expectations of continued momentum.
Wall Street wanted more.
But here’s what they missed…
4
Fortinet is not just a hardware company.
It’s quietly transforming into a cybersecurity platform play:
• 35%+ operating margins
• High-growth recurring revenue streams
• Cloud-native SASE infrastructure
• Embedded AI threat detection
This is evolution, not decline.
It’s quietly transforming into a cybersecurity platform play:
• 35%+ operating margins
• High-growth recurring revenue streams
• Cloud-native SASE infrastructure
• Embedded AI threat detection
This is evolution, not decline.
5
Imagine Fortinet as the full security system for your digital operations.
It sells the firewalls (hardware), but also the:
• Surveillance
• Alarm systems
• Guard dogs (AI)
• Ongoing monitoring
All bundled into one scalable fabric.
It sells the firewalls (hardware), but also the:
• Surveillance
• Alarm systems
• Guard dogs (AI)
• Ongoing monitoring
All bundled into one scalable fabric.
6
Despite the drop, Fortinet’s Q2 2025 showed strength:
• Revenue beat
• Net income up
• Software & services growing
• SASE ARR +28% YoY
• Operating efficiency improving
Not signs of a broken business.
• Revenue beat
• Net income up
• Software & services growing
• SASE ARR +28% YoY
• Operating efficiency improving
Not signs of a broken business.
7
So what caused the panic?
A shift in narrative.
The market thought Fortinet had more room in the upgrade cycle.
When management said otherwise, it felt like the growth story ended.
But in truth, it’s just entering a new chapter.
A shift in narrative.
The market thought Fortinet had more room in the upgrade cycle.
When management said otherwise, it felt like the growth story ended.
But in truth, it’s just entering a new chapter.
8
Behind the scenes, Fortinet is leaning into:
•Subscription services
• Cloud-first SASE adoption
• FortiAI (automated threat defense)
• Software revenue with high margins
And they’re already trusted by governments, enterprises, and SMBs.
•Subscription services
• Cloud-first SASE adoption
• FortiAI (automated threat defense)
• Software revenue with high margins
And they’re already trusted by governments, enterprises, and SMBs.
9
One stat that stands out:
Fortinet was ranked #7 on Forbes’ Most Trusted Companies in America (2025).
The most trusted U.S. cybersecurity firm.
In a world where trust is everything in cyber.
That moat is hard to replicate.
Fortinet was ranked #7 on Forbes’ Most Trusted Companies in America (2025).
The most trusted U.S. cybersecurity firm.
In a world where trust is everything in cyber.
That moat is hard to replicate.
10
Now the risks:
• Ongoing class action lawsuit over forward guidance
• Volatility from narrative reset
• Execution risk in pivoting from hardware to high-growth software
These don’t change the fundamentals—but they may shape near-term sentiment.
• Ongoing class action lawsuit over forward guidance
• Volatility from narrative reset
• Execution risk in pivoting from hardware to high-growth software
These don’t change the fundamentals—but they may shape near-term sentiment.
11
The Kintsugi Take:
Moderate-risk, moderate-reward.
The company is shifting gears—and the market doesn’t like uncertainty.
But transitions often create mispricing.
And mispricing = opportunity if the core thesis holds.
Moderate-risk, moderate-reward.
The company is shifting gears—and the market doesn’t like uncertainty.
But transitions often create mispricing.
And mispricing = opportunity if the core thesis holds.
12
What to watch going forward:
• SASE + subscription revenue momentum
• Enterprise IT budgets in a slower macro
• New product rollouts in AI, Zero Trust
• Clarity around legal overhang
• Forward guidance & billings trends
These will define the next 12–24 months.
• SASE + subscription revenue momentum
• Enterprise IT budgets in a slower macro
• New product rollouts in AI, Zero Trust
• Clarity around legal overhang
• Forward guidance & billings trends
These will define the next 12–24 months.
13
If Fortinet can execute, this dip could age like Adobe in 2013 or Microsoft in 2014.
Profitable, high-moat, misunderstood transitions don’t stay cheap forever.
We’re watching closely.
Profitable, high-moat, misunderstood transitions don’t stay cheap forever.
We’re watching closely.
14
We cover $FTNT more in depth in our newsletter.
Read the full analysis (including fundamentals and valuation) here:
newsletter.kintsugiinvesting.com/subscribe
Read the full analysis (including fundamentals and valuation) here:
newsletter.kintsugiinvesting.com/subscribe