$LMND ran 30% yesterday post earnings. But I think they're just...

Oliver | MMMT Wealth (CPA)@MMMTwealth
10 views
Aug 06, 2025
~2 min read
Advertisement
1
$LMND ran 30% yesterday post earnings.
But I think they're just getting started.
$LMND is also my highest conviction stock and biggest position in my portfolio.
Here's why 👇 Investment thesis🧵
But I think they're just getting started.
$LMND is also my highest conviction stock and biggest position in my portfolio.
Here's why 👇 Investment thesis🧵
2
1/ What does $LMND do 👇
$LMND is doing what no legacy insurer has got close to doing - build a vertically integrated, AI driven insurance platform.
They're much more than an InsureTech company. They're a software company offering insurance.
$LMND is doing what no legacy insurer has got close to doing - build a vertically integrated, AI driven insurance platform.
They're much more than an InsureTech company. They're a software company offering insurance.
1:20
3
2/ Total Addressable Market
The insurance market has the largest TAM out of healthcare, AI, oil, gas, and other multi-trillion-dollar industries.
Insurance is also one of the few trillion-dollar industries that has not been disrupted by AI making $LMND the big player in this digital revolution.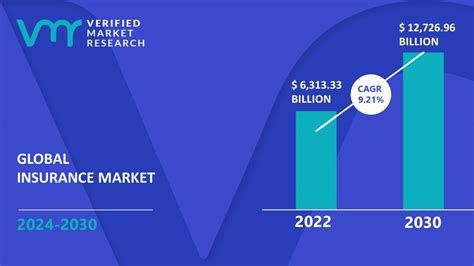
The insurance market has the largest TAM out of healthcare, AI, oil, gas, and other multi-trillion-dollar industries.
Insurance is also one of the few trillion-dollar industries that has not been disrupted by AI making $LMND the big player in this digital revolution.
4
3/ Growth
$LMND have grown their IFP by 845% in 4 years. In fact, $LMND has grown faster over the last year than $ALL has done in the last 5 years.
But what's more important here is:
- $LMND still has won less than 0.1% of the market share in most verticals.
- $LMND customers are young, digitally savvy, and loyal.
- Cross selling has not really begun yet.
5
4/ Opportunities For Growth
- Auto Insurance: If $LMND capture just less than 1% of the US auto market, they will more than 4x their IFP. - Cross Selling: One app, one login, one claims process. - International Expansion: $LMND's tech stack can expand across borders far quicker than legacy.
- Auto Insurance: If $LMND capture just less than 1% of the US auto market, they will more than 4x their IFP. - Cross Selling: One app, one login, one claims process. - International Expansion: $LMND's tech stack can expand across borders far quicker than legacy.
0:30
6
5/ Reinsurance Rework
$LMND recently reworked their reinsurance program, reducing reliance from 55% down to 20%.
This shows their confidence in their underwriting models. They've got to this stage in 10 years.
Imagine how good the models will be in another 10 years. Loss ratios down, revenue growth up, margins up.
$LMND recently reworked their reinsurance program, reducing reliance from 55% down to 20%.
This shows their confidence in their underwriting models. They've got to this stage in 10 years.
Imagine how good the models will be in another 10 years. Loss ratios down, revenue growth up, margins up.
7
6/ Profitability Inflection Point
$LMND margins increase with scale. Legacy incumbents margins can't increase with scale. Why?
Headcount is the main culprit.
$PGR IFP growth 2021-2024: 60% (and 35% headcount growth)
$LMND IFP growth 2021-2024: 130% (and 2% headcount growth)
@cybercatx
$LMND margins increase with scale. Legacy incumbents margins can't increase with scale. Why?
Headcount is the main culprit.
$PGR IFP growth 2021-2024: 60% (and 35% headcount growth)
$LMND IFP growth 2021-2024: 130% (and 2% headcount growth)
@cybercatx
8