Zeta ($ZETA) is extremely undervalued at 2.5x NTM sales. There's at...

Oliver | MMMT Wealth (CPA)@MMMTwealth
10 views
Jun 26, 2025
~2 min read
Advertisement
1
Zeta ($ZETA) is extremely undervalued at 2.5x NTM sales.
There's at least 100% upside available. Here's my quick thesis 👇🧵
There's at least 100% upside available. Here's my quick thesis 👇🧵
2
1. $ZETA is an AI powered marketing tech platform with one of the highest proprietary databases out of all peers allowing them to generate highly targeted engagement.
This has allowed them to boast:
- 114% net retention rate
- 548 customers spending +$100k per annum
- 159 customers spending +$1M per annum
This has allowed them to boast:
- 114% net retention rate
- 548 customers spending +$100k per annum
- 159 customers spending +$1M per annum
2:12
3
2. The MarTech industry is booming and $ZETA lead the way.
The MarTech industry is expected to hit $1.4T by 2030, growing at a CAGR of 20%. Most importantly, 35% of MarTech spend now aligns directly with AI and automation ($ZETA's niche).
Today, they have a tiny market share below 0.2%, but with the platform, and the wider market growth, if they can achieve ~1% of the market, they'll be worth billions.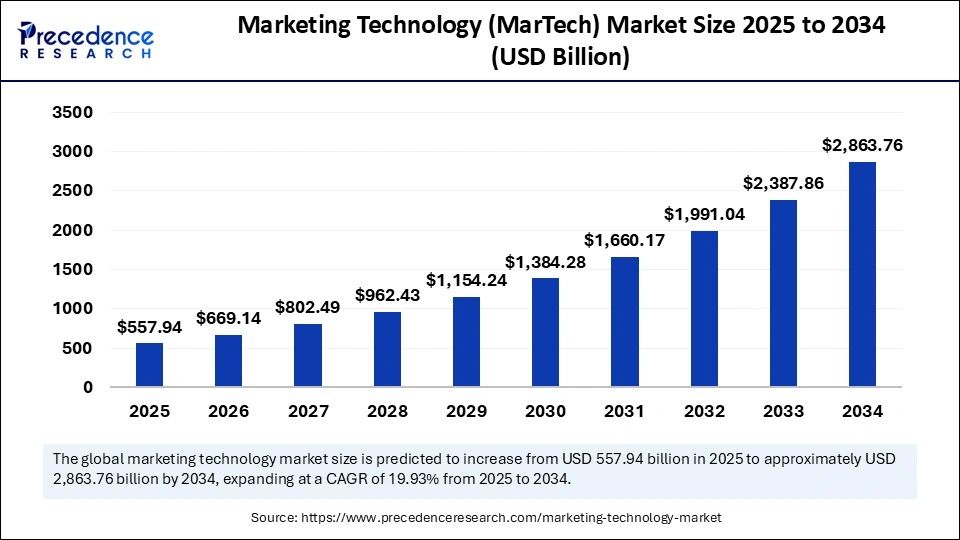
The MarTech industry is expected to hit $1.4T by 2030, growing at a CAGR of 20%. Most importantly, 35% of MarTech spend now aligns directly with AI and automation ($ZETA's niche).
Today, they have a tiny market share below 0.2%, but with the platform, and the wider market growth, if they can achieve ~1% of the market, they'll be worth billions.
4
3. $ZETA has now beaten revenue guidance (and raised) for 15 quarters in a row.
Here's the numbers today:
Revenue Growth: 36%
Adjusted EBITDA Growth: 53%
FCF Growth: 87%
On top of this high growth, it's important to realize that a lot of this growth is recurring. $ZETA platform revenue makes up 74% of total revenue today making it a very strong SaaS business deserving of high multiples.
5
4. Profitability Inflection is Coming Too
$ZETA is one of the few companies I know growing at these kind of rates...but profitably too.
Net income margins are now just below 0% whilst adj. EBITDA margins are at 17%. With scalable growth, increased ARPU, and costs remaining flat, this is a classic SaaS leverage that is starting to kick in.
$ZETA is one of the few companies I know growing at these kind of rates...but profitably too.
Net income margins are now just below 0% whilst adj. EBITDA margins are at 17%. With scalable growth, increased ARPU, and costs remaining flat, this is a classic SaaS leverage that is starting to kick in.
6
5. Valuation
$ZETA trades for just 12x NTM EBITDA and 2.5x Sales. For a SaaS company growing at 36% this is unheard of.
For reference, peers like $HUBS, $CRM, and $ADBE all trade for 8.5x, 5.8x, and 6.6x respectively all whilst growing far slower than $ZETA.
With an estimated $1.7B in revenue in FY27, and a conservative 5x multiple, $ZETA could easily trade at a $8.5B market cap, over 10% from today.
7