The endgame for $YCA & their 21.68Mlb #uranium (not end of deficit)...

Napalm@Napalm_1_
17 views
Aug 02, 2025
~3 min read
Advertisement
1
The endgame for $YCA & their 21.68Mlb #uranium (not end of deficit)
vs
Delays:
Phoenix=>8.4Mlb supply loss
Tumas=>3.6Mlb
Zuuvch Ovoo=>2x7Mlb
Arrow=>2x25Mlb
Mulga Rock
US producers slower ramp ups
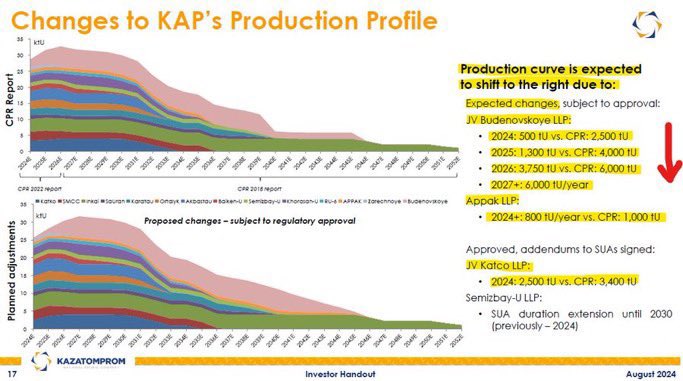
🇰🇿lower prod than previously hoped
Reactor restarts & licence extension
🧵1/n


vs
Delays:
Phoenix=>8.4Mlb supply loss
Tumas=>3.6Mlb
Zuuvch Ovoo=>2x7Mlb
Arrow=>2x25Mlb
Mulga Rock
US producers slower ramp ups
🇰🇿lower prod than previously hoped
Reactor restarts & licence extension
🧵1/n
Napalm@Napalm_1_
#Uranium supply sector is taken by surprise. It’s that simple
The utilities as global group are too late. They just don’t know it yet,bc they only look at their own needs
🇨🇳accelerating☢️reactor 🏗️,🇯🇵 restarting reactors & aiming to🏗️ new ones,🇺🇸 extends+restarts reactors
1/n
The utilities as global group are too late. They just don’t know it yet,bc they only look at their own needs
🇨🇳accelerating☢️reactor 🏗️,🇯🇵 restarting reactors & aiming to🏗️ new ones,🇺🇸 extends+restarts reactors
1/n
2
After🇨🇳,now🇪🇺🇺🇸want to stockpile more #uranium domestically for security reason
Me:Intermediaries will make $YCA takeover bid with backing of utilities & some producers
KAP UROY will possibly want YCA piece too to get lbs
But 1st awakening resulting in⬆️price will happen
2/n


Me:Intermediaries will make $YCA takeover bid with backing of utilities & some producers
KAP UROY will possibly want YCA piece too to get lbs
But 1st awakening resulting in⬆️price will happen
2/n
Napalm@Napalm_1_
With all lower #uranium productions 2024/2027 in🇺🇸🇰🇿🇳🇪 … than promised couple years ago, many producers produce less uranium than they have to deliver to clients in2024/2027
Once stakeholders & investors will understand that $YCA takeover is the only temporary solution:
1/3
Once stakeholders & investors will understand that $YCA takeover is the only temporary solution:
1/3
3
In2022/2024 the🌎 #uranium supply & demand models were over optimistic. They are now slowely adapting those models to the new reality of much bigger shortage ahead
In following posts couple examples of delays & production output being lower than promised in2022/2023
3/n
$YCA
In following posts couple examples of delays & production output being lower than promised in2022/2023
3/n
$YCA
4
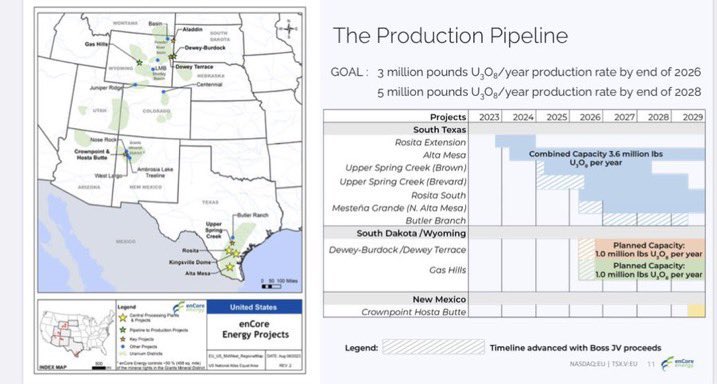
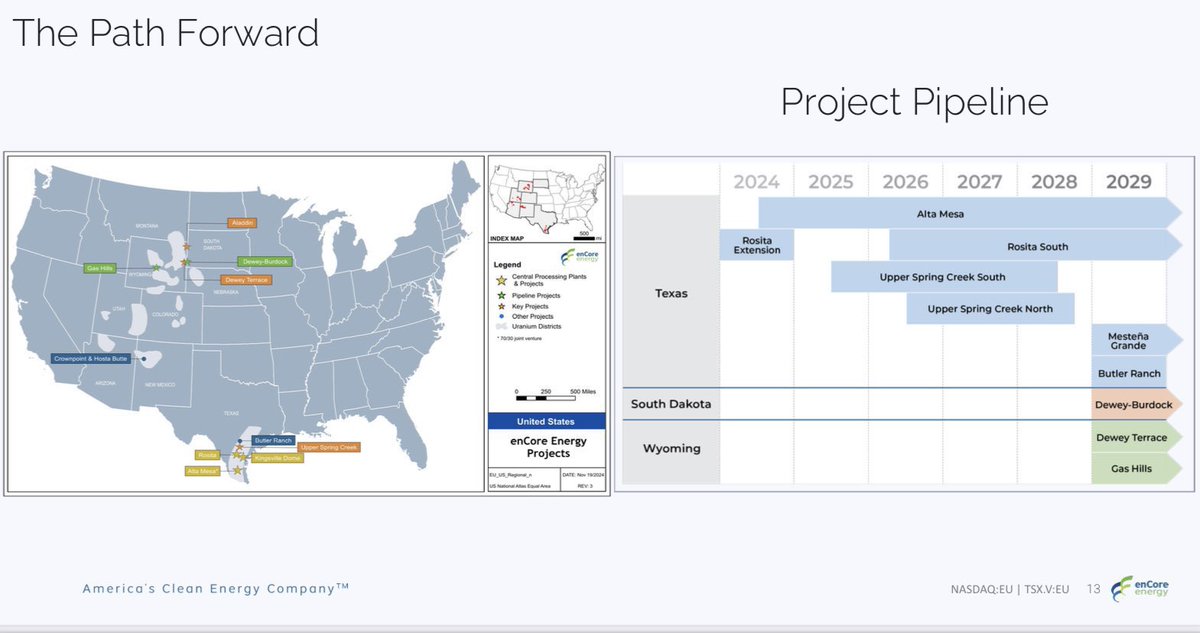
Encore Energy (EU) delays in #uranium production
& they borrowed 200klb from BOE in 2024 bc they produced less than hoped
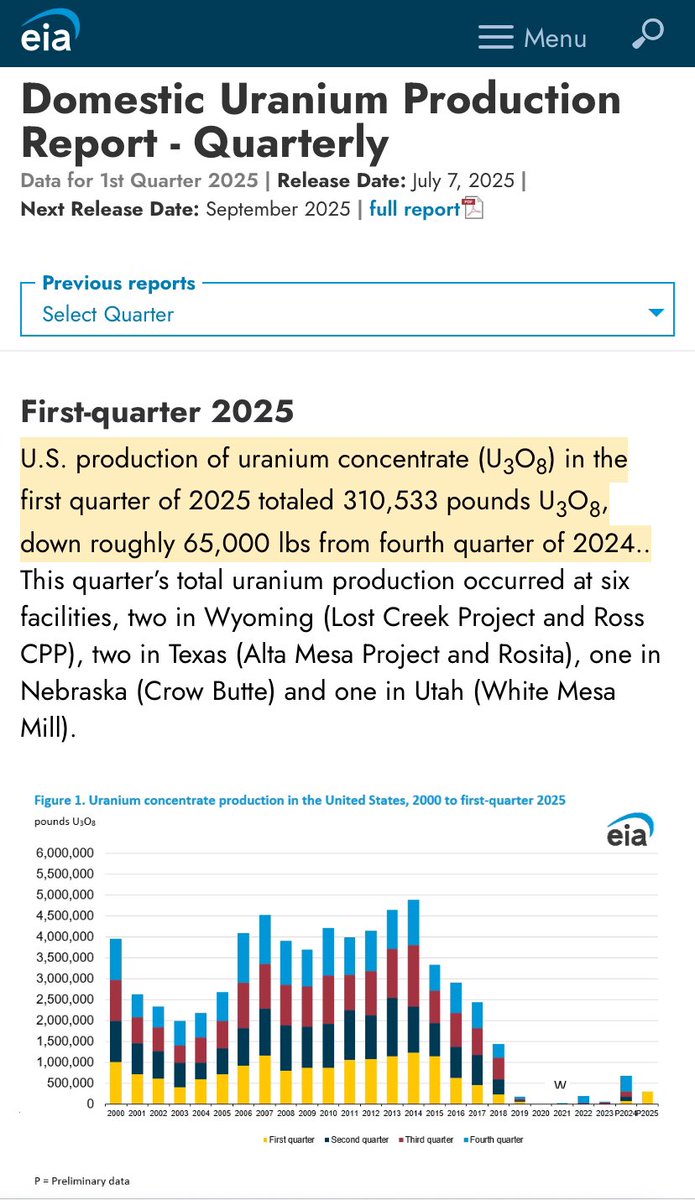
Total production of US miners (PEN UUUU URG EU UEC) didn’t even reach 1Mlb/y in2024 despite all their signed supply commitments towards clients
4/n
$YCA

& they borrowed 200klb from BOE in 2024 bc they produced less than hoped
Total production of US miners (PEN UUUU URG EU UEC) didn’t even reach 1Mlb/y in2024 despite all their signed supply commitments towards clients
4/n
$YCA
Napalm@Napalm_1_
Encore Energy also produced less uranium in2024/1H2025 than promised in2022/2023 = #uranium supply loss
& if you compare presentation of Encore Energy of 2y ago with the presentation today,you’ll notice they delayed uranium production too
No 5Mlb/y in 2028 anymore
$YCA $U.UN
& if you compare presentation of Encore Energy of 2y ago with the presentation today,you’ll notice they delayed uranium production too
No 5Mlb/y in 2028 anymore
$YCA $U.UN
5
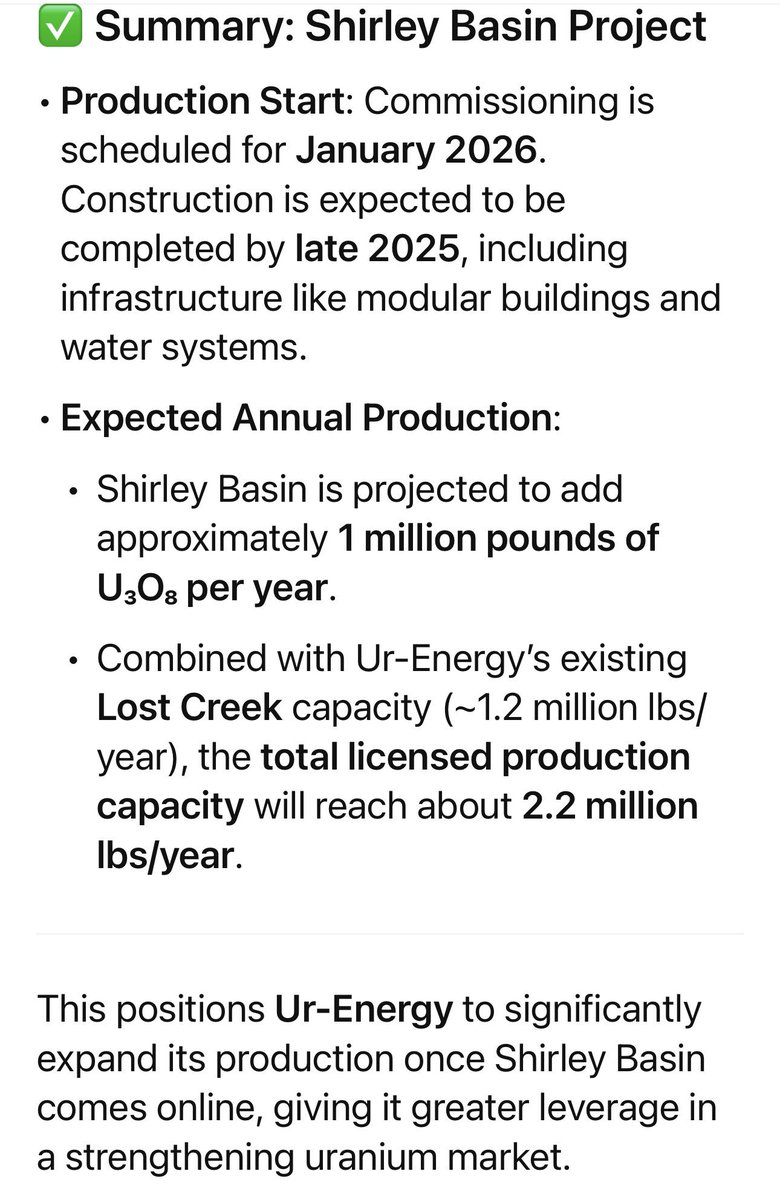
UR-Energy (URG) delayed production ramp ups too + failed to reach the level of output in 2024 promised from the Lost Creek in 2022/2023
Shirely Basin will be the same
5/n
$YCA
Shirely Basin will be the same
5/n
$YCA
Napalm@Napalm_1_
UR-Energy also produced less uranium in2024/2025 than promised in2022/2023 = #uranium supply loss
Promise 2022: 800klb produced from Lost Creek in 2024, add 1000klb from Shirely Basin in 2025
Reality: 266klb produced in 2024.
Shirely production start now in 2026
$YCA $U.UN
Promise 2022: 800klb produced from Lost Creek in 2024, add 1000klb from Shirely Basin in 2025
Reality: 266klb produced in 2024.
Shirely production start now in 2026
$YCA $U.UN
6
Uranium Energy Corp (UEC) keeps talking about their 8Mlb/y capacity for years, but they are nowhere in terms of #uranium production
I remember Amir saying >3y ago that UEC needed sustained 80USD/lb (inflation escalated) to start producing
CCJ said the same back then
6/n
$YCA

I remember Amir saying >3y ago that UEC needed sustained 80USD/lb (inflation escalated) to start producing
CCJ said the same back then
6/n
$YCA
Napalm@Napalm_1_
Uranium Energy Corp (~8Mlb/y capacity on paper!) in2021: “We are production ready”
Their total uranium production
2022: 0lb
2023: 0lb
2024: Christensen ISR mine restart in August => couple 10klb produced
2025: ?
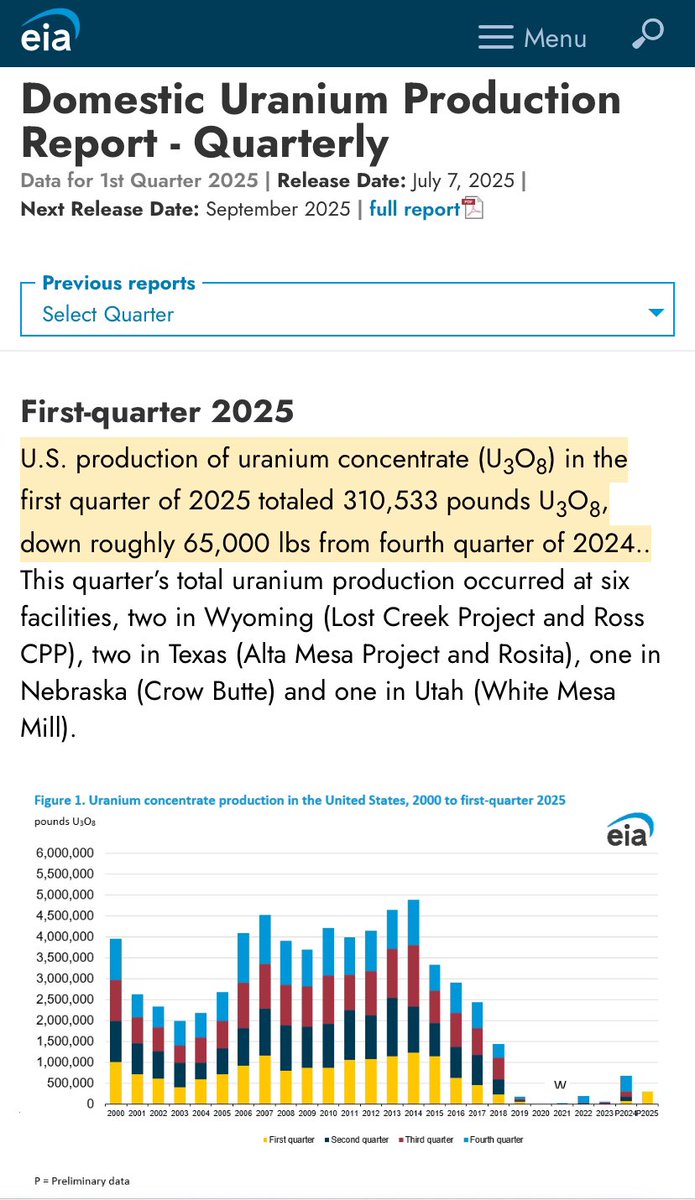
Total US #uranium production Q4 2024 375klb & 310klb in Q1 2025🤣
Their total uranium production
2022: 0lb
2023: 0lb
2024: Christensen ISR mine restart in August => couple 10klb produced
2025: ?
Total US #uranium production Q4 2024 375klb & 310klb in Q1 2025🤣
7
Peninsula Energy (PEN) just terminated 5.14Mlb of #uranium supply agreements with 🇺🇸 & 🇪🇺 utilities
Those utilities are now all of sudden uncovered
But Cameco, Orano & Kazatomprom are fully booked for 2026/2028
CCJ, Orano & KAP even need to buy in spot sometimes
7/n
$YCA


Those utilities are now all of sudden uncovered
But Cameco, Orano & Kazatomprom are fully booked for 2026/2028
CCJ, Orano & KAP even need to buy in spot sometimes
7/n
$YCA
Napalm@Napalm_1_
Peninsula Energy uranium “producer” terminates agreement to sell 5.14Mlb due to big production issues and delays = #uranium supply loss that was contracted => utilities need to find those 5.14Mlb elsewhere
$YCA $U.UN
$YCA $U.UN
8
Energy Fuels (UUUU) same. For years they talked about 2Mlb/y uranium production possible with little CAPEX needed…
& they now partially switch to REE (good move), 80USD/lb is just too low
Total US #uranium production Q4 2024 375klb & 310klb inQ1 2025🤣
8/n
$YCA
& they now partially switch to REE (good move), 80USD/lb is just too low
Total US #uranium production Q4 2024 375klb & 310klb inQ1 2025🤣
8/n
$YCA
9
And why is that important to talk about 2023/2025 production output failures?
Bc this made/makes those #uranium producers net uranium BUYERS!
Which reduced the secondary supply to a very low level. Mathematically that secondary supply is now gone.
9/n
$YCA $U.UN


Bc this made/makes those #uranium producers net uranium BUYERS!
Which reduced the secondary supply to a very low level. Mathematically that secondary supply is now gone.
9/n
$YCA $U.UN
Napalm@Napalm_1_
Hi everyone,
My detailed report (30 pages): “An important pivotal point has been reached. And the Uranium spotmarket is about to become much more tight”
See 30 pictures = 30 pages over a couple tweets.
$U.UN $YCA $URA $URNM $HURA $GCL #uranium
(1/6)
My detailed report (30 pages): “An important pivotal point has been reached. And the Uranium spotmarket is about to become much more tight”
See 30 pictures = 30 pages over a couple tweets.
$U.UN $YCA $URA $URNM $HURA $GCL #uranium
(1/6)
10
Inventory X (in my report of August 2023 & named inventory X starting in2024) is mathematically gone now.
Confirmed in 2H 2024 by UxC with the picture below
With inventory X gone,the🌎structural primary supply deficit can’t be compensated anymore
10/n
#uranium
$YCA $U.UN


Confirmed in 2H 2024 by UxC with the picture below
With inventory X gone,the🌎structural primary supply deficit can’t be compensated anymore
10/n
#uranium
$YCA $U.UN
Napalm@Napalm_1_
In August2023 I showed with 30pp report that the #uranium inventory created in2011-2017 (inventory X) used to compensate annual primary deficit since early2018 was now (2023) (close to be) depleted
Surprise. During high season that followed uranium spotprice went⬆️
(1/3)
$U.UN
Surprise. During high season that followed uranium spotprice went⬆️
(1/3)
$U.UN
11
With inventory X gone, the only solution to buy a bit of time (<1y) to compensate the primary supply deficit is through $YCA takeover bid
That was already known by some (but not the general investors) end2024
But now followes many announced #uranium development delays
11/n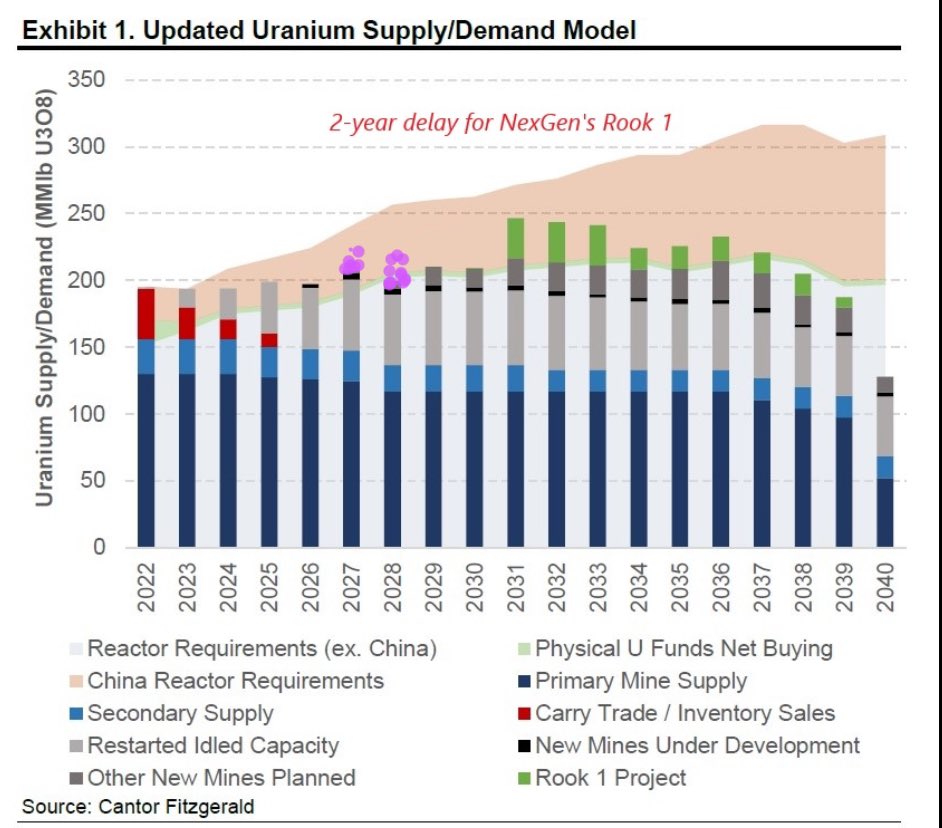

That was already known by some (but not the general investors) end2024
But now followes many announced #uranium development delays
11/n
12
February 2025: Denison mines delay = 8.4Mlb #uranium output lost
12/n
$YCA
12/n
$YCA
Napalm@Napalm_1_
February 2025: Denison mines again delaying the expected uranium production start of Phoenix (8.4Mlb/y) uranium project by 1 additional year = definitive 8.4 Mlb #uranium supply loss
$YCA $U.UN
$YCA $U.UN
13
Rook 1, Triple R, … additional #uranium development hurdles
13/n
$YCA

13/n
$YCA
Napalm@Napalm_1_
$YCA $U.UN
This alone would significantly delay the construction of the Patterson Lake South (Triple R) uranium mine (~9Mlb/y) & Arrow (Rook 1) uranium mine (~25Mlb/y) = several years of huge #uranium supply loss
This chart was before this requirement of unanimous approval
This alone would significantly delay the construction of the Patterson Lake South (Triple R) uranium mine (~9Mlb/y) & Arrow (Rook 1) uranium mine (~25Mlb/y) = several years of huge #uranium supply loss
This chart was before this requirement of unanimous approval
14
Arrow Rook 1 (NXE) delays = 2x25Mlb/y #uranium supply lost!
14/n
$YCA $U.UN


14/n
$YCA $U.UN
Napalm@Napalm_1_
NXE Arrow (Rook 1): biggest uranium project in🌎 (~29Mlb/y promised) needs at least 4y of construction before producing 1st #uranium lb!
But NXE didn’t start construction yet & will probably not start in2026 too
Early 2026+4y = early 2030
End 2026-> early 2031
1/2
$YCA $U.UN
But NXE didn’t start construction yet & will probably not start in2026 too
Early 2026+4y = early 2030
End 2026-> early 2031
1/2
$YCA $U.UN
15
April 2025: Tumas delay = 3.6Mlb #uranium output lost
15/n
$YCA
15/n
$YCA
Napalm@Napalm_1_
April 2025: Tumas (3.6Mlb/y) uranium project development delayed due to 80USD/lb being too low to justify the construction of the mine = 1y delay is 3.6Mlb #uranium supply loss
If 2y delay = 2 x 3.6Mlb definitive uranium supply loss
$YCA $U.UN
If 2y delay = 2 x 3.6Mlb definitive uranium supply loss
$YCA $U.UN
16
Zuuvch Ovoo delay = 2 x 7Mlb #uranium supply lost
16/n
$YCA
16/n
$YCA
Napalm@Napalm_1_
October 2024: Zuuvch Ovoo 7Mlb/y project at least delayed by 2y = 2 x 7Mlb/y #uranium supply loss
$YCA $U.UN
$YCA $U.UN
17
June/July 2025: Mulga Rock development delay => #uranium supply lost
17/n
$YCA
17/n
$YCA
Napalm@Napalm_1_
Mulga Rock DFS delayed from mid 2025 to Q3 2026 = #uranium supply loss
$YCA $U.UN
$YCA $U.UN
18
Paladin Energy #uranium production 2024 & 2025 lower than promised a couple years ago => lower primary supply = bigger primary supply deficit than previously expected, while secondary supply is now gone
18/n
$YCA
18/n
$YCA
Napalm@Napalm_1_
Paladin Energy today: Production for the financial year is expected to sit between 4M & 4.4M lbs of U3O8
In 2024: Paladin Energy lowered their production estimates 2 times last 18months
But in 2022/2023 PDN promised a 6Mlb/y production by now= #uranium supply loss
$YCA $U.UN
In 2024: Paladin Energy lowered their production estimates 2 times last 18months
But in 2022/2023 PDN promised a 6Mlb/y production by now= #uranium supply loss
$YCA $U.UN
19
Honeymoon future #uranium production probably lower than promised a couple years ago => lower primary supply = bigger primary supply deficit than previously expected, while secondary supply is now gone
19/n
$YCA


19/n
$YCA
Napalm@Napalm_1_
Honeymoon future production could be significantly lower than the promised 2.45Mlb/y = #uranium supply loss (1Mlb/y supply loss from Honeymoon?)
$YCA $U.UN
$YCA $U.UN
