$META stands as one of the largest and most immediate beneficiaries...

Mindset for Money@Mindset4Money_X
17 views
Dec 29, 2025
~5 min read
Advertisement
1
$META stands as one of the largest and most immediate beneficiaries of AI.
I believe $META has the potential to outperform analyst estimates and the broader market from here.
Today, I’ll explain why. 🧵👇
I believe $META has the potential to outperform analyst estimates and the broader market from here.
Today, I’ll explain why. 🧵👇
2
Most of this thesis rests on the strength of the core advertising business.
I believe both the models and the product quality in ads will outperform competitors over the next half decade.
An investment in $META today comes down to one core question:
Is the business strong enough at this valuation to withstand the risk of elevated capex?
I believe the answer is yes, and my goal is to lay that out clearly.
I believe both the models and the product quality in ads will outperform competitors over the next half decade.
An investment in $META today comes down to one core question:
Is the business strong enough at this valuation to withstand the risk of elevated capex?
I believe the answer is yes, and my goal is to lay that out clearly.
3
AI is improving the business today.
Management has already highlighted how new ad model architectures like Meta Lattice and Andromeda have reaccelerated performance.
Lattice drove a 3% gain in app conversions in Q3 2025, while Andromeda improved ad quality by 14%.
These gains may seem incremental, but they widen $META's lead over competitors. This is exactly why management is confident enough to keep pressing forward.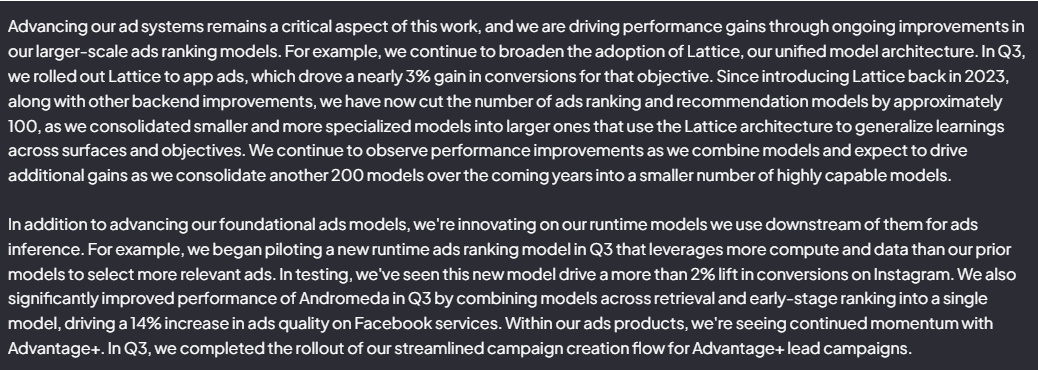
Management has already highlighted how new ad model architectures like Meta Lattice and Andromeda have reaccelerated performance.
Lattice drove a 3% gain in app conversions in Q3 2025, while Andromeda improved ad quality by 14%.
These gains may seem incremental, but they widen $META's lead over competitors. This is exactly why management is confident enough to keep pressing forward.
4
I’ll repeat it: AI is improving the business today.
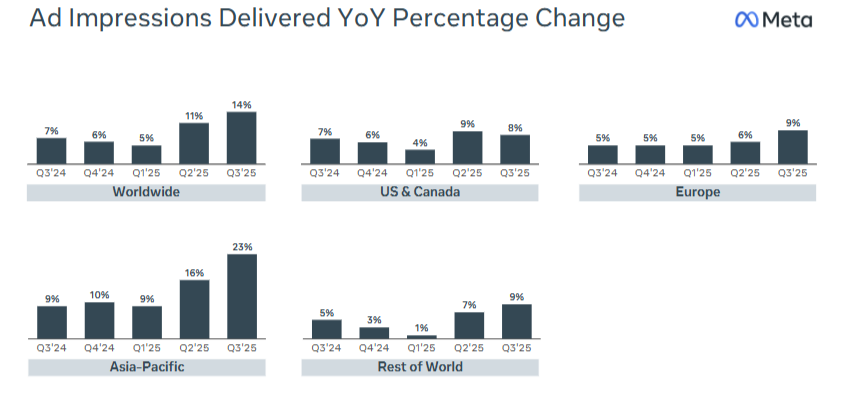
In Q3 2025, average price per ad rose 10% while ad impressions increased 14%.
Instagram video time spent grew 30% YoY.
This matters. $META basically only controls two levers: how much ad space they sell and the price they sell it for.
The core business is clearly investable here, especially relative to other large scale ad platforms trading at higher multiples.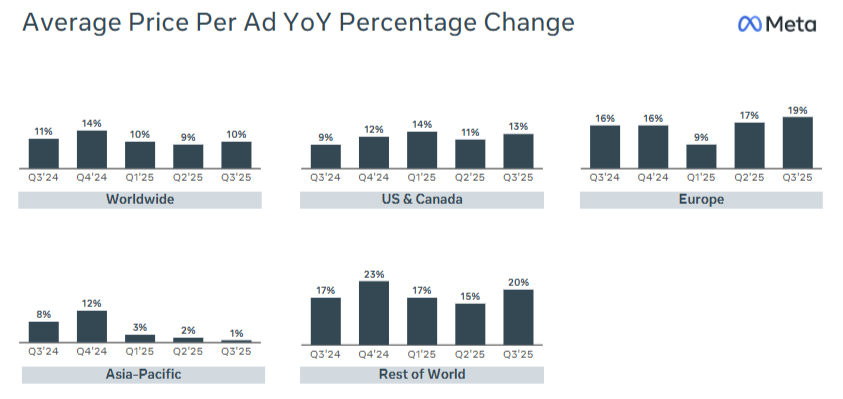
In Q3 2025, average price per ad rose 10% while ad impressions increased 14%.
Instagram video time spent grew 30% YoY.
This matters. $META basically only controls two levers: how much ad space they sell and the price they sell it for.
The core business is clearly investable here, especially relative to other large scale ad platforms trading at higher multiples.
5
Now let’s address CAPEX.
While some companies are rewarded for aggressive investment cycles, $META is being punished.
Some of this skepticism is justified:
- Zuckerbergs previous spending spree was a bit mismanaged (but lets keep in mind this investment eventually proved necessary)
- $META is spending more aggressively relative to its size than peers.
These are real risks. But as Zuckerberg has stated, these investments are foundational, not optional. Its also worth noting that $META is a younger business than its mature peers and thus is expected to grow into this spend.
While some companies are rewarded for aggressive investment cycles, $META is being punished.
Some of this skepticism is justified:
- Zuckerbergs previous spending spree was a bit mismanaged (but lets keep in mind this investment eventually proved necessary)
- $META is spending more aggressively relative to its size than peers.
These are real risks. But as Zuckerberg has stated, these investments are foundational, not optional. Its also worth noting that $META is a younger business than its mature peers and thus is expected to grow into this spend.
6
Why spend so much on data centers? How does this pay off?
The core business is compute constrained (and energy).
AI requires massive compute, and $META runs inference on virtually every post and ad you see in real time.
More compute allows deeper, more precise prediction models that improve engagement and monetization.
That directly translates into higher revenue per user.
In 2022, Zuckerberg invested aggressively in H100s, ordering roughly twice the capacity Meta needed at the time. Their rationale was "always want to have enough capacity to build something they cant quite see on the horizon". While this investment seemed expensive at the time, it resulted in EXTREME growth in their ad revenues and time spent on their applications.
Compute is multipurpose. Assets like Prometheus and Hyperion will support multiple business needs across the company. It is obviously expensive, but so far it has remained quite affordable and should continue to be over the next year.
This move is both defensive and offensive, and therefore necessary.
The core business is compute constrained (and energy).
AI requires massive compute, and $META runs inference on virtually every post and ad you see in real time.
More compute allows deeper, more precise prediction models that improve engagement and monetization.
That directly translates into higher revenue per user.
In 2022, Zuckerberg invested aggressively in H100s, ordering roughly twice the capacity Meta needed at the time. Their rationale was "always want to have enough capacity to build something they cant quite see on the horizon". While this investment seemed expensive at the time, it resulted in EXTREME growth in their ad revenues and time spent on their applications.
Compute is multipurpose. Assets like Prometheus and Hyperion will support multiple business needs across the company. It is obviously expensive, but so far it has remained quite affordable and should continue to be over the next year.
This move is both defensive and offensive, and therefore necessary.
2:33
7
The moat here is massive and still expanding.
Despite numerous new entrants, none have meaningfully threatened $META's position.
They serve over 3.5B users. This is obvious.
The only force with real penetration power today is government regulation.
As compute is deployed and scaled internally, the barrier to entry rises further. Reels is a clear example of how $META can absorb competitive pressure and emerge stronger. There is evidence of this moat.
Despite numerous new entrants, none have meaningfully threatened $META's position.
They serve over 3.5B users. This is obvious.
The only force with real penetration power today is government regulation.
As compute is deployed and scaled internally, the barrier to entry rises further. Reels is a clear example of how $META can absorb competitive pressure and emerge stronger. There is evidence of this moat.
8
A few additional operational pros and cons that must be considered:
Cons:
- Reality Labs has burned $71B since 2021 while generating just $2B in LTM revenue
- EU regulation poses risk to ad revenue, which represents 23% of total ad sales
- Youth safety litigation in 2026 could be material
- Competitors like Google, Apple can gatekeep features, data.
Pros:
- Founder led, with a relatively young founder still deeply involved
- WhatsApp monetization remains significantly underappreciated
- GPUs are multipurpose and retain value even if AGI timelines slip
msn.com/en-us/money/co…
Cons:
- Reality Labs has burned $71B since 2021 while generating just $2B in LTM revenue
- EU regulation poses risk to ad revenue, which represents 23% of total ad sales
- Youth safety litigation in 2026 could be material
- Competitors like Google, Apple can gatekeep features, data.
Pros:
- Founder led, with a relatively young founder still deeply involved
- WhatsApp monetization remains significantly underappreciated
- GPUs are multipurpose and retain value even if AGI timelines slip
msn.com/en-us/money/co…
9
Financials:
$META has funded these investments primarily through cash and a "lease" with Blue Owl Capital.
As spending scales in 2026, free cash flow could temporarily turn negative with CAPEX projected north of $100B.
That sounds alarming, but operating cash flows continue to grow. Op margins remain above 40%, even as depreciation rose 32% YoY.
It’s also worth noting that previous investments in ad infrastructure delivered exceptional returns, as reflected in $META's long term ROIC.


$META has funded these investments primarily through cash and a "lease" with Blue Owl Capital.
As spending scales in 2026, free cash flow could temporarily turn negative with CAPEX projected north of $100B.
That sounds alarming, but operating cash flows continue to grow. Op margins remain above 40%, even as depreciation rose 32% YoY.
It’s also worth noting that previous investments in ad infrastructure delivered exceptional returns, as reflected in $META's long term ROIC.
10
Valuation:
$META is not a screaming bargain, but it is strong value.
At a fwd multiple of 25x and consensus EPS of $33.21 in 2027, the stock would trade around $830.
That implies roughly a 12% CAGR and a 24% 2yr return.
I view consensus estimates as a conservative floor. Wall Street is heavily discounting future depreciation tied to current CAPEX and not enough upside.
What they are not fully pricing in:
- A 30% budget cut to Reality Labs, roughly $5B in savings
- Continued efficiency gains from AI models like Andromeda and Lattice
- The recent reacceleration in revenue growth to 26%, which could suggest stronger future performance, while forecasts call for 14 -15% CAGR.
I see a plausible path to $38 EPS in 2027, implying a ~$950 stock price and a 21% CAGR.
Next year will be a "show me" period, of which I believe $META will perform better than expected.
This is not financial advice :)
$META is not a screaming bargain, but it is strong value.
At a fwd multiple of 25x and consensus EPS of $33.21 in 2027, the stock would trade around $830.
That implies roughly a 12% CAGR and a 24% 2yr return.
I view consensus estimates as a conservative floor. Wall Street is heavily discounting future depreciation tied to current CAPEX and not enough upside.
What they are not fully pricing in:
- A 30% budget cut to Reality Labs, roughly $5B in savings
- Continued efficiency gains from AI models like Andromeda and Lattice
- The recent reacceleration in revenue growth to 26%, which could suggest stronger future performance, while forecasts call for 14 -15% CAGR.
I see a plausible path to $38 EPS in 2027, implying a ~$950 stock price and a 21% CAGR.
Next year will be a "show me" period, of which I believe $META will perform better than expected.
This is not financial advice :)
11
What do you think? Is $META a buy today?
Please like and follow if you enjoyed, and have a great day!
If you want to build charts and research stocks like me, try Fiscal for free!
fiscal.ai/?via=MFM
Please like and follow if you enjoyed, and have a great day!
If you want to build charts and research stocks like me, try Fiscal for free!
fiscal.ai/?via=MFM
