Tin Deep Dive - Part 1 🧵 We’ll cover one by one both the producers...

Kacper Piotr Kaminski@Kacper_PK_CH
43 views
Jan 09, 2026
~9 min read
Advertisement
1
Tin Deep Dive - Part 1 🧵
We’ll cover one by one both the producers and developers/explorers that make up the investable universe for this metal - breaking down fundamentals and charts. Enjoy!
Producers (majority revenue from tin):
• Alphamin Resources $AFM (TSXV) – Materials 🇨🇦
• Andrada Mining $ATM (LSE AIM) – Materials 🇬🇧
• Metals X $MLX (ASX) – Materials 🇦🇺
• Malaysia Smelting Corporation $5916 (Bursa Malaysia) 🇲🇾
• PT Timah $TINS (IDX) 🇮🇩
• Minsur S.A. $MINSURI1 (BVL) 🇵🇪
• Yunnan Tin Company $000960 (SZSE) 🇨🇳
Developers / Explorers:
• Cornish Metals $CUSN (LSE AIM, TSXV) 🇬🇧🇨🇦
• First Tin $1SN (LSE) 🇬🇧
• Elementos Limited $ELT (ASX) 🇦🇺
• Stellar Resources $SRZ (ASX) 🇦🇺
• TinOne Resources $TORC (TSXV) 🇨🇦
• Tincorp Metals $TIN (TSXV) 🇨🇦
• Rome Resources $RMR (LSE AIM) 🇬🇧
• Eloro Resources $ELO (TSX) 🇨🇦
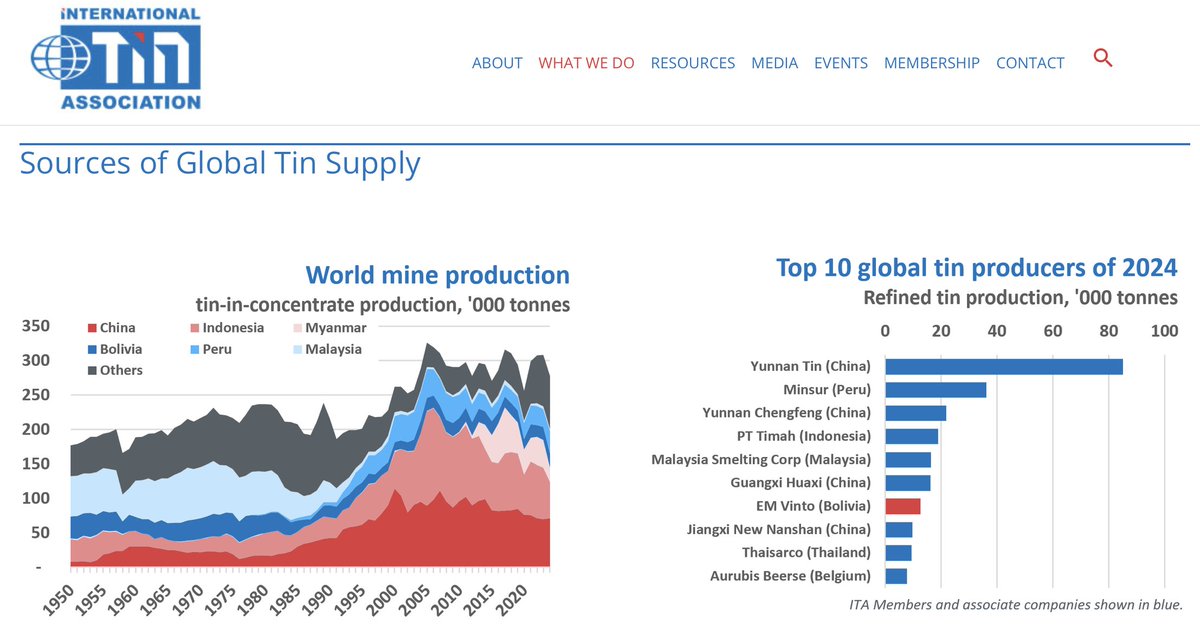
We’ll cover one by one both the producers and developers/explorers that make up the investable universe for this metal - breaking down fundamentals and charts. Enjoy!
Producers (majority revenue from tin):
• Alphamin Resources $AFM (TSXV) – Materials 🇨🇦
• Andrada Mining $ATM (LSE AIM) – Materials 🇬🇧
• Metals X $MLX (ASX) – Materials 🇦🇺
• Malaysia Smelting Corporation $5916 (Bursa Malaysia) 🇲🇾
• PT Timah $TINS (IDX) 🇮🇩
• Minsur S.A. $MINSURI1 (BVL) 🇵🇪
• Yunnan Tin Company $000960 (SZSE) 🇨🇳
Developers / Explorers:
• Cornish Metals $CUSN (LSE AIM, TSXV) 🇬🇧🇨🇦
• First Tin $1SN (LSE) 🇬🇧
• Elementos Limited $ELT (ASX) 🇦🇺
• Stellar Resources $SRZ (ASX) 🇦🇺
• TinOne Resources $TORC (TSXV) 🇨🇦
• Tincorp Metals $TIN (TSXV) 🇨🇦
• Rome Resources $RMR (LSE AIM) 🇬🇧
• Eloro Resources $ELO (TSX) 🇨🇦
Kacper Piotr Kaminski@Kacper_PK_CH
Tin Deep Dive in preparation - $SN
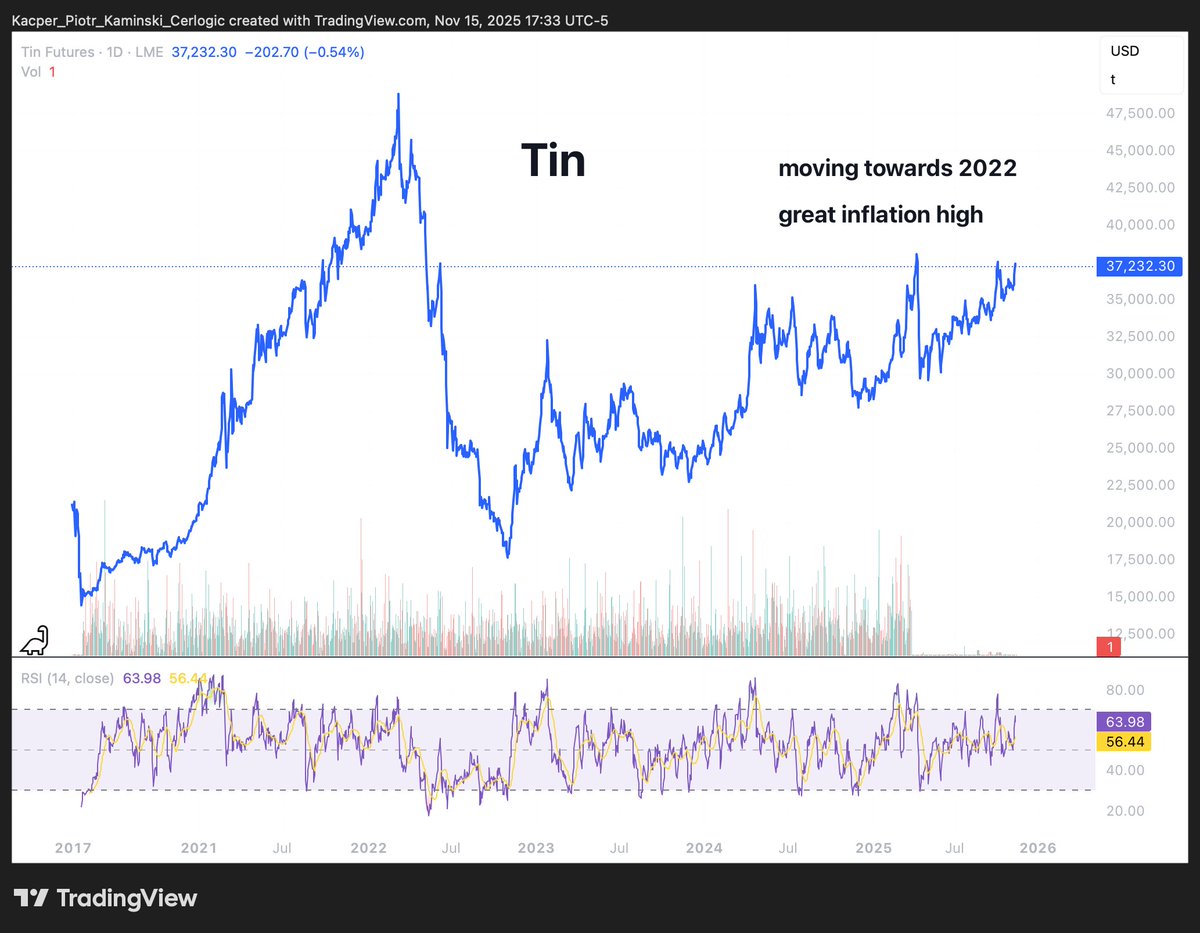
Largely forgotten metal, yet Tin is trading almost back at the great-inflation highs of 2022.
There are very few ways to get pure exposure to this price surge. We’ve got of course $AFM – Alphamin, printing money at these levels, but there are a few other interesting names worth a closer look as well.
Largely forgotten metal, yet Tin is trading almost back at the great-inflation highs of 2022.
There are very few ways to get pure exposure to this price surge. We’ve got of course $AFM – Alphamin, printing money at these levels, but there are a few other interesting names worth a closer look as well.
2
Tin Deep Dive - Part 2 🧵
Alphamin Resources $AFM (TSXV)🇨🇦
We’ve got to start with perhaps the most popular tin company out there. It’s in the DRC, so you’ve got to be comfortable with jurisdiction risk. Long life, expansion completed, low cost producer, you can find everything you could wish for here.
Now to the chart. We all want to know whether it’s a bargain after all. Let’s put it this way: if I were a larger shareholder, I would hold my position and enjoy the ride, looking for a trend change as a signal to exit. If I weren’t, I’d probably wait for a larger pullback like we saw in March April this year, or less dramatic one.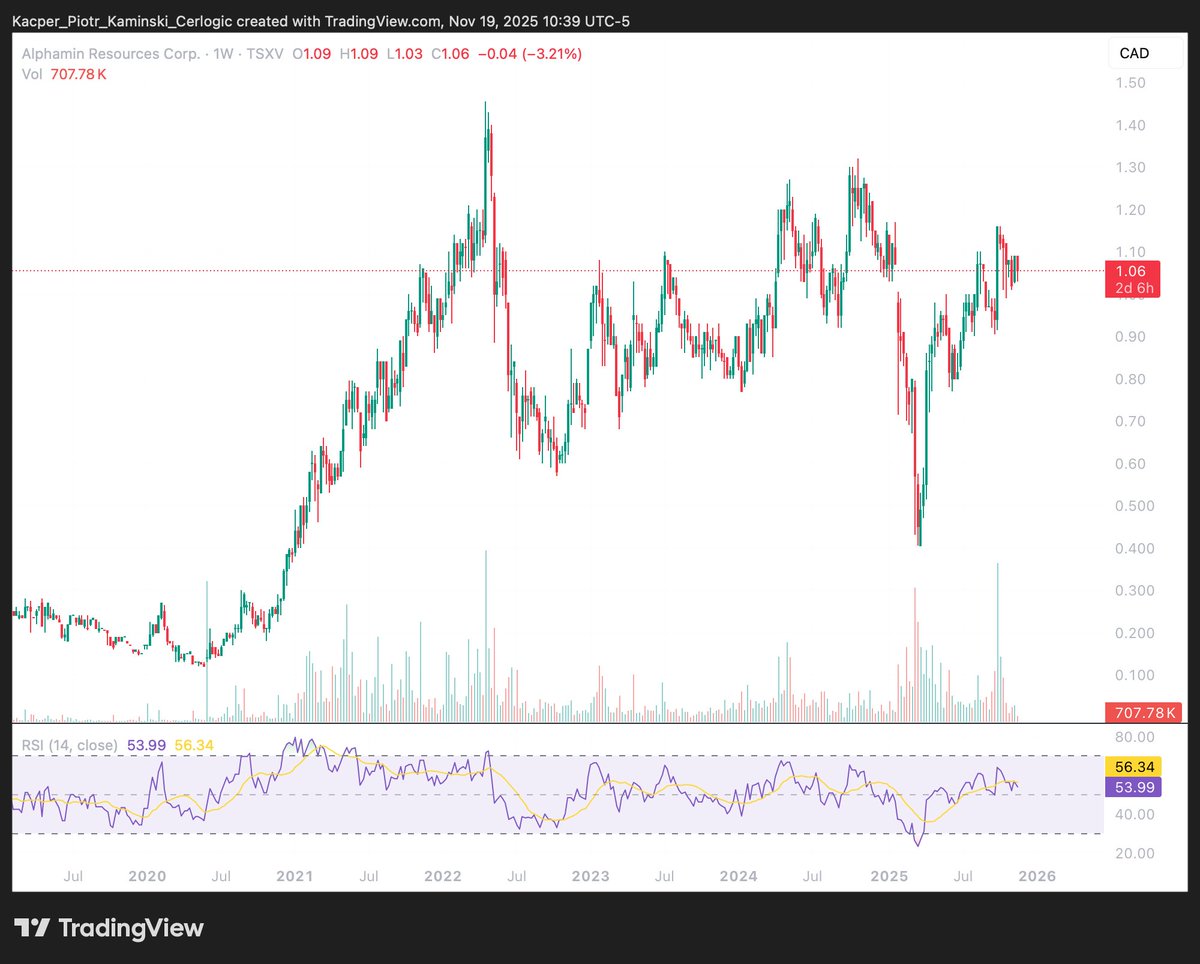
Alphamin Resources $AFM (TSXV)🇨🇦
We’ve got to start with perhaps the most popular tin company out there. It’s in the DRC, so you’ve got to be comfortable with jurisdiction risk. Long life, expansion completed, low cost producer, you can find everything you could wish for here.
Now to the chart. We all want to know whether it’s a bargain after all. Let’s put it this way: if I were a larger shareholder, I would hold my position and enjoy the ride, looking for a trend change as a signal to exit. If I weren’t, I’d probably wait for a larger pullback like we saw in March April this year, or less dramatic one.
3
Tin Deep Dive - Part 3 🧵
Andrada Mining $ATM (LSE AIM) 🇬🇧
Uis mine in Namibia is producing tin and tantalum, with recent expansions raising throughput and achieving over 90% plant availability. Revenue is growing, but the company is still loss-making for now.
It’s also worth noting that Andrada has entered an earn-in agreement with SQM to develop its Lithium Ridge project. Promising overall, with a good chance they achieve profitability in the next 12–24 months if the tin price remains supportive.
Now to the chart. The price certainly reflects market skepticism, but that in itself can be an opportunity. It’s a rather small-cap name, so volatility is to be expected. A solid play if tin prices continue higher, putting it firmly on our watchlist.
Andrada Mining $ATM (LSE AIM) 🇬🇧
Uis mine in Namibia is producing tin and tantalum, with recent expansions raising throughput and achieving over 90% plant availability. Revenue is growing, but the company is still loss-making for now.
It’s also worth noting that Andrada has entered an earn-in agreement with SQM to develop its Lithium Ridge project. Promising overall, with a good chance they achieve profitability in the next 12–24 months if the tin price remains supportive.
Now to the chart. The price certainly reflects market skepticism, but that in itself can be an opportunity. It’s a rather small-cap name, so volatility is to be expected. A solid play if tin prices continue higher, putting it firmly on our watchlist.
4
Tin Deep Dive - Part 4 🧵
Metals X $MLX (ASX) – Materials 🇦🇺
Well, what can we say? A simply fantastic run: growing revenues, strong cash generation, and the largest tin producer in Australia. One can dream about this level of execution, I certainly wish we saw it more often in this sector.
Now to the chart. It has clearly repriced much higher over the last few years. At this stage it’s really a play on tin prices if one decides to become a shareholder. Production is expected to remain stable in the coming years, unless execution and margins improve significantly.
Furthermore, Metals X discloses strategic investments in tin developers - Elementos Limited $ELT and First Tin $1SN. So you're getting more than just Metals X when you buy the stock.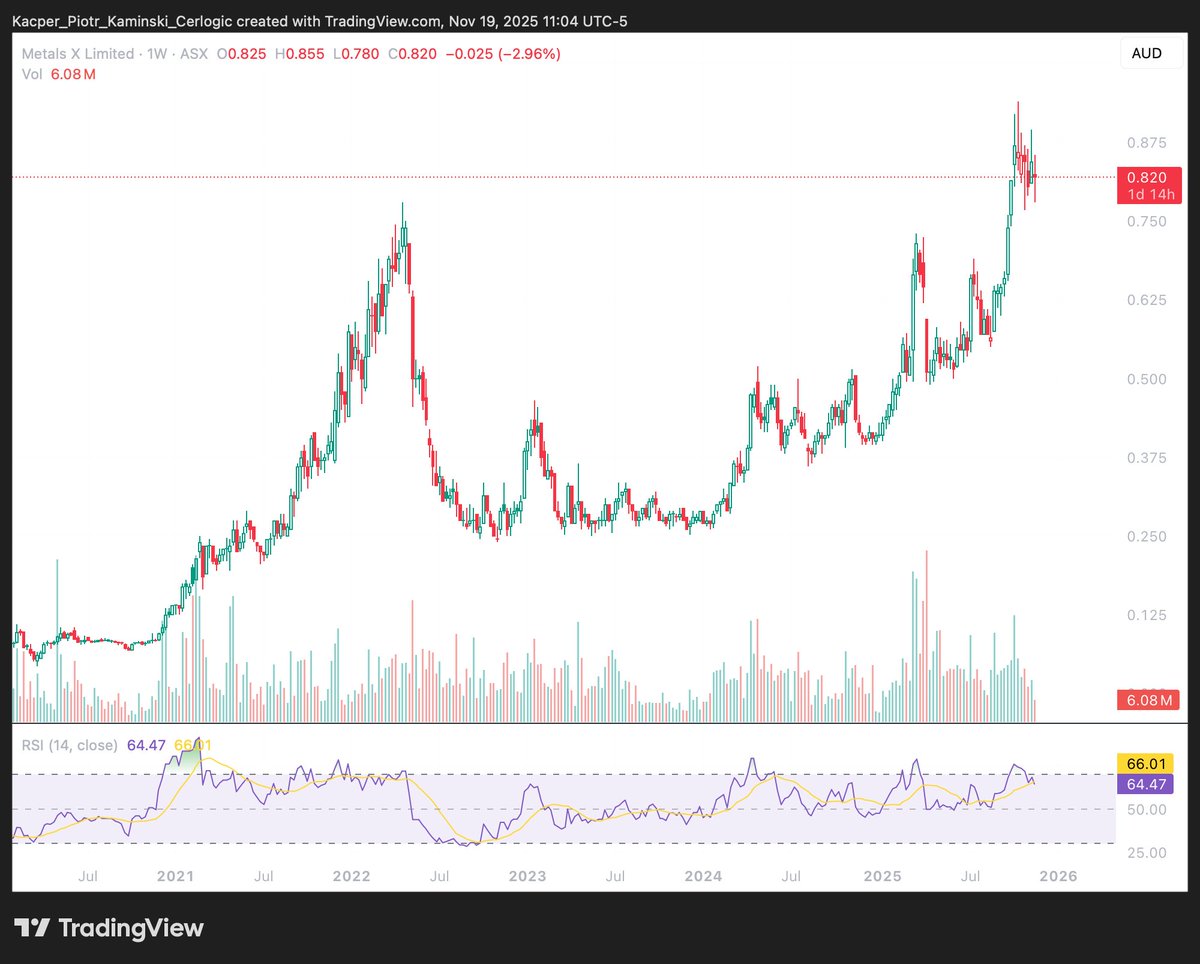
Metals X $MLX (ASX) – Materials 🇦🇺
Well, what can we say? A simply fantastic run: growing revenues, strong cash generation, and the largest tin producer in Australia. One can dream about this level of execution, I certainly wish we saw it more often in this sector.
Now to the chart. It has clearly repriced much higher over the last few years. At this stage it’s really a play on tin prices if one decides to become a shareholder. Production is expected to remain stable in the coming years, unless execution and margins improve significantly.
Furthermore, Metals X discloses strategic investments in tin developers - Elementos Limited $ELT and First Tin $1SN. So you're getting more than just Metals X when you buy the stock.
5
Tin Deep Dive - Part 5 🧵
Malaysia Smelting Corporation $MSC (Bursa Malaysia) 🇲🇾
Fully integrated tin producer, operating both tin mining and tin smelting/refining. Fairly priced now, and it should perform well in a bull market.
It also trades as $NPW in Singapore, but it’s still not easily accessible for everyone depending on the broker. We’re skipping this one on our potential buy list not because we found anything wrong with it, but because there are other great opportunities out there.
Malaysia Smelting Corporation $MSC (Bursa Malaysia) 🇲🇾
Fully integrated tin producer, operating both tin mining and tin smelting/refining. Fairly priced now, and it should perform well in a bull market.
It also trades as $NPW in Singapore, but it’s still not easily accessible for everyone depending on the broker. We’re skipping this one on our potential buy list not because we found anything wrong with it, but because there are other great opportunities out there.
6
Tin Deep Dive - Part 6 🧵
PT Timah $TINS (IDX) 🇮🇩
Indonesia’s state-linked tin giant, one of the world’s largest refined tin producers. On the regulatory front it benefits from Indonesia’s change in its concession areas, it could reduce competition, but we have to be careful.
Now to the chart. The recent move has been enormous, a clear repricing. Overbought, chasing here carries elevated risk. The chart calls for patience, especially as the company is fairly priced at the moment.
PT Timah $TINS (IDX) 🇮🇩
Indonesia’s state-linked tin giant, one of the world’s largest refined tin producers. On the regulatory front it benefits from Indonesia’s change in its concession areas, it could reduce competition, but we have to be careful.
Now to the chart. The recent move has been enormous, a clear repricing. Overbought, chasing here carries elevated risk. The chart calls for patience, especially as the company is fairly priced at the moment.
7
Tin Deep Dive - Part 7 🧵
Minsur S.A. $MINSURI1 (BVL) 🇵🇪
Time to travel to Peru! A large producer, but here things are a bit more complicated. A significant share of revenue comes from copper and gold, yet it remains one of the world’s largest tin producers. Not a bad thing if you prefer to limit risk and avoid being dependent on a single metal.
It has been highly profitable since 2020 and has paid substantial dividends. With potentially growing production, I’d be interested in owning it. Putting it straight onto the potential buy list.
Minsur S.A. $MINSURI1 (BVL) 🇵🇪
Time to travel to Peru! A large producer, but here things are a bit more complicated. A significant share of revenue comes from copper and gold, yet it remains one of the world’s largest tin producers. Not a bad thing if you prefer to limit risk and avoid being dependent on a single metal.
It has been highly profitable since 2020 and has paid substantial dividends. With potentially growing production, I’d be interested in owning it. Putting it straight onto the potential buy list.
8
Tin Deep Dive - Part 8 🧵
Yunnan Tin Company $000960 (SZSE) 🇨🇳
Major integrated tin producer in China, engaged in mining and smelting of tin and other non-ferrous metals. Its revenue base is diversified beyond tin, including copper, zinc, indium and various tin chemicals, which means it is not a pure tin story.
As for trading it, you really need a good broker to access the Shenzhen market. If someone is interested anyways, I would say it is fairly valued at this point, and I certainly would not chase it. We are looking for asymmetrical opportunities after all!
Yunnan Tin Company $000960 (SZSE) 🇨🇳
Major integrated tin producer in China, engaged in mining and smelting of tin and other non-ferrous metals. Its revenue base is diversified beyond tin, including copper, zinc, indium and various tin chemicals, which means it is not a pure tin story.
As for trading it, you really need a good broker to access the Shenzhen market. If someone is interested anyways, I would say it is fairly valued at this point, and I certainly would not chase it. We are looking for asymmetrical opportunities after all!
9
Tin Deep Dive - Part 9 🧵
We're moving to developers / explorers, it'll be interesting, we often find great opportunities here!
Cornish Metals $CUSN (LSE AIM, TSXV) 🇬🇧🇨🇦
I love history, so we can start there. Cornwall is one of the world’s oldest tin-producing regions, with continuous mining dating back to the Bronze Age and significant activity during Roman times.
Cornish Metals owns the fully permitted South Crofty project in Cornwall, one of the highest-grade undeveloped tin assets in the West. The economics are strong, and there is a clear path toward production once dewatering and refurbishment milestones are completed.
As a pre-production developer this is a higher-risk, higher-reward play, and any positive or negative news on progress or funding tends to move the chart quickly. The updated PEA projects South Crofty to generate roughly £70 million in annual EBITDA in its early production years. Definitely one of my favorites, assuming the long-term tin story continues to unfold.
We're moving to developers / explorers, it'll be interesting, we often find great opportunities here!
Cornish Metals $CUSN (LSE AIM, TSXV) 🇬🇧🇨🇦
I love history, so we can start there. Cornwall is one of the world’s oldest tin-producing regions, with continuous mining dating back to the Bronze Age and significant activity during Roman times.
Cornish Metals owns the fully permitted South Crofty project in Cornwall, one of the highest-grade undeveloped tin assets in the West. The economics are strong, and there is a clear path toward production once dewatering and refurbishment milestones are completed.
As a pre-production developer this is a higher-risk, higher-reward play, and any positive or negative news on progress or funding tends to move the chart quickly. The updated PEA projects South Crofty to generate roughly £70 million in annual EBITDA in its early production years. Definitely one of my favorites, assuming the long-term tin story continues to unfold.
10
Tin Deep Dive - Part 10 🧵
First Tin $1SN (LSE) 🇬🇧
The company started trading right at the top of the previous commodity cycle, and it is no surprise it fell a long way from there. It is a junior after all. Only later did it finally settle into a bottom around the 4p to 6p range (£).
That is when Metals X $MLX came in with a strategic move and took a major position. They first bought about 23% of the company in July 2024 and later pushed that holding to nearly 30% by November 2024.
A solid speculation for a bull market. First Tin owns two advanced tin projects, the Taronga Tin Project in Australia and the Tellerhäuser Tin Project in Germany, both located in low jurisdictions.
First Tin $1SN (LSE) 🇬🇧
The company started trading right at the top of the previous commodity cycle, and it is no surprise it fell a long way from there. It is a junior after all. Only later did it finally settle into a bottom around the 4p to 6p range (£).
That is when Metals X $MLX came in with a strategic move and took a major position. They first bought about 23% of the company in July 2024 and later pushed that holding to nearly 30% by November 2024.
A solid speculation for a bull market. First Tin owns two advanced tin projects, the Taronga Tin Project in Australia and the Tellerhäuser Tin Project in Germany, both located in low jurisdictions.
11
Tin Deep Dive - Part 11 🧵
Elementos Limited $ELT (ASX) 🇦🇺
Another junior that went through the usual ups and downs together with metal prices. One really has to be careful when trading these names because they often move in ways that feel disconnected from fundamentals, even when the project itself is solid.
Elementos declined heavily from the 2022 cycle peak and only truly found a bottom this year. It then received a strong boost from a strategic private placement by, you guessed it .. Metals X $MLX. They invested $5 million $AUD and took 20% of the company. Whoever makes those acquisition decisions deserves a bonus.
A solid speculation for the bull market, though I would not chase it here. Elementos holds two mature tin projects, the Oropesa Tin Project in Andalusia, Spain with a completed DFS, and the Cleveland Tin Project in Tasmania, Australia.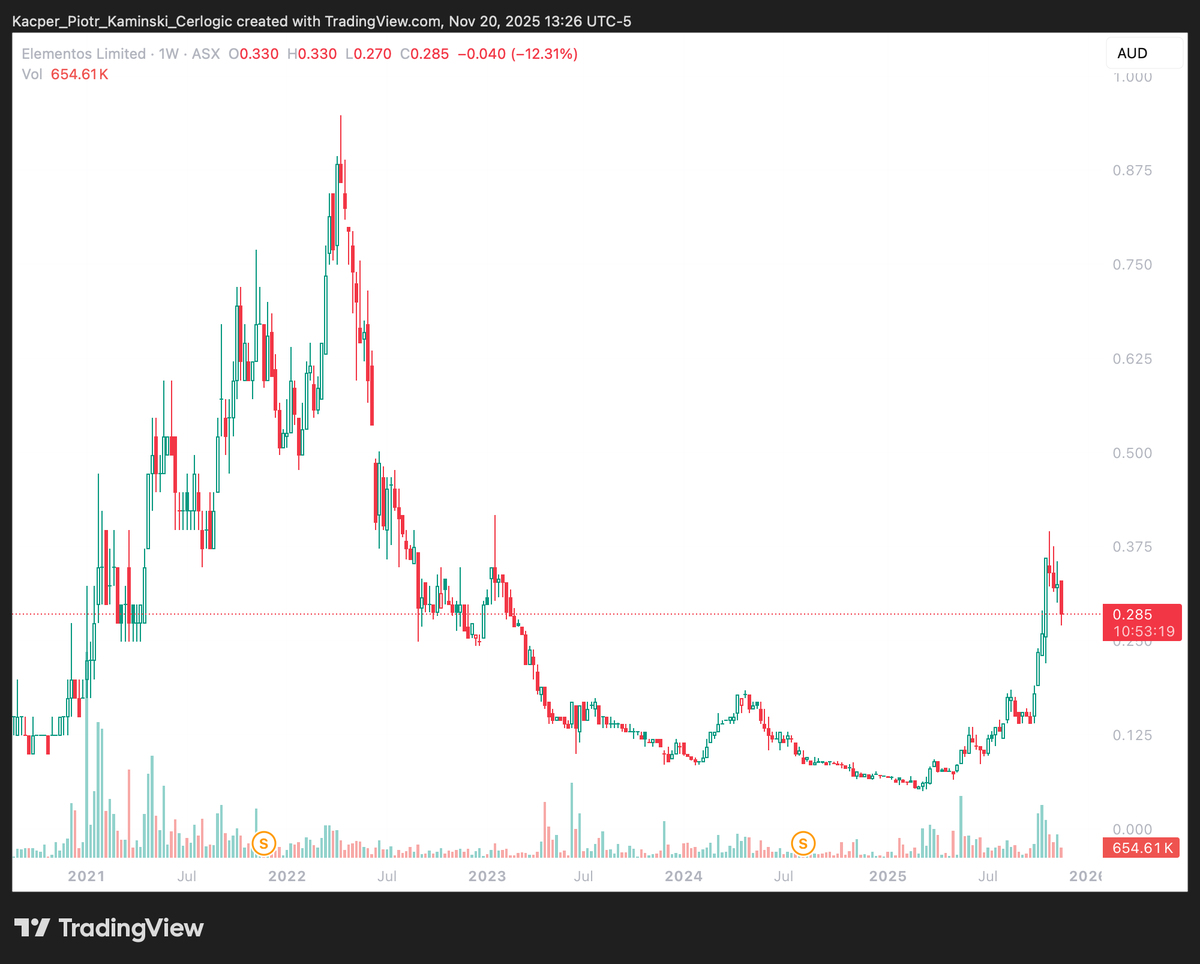
Elementos Limited $ELT (ASX) 🇦🇺
Another junior that went through the usual ups and downs together with metal prices. One really has to be careful when trading these names because they often move in ways that feel disconnected from fundamentals, even when the project itself is solid.
Elementos declined heavily from the 2022 cycle peak and only truly found a bottom this year. It then received a strong boost from a strategic private placement by, you guessed it .. Metals X $MLX. They invested $5 million $AUD and took 20% of the company. Whoever makes those acquisition decisions deserves a bonus.
A solid speculation for the bull market, though I would not chase it here. Elementos holds two mature tin projects, the Oropesa Tin Project in Andalusia, Spain with a completed DFS, and the Cleveland Tin Project in Tasmania, Australia.
12
Tin Deep Dive - Part 12 🧵
Stellar Resources $SRZ (ASX) 🇦🇺
They are advancing the 100%-owned Heemskirk Tin Project in Tasmania, regarded as the highest-grade undeveloped tin resource in Australia and the third-highest globally. The company is still in the development stage, so all value depends on resource expansion, study progress and eventually securing financing.
The share price has its usual ups and downs, and in situations like this I prefer buying panic, which we may or may not get at some point. What will drive this one forward are clear project milestones such as drilling results, resource updates, PFS and DFS progress, funding decisions and of course the broader tin price.
High reward potential, but you need to be comfortable with junior-mine risk.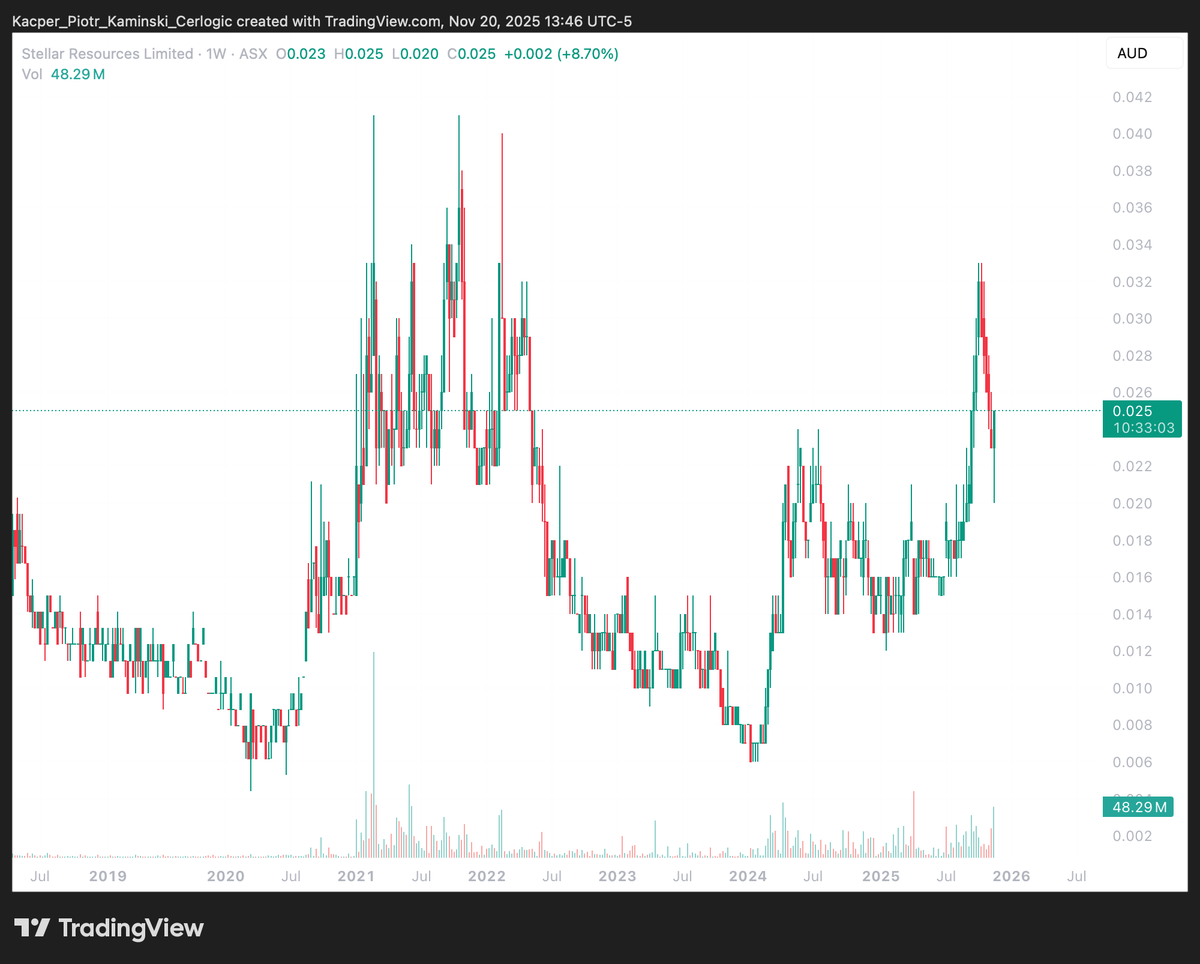
Stellar Resources $SRZ (ASX) 🇦🇺
They are advancing the 100%-owned Heemskirk Tin Project in Tasmania, regarded as the highest-grade undeveloped tin resource in Australia and the third-highest globally. The company is still in the development stage, so all value depends on resource expansion, study progress and eventually securing financing.
The share price has its usual ups and downs, and in situations like this I prefer buying panic, which we may or may not get at some point. What will drive this one forward are clear project milestones such as drilling results, resource updates, PFS and DFS progress, funding decisions and of course the broader tin price.
High reward potential, but you need to be comfortable with junior-mine risk.
13
Tin Deep Dive - Part 13 🧵
TinOne Resources $TORC (TSXV) 🇨🇦
Micro cap, now below $2M CAD, and it even completed a private placement recently. The market seems to think it is unsalvageable, but we will see about that.
It is a high-risk junior explorer, yet at these levels it is essentially priced for zero. The company holds several tin projects in Tasmania, including Great Pyramid and Aberfoyle.
As always with explorers, everything depends on resource growth, future studies and securing funding when the time comes. Any meaningful discovery or upgrade could move the share price sharply because expectations are extremely low.
One for the watchlist if you are comfortable with speculation and want maximum risk leverage to the tin cycle.
TinOne Resources $TORC (TSXV) 🇨🇦
Micro cap, now below $2M CAD, and it even completed a private placement recently. The market seems to think it is unsalvageable, but we will see about that.
It is a high-risk junior explorer, yet at these levels it is essentially priced for zero. The company holds several tin projects in Tasmania, including Great Pyramid and Aberfoyle.
As always with explorers, everything depends on resource growth, future studies and securing funding when the time comes. Any meaningful discovery or upgrade could move the share price sharply because expectations are extremely low.
One for the watchlist if you are comfortable with speculation and want maximum risk leverage to the tin cycle.
14
Tin Deep Dive - Part 14 🧵
Tincorp Metals $TIN (TSXV) 🇨🇦
Another micro-cap, early-stage tin explorer focused on the Porvenir and SF Tin Projects in Bolivia’s prolific Oruro tin belt.
As with all junior explorers the peril is real, success depends on drilling, permitting, financing. At current levels the market is clearly discounting much of that optionality. One worth watching if you’re comfortable with a high-risk, high-leverage play in the tin cycle.
Tincorp Metals $TIN (TSXV) 🇨🇦
Another micro-cap, early-stage tin explorer focused on the Porvenir and SF Tin Projects in Bolivia’s prolific Oruro tin belt.
As with all junior explorers the peril is real, success depends on drilling, permitting, financing. At current levels the market is clearly discounting much of that optionality. One worth watching if you’re comfortable with a high-risk, high-leverage play in the tin cycle.
15
Tin Deep Dive - Part 15 🧵
Rome Resources $RMR (LSE AIM) 🇬🇧
Drilling strategically located tin projects just 8 km north of Alphamin’s $AFM high-grade Mpama deposits in the DRC. Results could be expected soon.
High-risk jurisdiction, but genuine exploration upside; a strong resource announcement could rapidly re-rate the stock.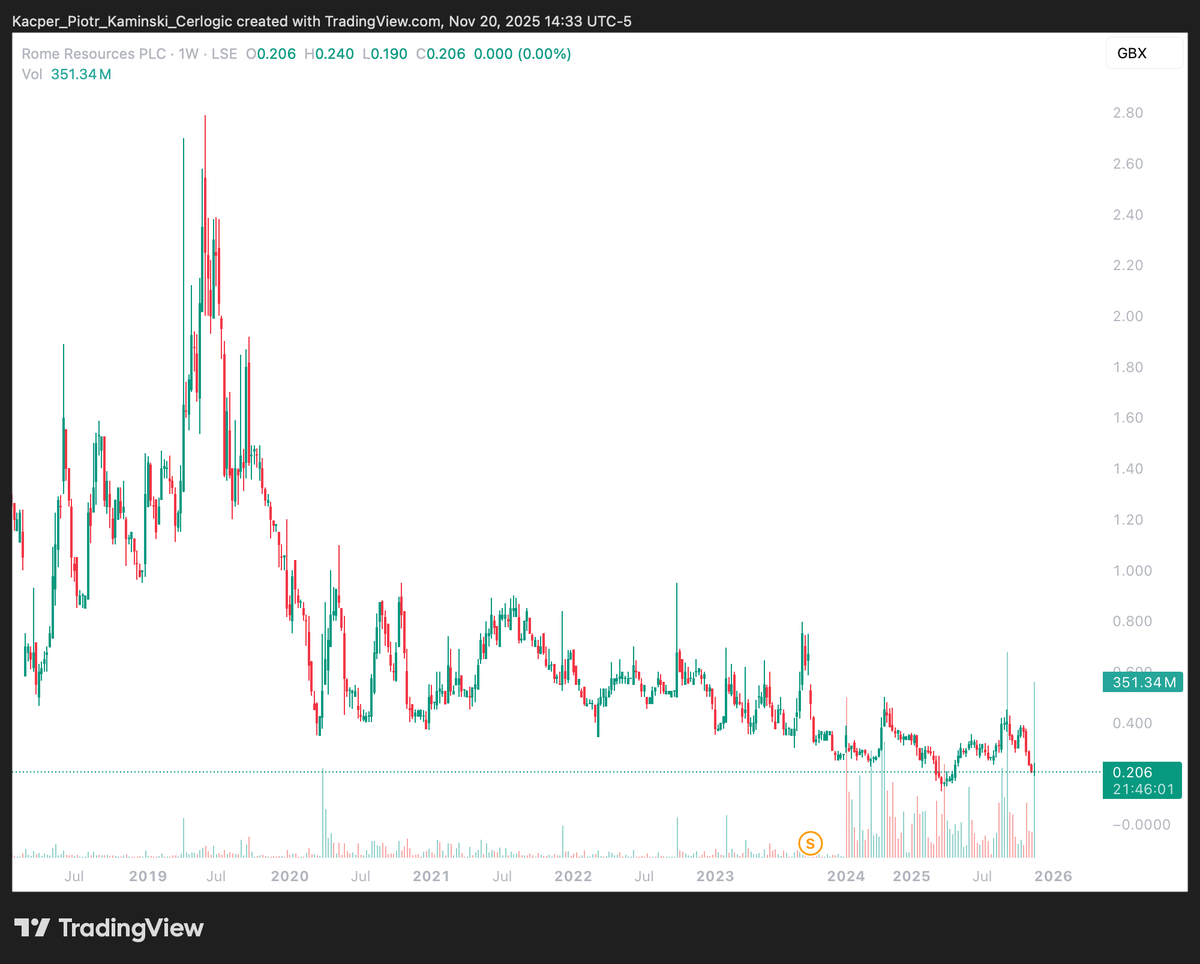
Rome Resources $RMR (LSE AIM) 🇬🇧
Drilling strategically located tin projects just 8 km north of Alphamin’s $AFM high-grade Mpama deposits in the DRC. Results could be expected soon.
High-risk jurisdiction, but genuine exploration upside; a strong resource announcement could rapidly re-rate the stock.
16
Tin Deep Dive - Part 16 🧵
Eloro Resources $ELO (TSX) 🇨🇦
Not purely tin play. They are advancing the large Iska Iska silver–tin polymetallic project in Bolivia. The project hosts 298 million ounces of contained silver according to the company reports, a serious number for any early-stage explorer. On top of that, the resource outlines 130,000 tonnes of contained tin.
I’m interested, as in any large-scale project. High risk as always at this stage, but the sheer scale makes it one of the most compelling tin–silver growth stories in the sector. I'm digging further into fundamentals.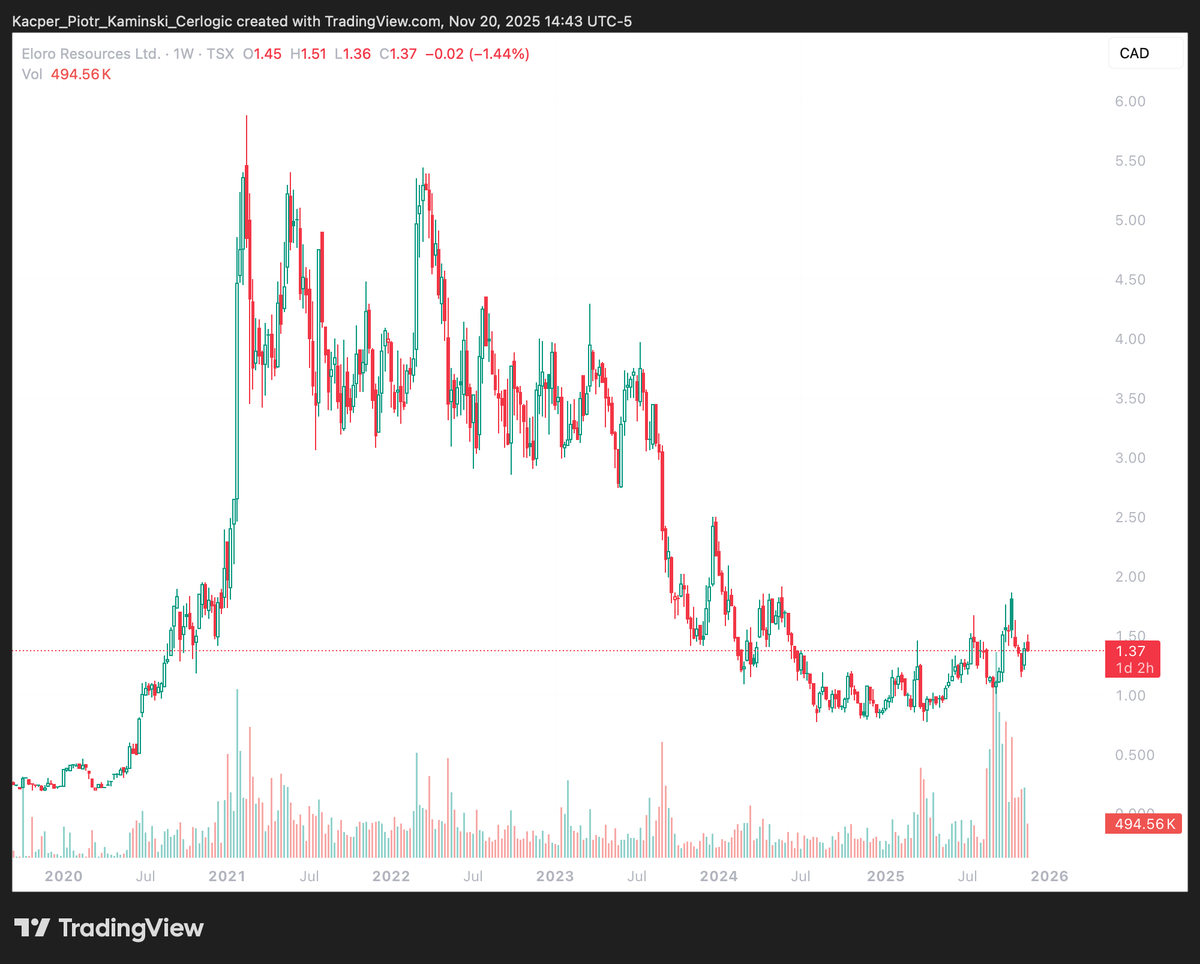
Eloro Resources $ELO (TSX) 🇨🇦
Not purely tin play. They are advancing the large Iska Iska silver–tin polymetallic project in Bolivia. The project hosts 298 million ounces of contained silver according to the company reports, a serious number for any early-stage explorer. On top of that, the resource outlines 130,000 tonnes of contained tin.
I’m interested, as in any large-scale project. High risk as always at this stage, but the sheer scale makes it one of the most compelling tin–silver growth stories in the sector. I'm digging further into fundamentals.
