$RBRK is a high quality, yet underappreciated cybersecurity...

Investing visuals@InvestingVisual
26 views
Sep 28, 2025
~4 min read
Advertisement
1
$RBRK is a high quality, yet underappreciated cybersecurity business.
Let's break it down!
• How they make money
• Sentiment
• Geography
• Business segments
• Financials
• Cash
• Margins
• Valuation
• My thoughts: would I buy it?
Time to dive in 🧵👇
Let's break it down!
• How they make money
• Sentiment
• Geography
• Business segments
• Financials
• Cash
• Margins
• Valuation
• My thoughts: would I buy it?
Time to dive in 🧵👇
2
1 - How they make money
First things first: what does $RBRK actually do?
$RBRK specializes in data protection (backup and recovery), threat detection and analytics, sensitive-data governance, and disaster/cyber recovery.
It's a software platform that protects data across local databases (on-premises) and public clouds. They aim to shorten time-to-recovery after ransomware or insider events.
$RBRK monetization relies on subscriptions. Customers typically start small (protecting specific workloads) then expand over time.
They are not yet making money, but recently turned free cash flow positive.
3
2 - Sentiment
According to @Stocktwits, $RBRK sentiment is currently neutral.
Over the past year, the stock fluctuated between $50 and $100, making it quite volatile. This is quite normal to see for businesses in hypergrowth mode like $RBRK.
According to @Stocktwits, $RBRK sentiment is currently neutral.
Over the past year, the stock fluctuated between $50 and $100, making it quite volatile. This is quite normal to see for businesses in hypergrowth mode like $RBRK.
4
3 - Geography
About ~68% of $RBRK's revenue is from the U.S.
Bipul Sinha, $RBRK's co-founder and CEO said they see a “substantial international opportunity,” and "plans to expand its global footprint".
This can be a great growth lever for $RBRK in the years ahead.
About ~68% of $RBRK's revenue is from the U.S.
Bipul Sinha, $RBRK's co-founder and CEO said they see a “substantial international opportunity,” and "plans to expand its global footprint".
This can be a great growth lever for $RBRK in the years ahead.
5
4 - Business segments
$RBRK is a software-as-a-service (SaaS) business with the majority of it's revenue coming from recurring subscriptions.
Their main product areas:
• Data Protection; ensures backups, replication, archival, and restores.
• Cyber Recovery: helps detect ransomware or breach activity, isolate threats, simulate clean restores.
• Identity Security: protects identity infrastructures and recovers identity objects if compromised.
• AI Acceleration: helps automate threat detection, anomaly detection, preemptive recovery and speeding up threat-response workflows.
As their mission summarizes: secure the world’s data.
6
5 - Financials
$RBRK became free cash flow positive this year, marking an important inflection point. If we look at revenue, $RBRK shows some impressive growth so far. Growing from $150M to $299M quarterly revenue in three years.
From their Q2 2025:
“We delivered a strong quarter with exceptional top-line growth and significant cash flow margin. We continue to build towards a highly profitable growth business.” -- Bipul Sinha, CEO
7
6 - Margins
Both $RBRK gross margins and free cash flow margins are trending in the right direction. Increasing gross margins signal a strong competitive position, while free cash flow margins show profitability at scale.
This kind of operating leverage is exactly what you would like to see as an investor.
Both $RBRK gross margins and free cash flow margins are trending in the right direction. Increasing gross margins signal a strong competitive position, while free cash flow margins show profitability at scale.
This kind of operating leverage is exactly what you would like to see as an investor.
8
7 - Cash
$RBRK is debt-free and has $355 million cash on hand which can fuel their long term growth, geographic expansion and potential strategic acquisitions.
It's likely to see their cash balance increase as operating leverage kicks in over the next few quarters.
$RBRK is debt-free and has $355 million cash on hand which can fuel their long term growth, geographic expansion and potential strategic acquisitions.
It's likely to see their cash balance increase as operating leverage kicks in over the next few quarters.
9
8 - Valuation
$RBRK currently trades at 11x price to forward revenue, which is very reasonable if we compare it to peers:
Ranked from highest to lowest based on price to forward revenue:
• $CRWD: 23x at 24% annual growth
• $ZS: 14x at 23% annual growth
• $PANW: 13x at 15% annual growth
• $RBRK: 11x at 43% annual growth
In short: $RBRK is trading at half the valuation of $CRWD while growing nearly twice as fast.
10
9 - My thoughts: would I buy it?
Before I answer that question, lets first evaluation their competitive advantages and risks in some more detail.
Competitive advantages:
• High switching costs: $RBRK is deeply embedded in IT processes, recovery workflows, and compliance.
Migration is complex and risky, creating customer stickiness.
• Product leadership. $RBRK fused security outcomes with backup. They are recognized as a Leader by Gartner for six years.
• Brand and trust. Known for ransomware recovery and bold $10M warranty. They are trusted by many CIOs and CISOs.
• Ecosystem and channel. Partnerships with Microsoft/Azure, AWS; heavy channel leverage extends reach.
Scale advantage: ~$1B run-rate revenue, 6,100+ customers, and repeatable playbooks give it efficient scale despite smaller resources than giants.
Risks
• Competition. Cohesity–Veritas scale, Veeam’s growth, legacy vendors, cloud natives; they could pressure pricing/margins.
• Security/product risk. Any recovery failure or vulnerability could tarnish trust.
• Macro cycles. IT budget tightening delays deals. U.S. dominance (68%) exposes macro/geopolitical swings.
To summarize
$RBRK is a great business positioned right at the intersection of data, security, and AI. They have a mission-critical product, have executed very well so far, are founder-led, operating leverage is kicking in, and the stock isn’t trading at a nosebleed valuation. Yes, there are risks to be aware off, but so far $RBRK is in a great spot.
So, would I buy it? Definitely. And I already have. I shared this new position with a group of early supporters in a soon-to-launch service.
I'll share more about that soon!
11
10 - $RBRK snapshot
$RBRK is a high quality and founder led data security company, trading at a reasonable valuation.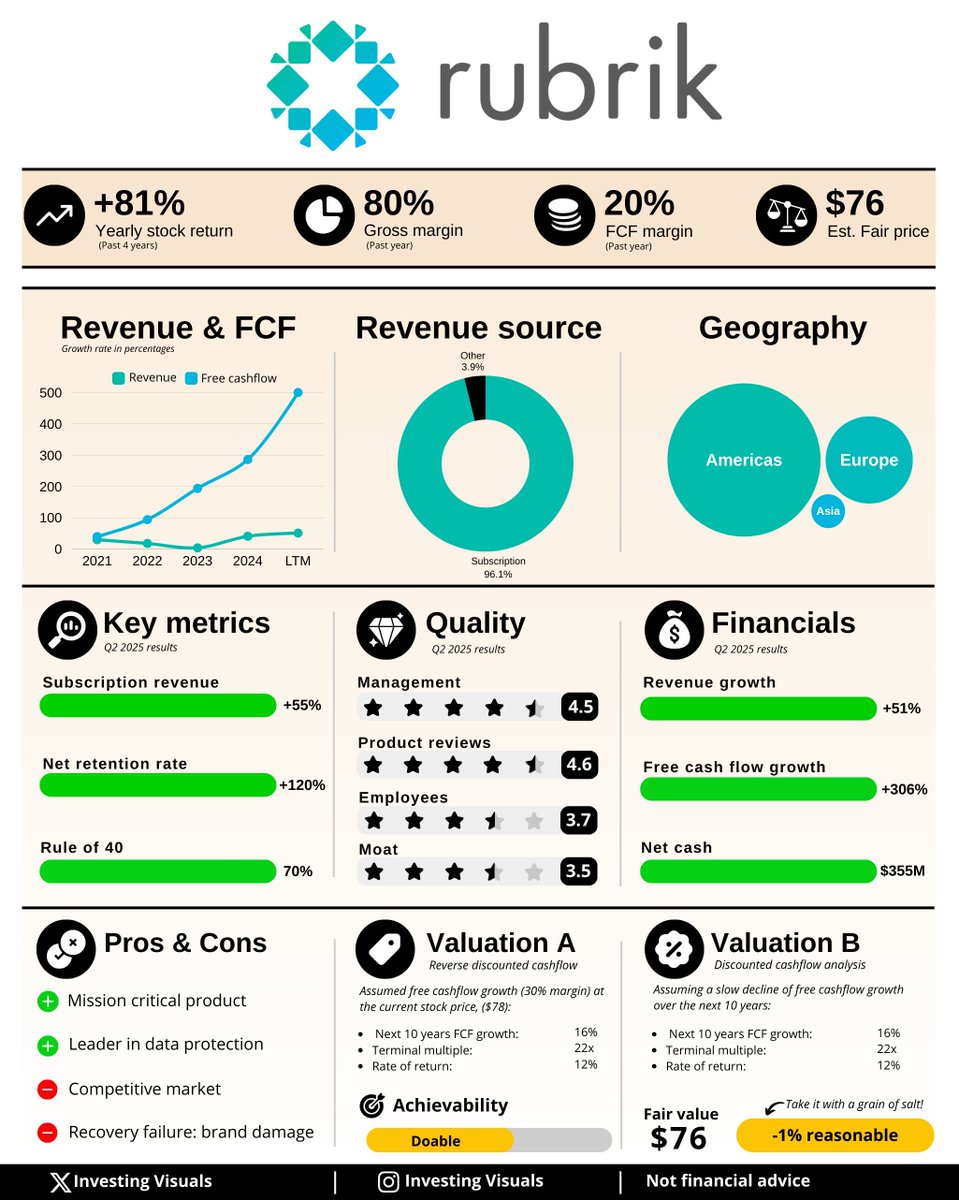
$RBRK is a high quality and founder led data security company, trading at a reasonable valuation.