KF-GEX+: Gamma, Vanna, Exposure, and IV A tale of cryptocurrencies'...

TheKingfisher@kingfisher_btc
35 views
May 18, 2025
~4 min read
Advertisement
1
KF-GEX+: Gamma, Vanna, Exposure, and IV
A tale of cryptocurrencies' expected volatility
A 🧵
It all started with a research paper published by @SqueezeMetrics exposing the effect of Options Order
A tale of cryptocurrencies' expected volatility
A 🧵
It all started with a research paper published by @SqueezeMetrics exposing the effect of Options Order
2
Flow in traditional financial markets, how to calculate it, and what kind of decision one could take from it. We will try to break down the options jargon to a direct Profit and loss practical point of view.
3
The option market
The majority of option volumes are generally underwritten by professional traders/desks, looking for a non-directional bet. They act as liquidity providers.
The majority of option volumes are generally underwritten by professional traders/desks, looking for a non-directional bet. They act as liquidity providers.
4
Those actors (unlike how retail often functions) tend to dynamically hedge their inventory, meaning they have a direct impact on the underlying price action.
They make money by selling options and collecting the associated premium.
They make money by selling options and collecting the associated premium.
5
Instead of a Robinhood “Yolo” call, dealers don’t take directional bets, hence the importance for an options dealer is to hedge his position and the associated different Greeks.
6
Most dealers will follow an in-house Black-Scholes-Merton model to evaluate the risk of the instrument and try to mimic implied volatility IV (premium) to match future realized volatility.
7
Greeks will reflect into the delta of the options as the probability of the options expiring in the money (ITM) or out of the money (OTM). As a reminder, dealers make money if the spread between their cost for dynamic hedging and the premium collected offsets each other.
8
Long story short options market is like the usual future market with a higher spread, market makers are more sophisticated investors and they are less informed takers.
9
Dealers want to play against non-toxic order flow or uninformed traders to have a long-term lucrative business. That’s mostly why only Bitcoin and Ethereum have options markets today.
10
Note that along with a plethora of insider trading increasing the toxicity of the order flow, altcoins markets don’t meet the market efficiency requirements to create liquid options markets.
11
Deep dive into dynamic hedging.
For example, let’s buy a vanilla call, the counterparty will end up selling a call and have a negative delta. If the market is on your side and the bet is winning, increasing the delta will force dealers to follow the market and be takers.
For example, let’s buy a vanilla call, the counterparty will end up selling a call and have a negative delta. If the market is on your side and the bet is winning, increasing the delta will force dealers to follow the market and be takers.
12
If you are losing your bet your delta will go down and dealers have less impact on the market for this particular instrument.
13
Path dependence of a regular option is possible if the different greek turns positive or negative at different levels, creating non-intuitive behavior like buying the top and selling the bottom.
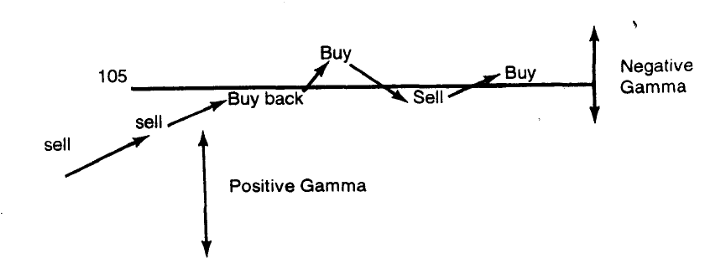
14
Also, the noise of the market itself impacts the path to delta neutrality of the dealers, by affecting the volume it will create a new path.
Hedging actually increases the risk and uses more capital. That’s why you also want a model to price the underlying and you simply
Hedging actually increases the risk and uses more capital. That’s why you also want a model to price the underlying and you simply
15
can’t hedge every minute. The transaction costs of unwinding the hedge should also be taken into account.
How do one hedge Gamma and Vanna exposure?
A great primer on Gamma Vanna hedging by @KeyPaganRush
youtube.com/watch?v=zfkOCc…
How do one hedge Gamma and Vanna exposure?
A great primer on Gamma Vanna hedging by @KeyPaganRush
youtube.com/watch?v=zfkOCc…
16
Gamma exposure
Gamma exposure is hedged by buying/selling the underlying instrument as to flatten the dealer’s expected return curve.
Market maker long Gamma → Need to sell as price increases and buy as price decreases → stabilize the price and soften price action
Gamma exposure is hedged by buying/selling the underlying instrument as to flatten the dealer’s expected return curve.
Market maker long Gamma → Need to sell as price increases and buy as price decreases → stabilize the price and soften price action
17
Market maker short Gamma → Need to buy as price increases and sell as price decreases → destabilize the price and exacerbate price movements
18
Do you start to see how powerful knowing the market’s overall Gamma exposure is? You can figure out where the market will slow down, range, or where it will be more “explosive”.
19
Vanna exposure
The options dealers' Vanna exposure represents the dealer’s options portfolio exposure in the context of the implied volatility.
This is best summarized by @cryptoSqueeze below: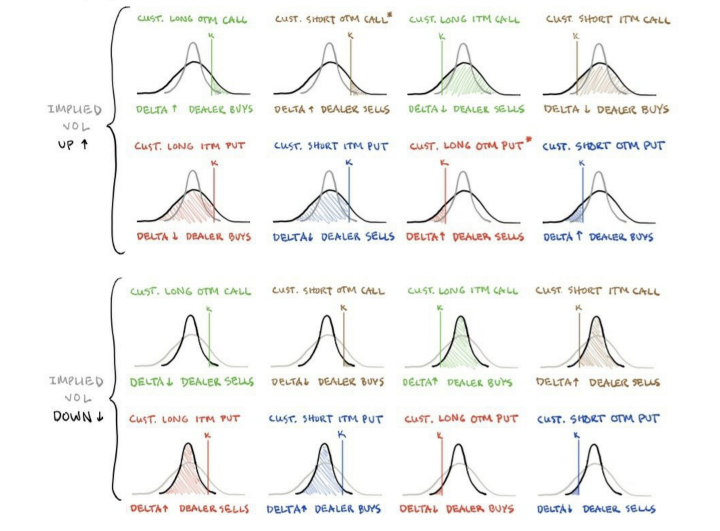
The options dealers' Vanna exposure represents the dealer’s options portfolio exposure in the context of the implied volatility.
This is best summarized by @cryptoSqueeze below:
20
So what’s with the Kingfisher’s GEX+ chart?
By analyzing the Bitcoin’s options order flow, the Kingfisher is able to reconstruct the dealers’ overall positions and deduct their Gamma and Vanna exposure.
By analyzing the Bitcoin’s options order flow, the Kingfisher is able to reconstruct the dealers’ overall positions and deduct their Gamma and Vanna exposure.
21
By graphing such deltas as below (x-axis: Implied volatility; y-axis: Index price), the Kingfisher shows you graphically the dealers’ deltas and their evolutions.
22
Delta > 0 (blue-green) → dealers tend to trade against price action to stay hedged
Delta < 0 (purple-red) → dealers tend to trade along with price action to stay hedged
Delta = 0 (transparent) → Deltas are hedged, a major shift in price action is likely coming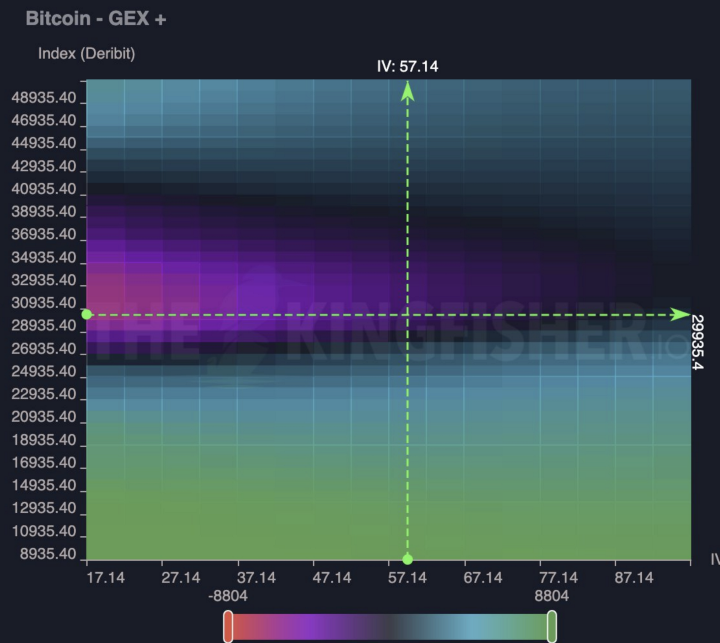

Delta < 0 (purple-red) → dealers tend to trade along with price action to stay hedged
Delta = 0 (transparent) → Deltas are hedged, a major shift in price action is likely coming
23
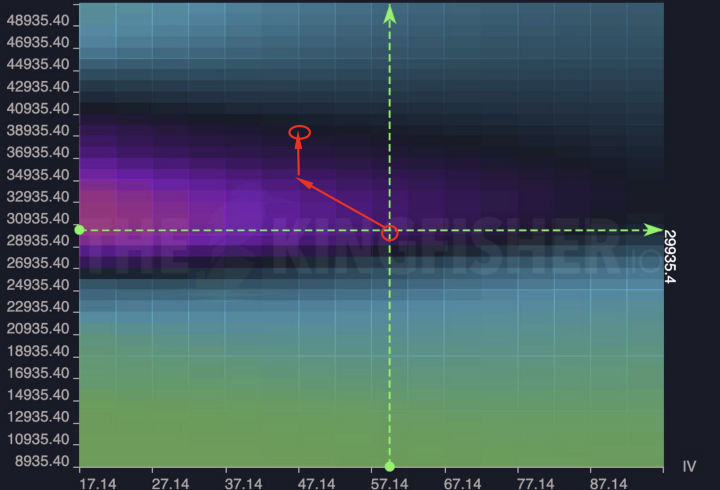
You will notice on the GEX+ graph that we were sitting in a weak slightly negative GEX+ area of the heatmap, indicating the options dealers were close to being fully hedged.
Later that day, the Volatility started decreasing while the price remained somewhat stable.
Later that day, the Volatility started decreasing while the price remained somewhat stable.
24
This resulted in an increase in negative delta for the dealers, which were pushed to trade along with the market, when this one started buying, and exacerbate the upward momentum until reaching another area of low/0 GEX+.
25
Of course, the GEX+ is better used regularly to observe the changes in Dealers’ Deltas in real-time as a few big transactions can dramatically change the GEX+ outlook.
The $BTC GEX+ is available in exclusivity on thekingfisher.io to subscribed users.
The $BTC GEX+ is available in exclusivity on thekingfisher.io to subscribed users.