1/ Fortune's Formula (William Poundstone) "Even unlikely events...

Darren r-σ²/2@ReformedTrader
65 views
Mar 15, 2025
~30 min read
Advertisement
1
1/ Fortune's Formula (William Poundstone)
"Even unlikely events must eventually come to pass. Therefore, anyone who accepts small risks of losing everything eventually _will_ lose everything. The compound return rate is acutely sensitive to fat tails."
amazon.com/Fortunes-Formu…
"Even unlikely events must eventually come to pass. Therefore, anyone who accepts small risks of losing everything eventually _will_ lose everything. The compound return rate is acutely sensitive to fat tails."
amazon.com/Fortunes-Formu…
2
2/ "Looked at another way, a coin toss is physics. An event is random only when no one cares to predict it.
"Thorp discovered that he was able to guess approximately where the roulette ball would land: The wheel was slightly tilted. This made the ball favor the downhill side."
"Thorp discovered that he was able to guess approximately where the roulette ball would land: The wheel was slightly tilted. This made the ball favor the downhill side."
3
3/ "Money management is the tricky & all-important issue of how to extract the greatest profit from a favorable opportunity. You can be the world’s greatest poker player, but if you can’t manage your money, you’ll end up broke. Sadly, almost everyone goes broke in the long run."
4
4/ "Early in this random-walk chart, wealth hits zero (line marked “Bankrupt”). Had this happened in a casino, the gambler would be tapped out. The right part of the chart is therefore irrelevant. He’s out permanently.
"It is possible to go broke even with a positive edge."
"It is possible to go broke even with a positive edge."
5
5/ "A greedy better might be tempted to bet his entire bankroll on the basis of the inside tips. But tips are not sure things. Sooner or later, a favored horse will lose. The gambler who always stakes his entire bankroll will lose everything the first time a tip is wrong."
6
6/ "Kelly concluded that a gambler should be interested in compound return, measuring success not in dollars but in percentage gain per race. The best strategy is one that offers the highest compound return consistent with no risk of going broke."
7
7/ Given zero transaction costs, "apportion your bets among horses according to your estimate of each one’s chance of winning.
"This way, you bet on every horse and will never be completely broke. If you believe War Admiral has a 24% chance to win, put 24% of your capital there.
"This way, you bet on every horse and will never be completely broke. If you believe War Admiral has a 24% chance to win, put 24% of your capital there.
8
8/ "In the long run, “bet your beliefs” will earn you the maximum possible compound return—provided that your assessment of the odds is more accurate than the public’s.
"The bets on the horses you think will lose are a valuable insurance policy.
"The bets on the horses you think will lose are a valuable insurance policy.
9
9/ " But “bet your beliefs” is of little use at a real track, as U.S. racetracks skim anywhere from 14-19% of the amount wagered.
"The Kelly formula says to bet edge/odds of your bankroll on each bet."
For a portfolio, Kelly sizing uses Sharpe ratios:
"The Kelly formula says to bet edge/odds of your bankroll on each bet."
For a portfolio, Kelly sizing uses Sharpe ratios:
Darren r-σ²/2@ReformedTrader
20/ "The optimal Kelly risk target is equal to your expected Sharpe ratio.
"Negative skew or high kurtosis reduces the optimal leverage. For FX carry (modest negative skew), optimal leverage is reduced by around 5%." (p. 66)
The author elaborates here:
qoppac.blogspot.com/2018/06/kelly-…
"Negative skew or high kurtosis reduces the optimal leverage. For FX carry (modest negative skew), optimal leverage is reduced by around 5%." (p. 66)
The author elaborates here:
qoppac.blogspot.com/2018/06/kelly-…
10
10/ "Elwyn Berlekamp, who worked for Kelly at Bell Labs, remembers Kelly saying that gambling and investment differ only by a minus sign. Favorable bets are called “investments.” Unfavorable bets constitute “gambling.” "
11
11/ "Shannon suggested that Thorp use Kelly’s formula to decide how much to bet on blackjack based on how favorable the deck was. Despite the theoretical protection against ruin, they realized that there are many variables in casino play."
12
12/ "In a moderately favorable situation, a card-counter might have a 51% chance of winning. The edge is 2%, so the Kelly formula says to bet 2% of the bankroll. (This estimate is not exact because of the features of splitting pairs and doubling down.)
13
13/ "They won $500 in 15 minutes at at a $500 maximum table. Then the dealer pressed the secret button.
"An army of unseen operatives inspected the play from behind miles of one-way mirrors. Dealers were expected to inform Smith when someone was winning too much too fast."
"An army of unseen operatives inspected the play from behind miles of one-way mirrors. Dealers were expected to inform Smith when someone was winning too much too fast."
14
14/ "Betting it all only works until you lose.
"The martingale, which requires doubling a wager at every bet lost, can lead to rapidly escalating losses.
"Although it takes a whole to get started, Kelly betting causes wealth to grow fastest by making optimal use of capital."
"The martingale, which requires doubling a wager at every bet lost, can lead to rapidly escalating losses.
"Although it takes a whole to get started, Kelly betting causes wealth to grow fastest by making optimal use of capital."
15
15/ "Betting twice Kelly ('overbet') is treacherous. Due to a lucky streak, overbettor was briefly the best-performing of the systems early on (the little volcano-shaped peak at lower left). Then the overbettor’s wealth fell back to nearly zero and stayed there for a long time.

16
16/ "Were the simulation continued indefinitely, the wealth of the twice-Kelly bettor would fall back to the original $1 or less an infinite number of times.
"The Kelly system manages money so that the bettor stays in the game long enough for the law of large numbers to work."
"The Kelly system manages money so that the bettor stays in the game long enough for the law of large numbers to work."
17
17/ "Card-counting may be the greatest shill ever invented. Not everyone who read Thorp’s book was able to apply the system consistently enough to gain an advantage. For every successful counter, there were hundreds who merely thought they could count cards successfully.
18
18/ "Card-counting got more attention than the more abstract Kelly formula.
"Those who skimmed Thorp’s book probably did not understand the importance of scaling bets to bankroll. It is a natural impulse to bet big when the deck is hot. For many, this must have been costly."
"Those who skimmed Thorp’s book probably did not understand the importance of scaling bets to bankroll. It is a natural impulse to bet big when the deck is hot. For many, this must have been costly."
19
19/ "Use of multiple decks makes counting less profitable. Because the end cards are never dealt, the concentrations of good cards that occasionally occur at the end of the deck never come into play.
"While playing at one Las Vegas strip casino, Thorp was offered a drink.
"While playing at one Las Vegas strip casino, Thorp was offered a drink.
20
20/ "He had problems concentrating and staggered up to his room. His eyes were dilated. It took about eight hours to wear off. The next day, Thorp returned and was offered another drink. He asked for water this time. “It tasted like they’d dumped a box of baking soda in it.
21
21/ “Just the few drops on my tongue were enough to wipe me out for the night.... I know of three beatings. One well-known blackjack card-counter had a lot of his face caved in. A guy I know had his arms held. Every time he tried to catch his breath, they’d punch him again.”
22
22/ "The latter player had been told to leave. He ignored the warning and continued playing. Thorp made it a policy to leave when asked on the hopeful theory that the thugs would always give one “fair” warning before getting violent.
23
23/ "Ed Reid and Ovid Demaris’s The Green Felt Jungle, an exposé of casino corruption, confirms that the casinos settled disputes with gangland violence well into the 1960s. Beatings often took place in the counting room, a soundproof room “ideal for such torture.”
24
24/ "Reid and Demaris tell of a cheating dealer at the Riviera. Two casino enforcers forced him to place his closed fists on a table. Another used a lead-encased baseball bat to smash the man’s fists. A mob doctor bandaged but did not set the hands.
25
25/ "The man was driven to the edge of town. The thugs took his shoes off and pushed him out of the car. “Now you SOB,” one thug said, “walk to Barstow. No goddamn hitchhiking, either. We’re gonna check on you all the way.” "
26
26/ "Bachelier spent his career in such obscurity that virtually nothing is known of his life. He died a decade before his rediscovery by Savage and Samuelson would make him one of the most influential figures in 20th-century economics."
More on this:
Darren r-σ²/2@ReformedTrader
3/ "The paper that first showed how to unlock the properties of molecules captured by Brownian motion helped make its author famous and clinched a victory for the atomists.
"However, it was not written by Louis Bachelier. It was written by Albert Einstein in 1905.
"However, it was not written by Louis Bachelier. It was written by Albert Einstein in 1905.
27
27/ "At the time Bachelier was writing, Albert Einstein puzzled over Brownian motion. The mathematical treatment of Einstein published in 1905 was similar to but less advanced than the one that Bachelier had already derived for stocks. Einstein had never heard of Bachelier."
28
28/ "The notion of a superior investor needs to be carefully qualified. The hallmark has to be a market-beating risk-adjusted return achieved not through luck but through some logical system."
AQR evaluates superstar investors using risk-adjusted returns:
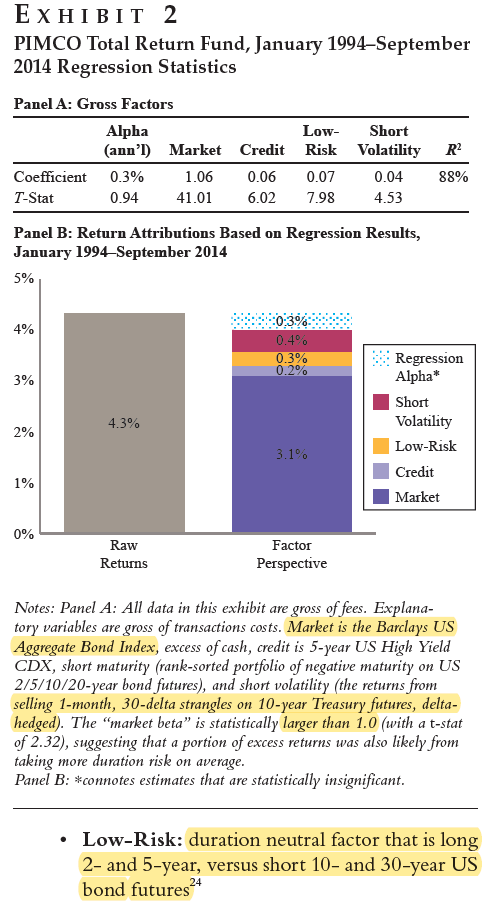
AQR evaluates superstar investors using risk-adjusted returns:
Darren r-σ²/2@ReformedTrader
1/ Superstar Investors (Brooks, Tsuji, Villalon)
"Identify structural edges and commit to seeing them through inevitable periods of underperformance. As each of our superstars shows, “merely good” edges over time compound to great long-term performance."
aqr.com/Insights/Resea…
"Identify structural edges and commit to seeing them through inevitable periods of underperformance. As each of our superstars shows, “merely good” edges over time compound to great long-term performance."
aqr.com/Insights/Resea…
29
29/ "Samuelson apparently felt that Buffett’s success was best filed with a small minority of “unexplained cases.” Samuelson, however, hedged his personal bets by putting some of his own money in Berkshire Hathaway."
More on Buffett's alpha:

More on Buffett's alpha:
Darren r-σ²/2@ReformedTrader
1/ Buffett's Alpha (Frazzini, Kabiller, Pedersen)
AQR finds that Berkshire Hathaway's large 13% CAPM alpha and 0.79 Sharpe ratio becomes insignificant after controlling for BAB and QMJ. Warren Buffet may have been the first multifactor investor.
papers.ssrn.com/sol3/papers.cf…
AQR finds that Berkshire Hathaway's large 13% CAPM alpha and 0.79 Sharpe ratio becomes insignificant after controlling for BAB and QMJ. Warren Buffet may have been the first multifactor investor.
papers.ssrn.com/sol3/papers.cf…
30
30/ "An MIT “Mafia” made it difficult to publish dissenting views in The Journal of Finance & other prestigious publications. In the 1980s, MIT information theorist Robert Fano wrote a paper arguing that stock price changes are not exactly a random walk & have predictable cycles.
31
31/ "The reaction to the paper’s mere premise was brutal. He was told that it would be pointless to seek publication. “Unless you have certain views, you’re wrong. The referee would call someone at MIT and they’d say, ‘Oh, yes, he’s a crackpot.’” "
More:
More:
Darren r-σ²/2@ReformedTrader
1/ Structure of Scientific Revolutions (Thomas Kuhn)
"A new theory is not chosen because it is true but because of a worldview change. Progress is not a simple line leading to the truth. It is progress away from less adequate conceptions of the world."
amazon.com/Structure-Scie…
"A new theory is not chosen because it is true but because of a worldview change. Progress is not a simple line leading to the truth. It is progress away from less adequate conceptions of the world."
amazon.com/Structure-Scie…
32
32/ "It is folly to bet everything on a favorite (horse or stock). The only way to survive is through diversification.
"There may also be unacknowledged risks. What we believe to be a “sure thing” is not. A small profit may come by accepting a small risk of a catastrophic loss."
"There may also be unacknowledged risks. What we believe to be a “sure thing” is not. A small profit may come by accepting a small risk of a catastrophic loss."
33
33/ "One of the puzzles of the market is that stock prices are more volatile than corporate earnings. This is often attributed to feedback effects.
"When people put money into the market, the buying pressure causes prices to rise. Envy motivates friends into buying stock too.
"When people put money into the market, the buying pressure causes prices to rise. Envy motivates friends into buying stock too.
34
34/ "Prices can’t go up forever if earnings haven’t increased apace. At some point, bad news triggers panic selling (negative feedback). The “bad news” does not have to be that bad: it's only a catalyst, the pinprick that bursts the bubble."
More on this:
Darren r-σ²/2@ReformedTrader
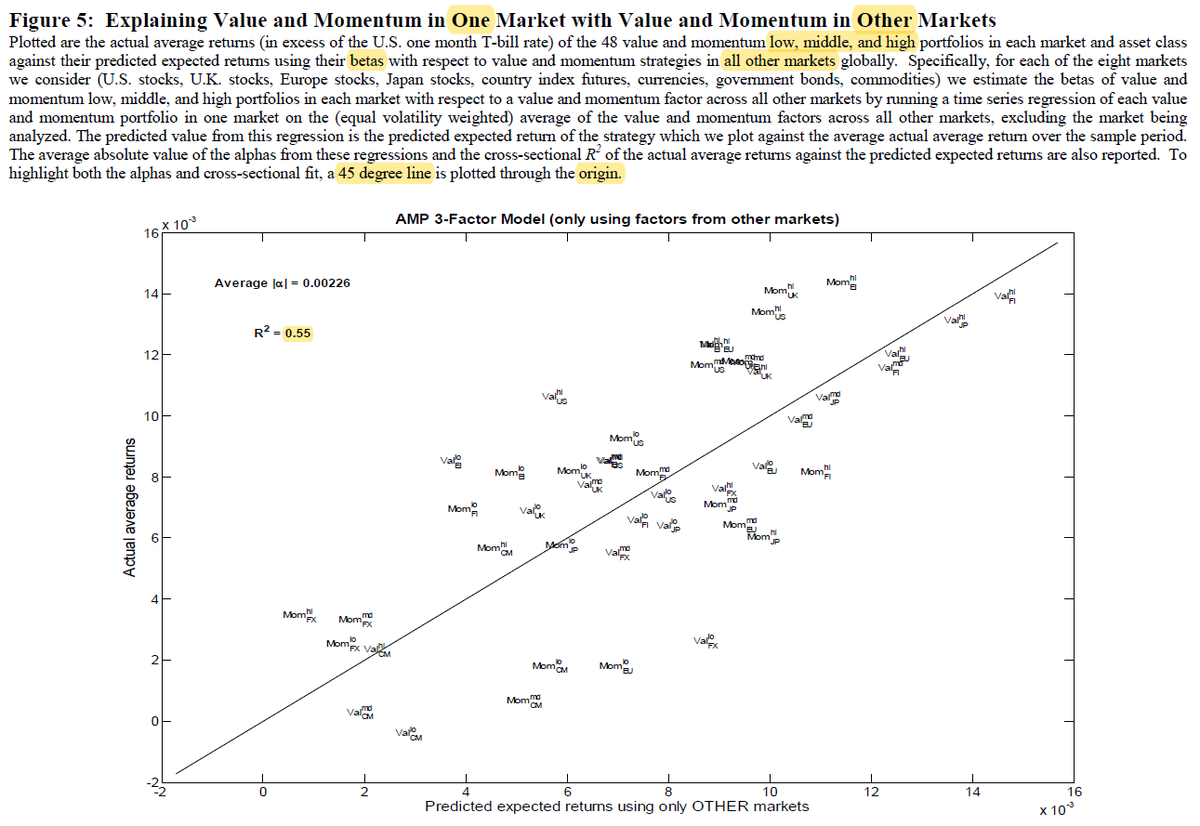
1/ Value and Momentum Everywhere (Asness, Moskowitz, Pedersen)
"Value and momentum are more pos. correlated across asset classes than the asset classes are themselves. However, value and momentum are neg. correlated both within and across asset classes."
papers.ssrn.com/sol3/papers.cf…
"Value and momentum are more pos. correlated across asset classes than the asset classes are themselves. However, value and momentum are neg. correlated both within and across asset classes."
papers.ssrn.com/sol3/papers.cf…
35
35/ "Blackjack had ceased to be as profitable or fun as it had once been for Thorp. “I realized that if I pushed it, some unpleasant physical things would eventually happen in Nevada.” By 1964, he decided to direct his talents toward the biggest casino of all: the stock market."
36
36/ "Most warrants were cost too much given the odds. This was especially true of warrants within a couple of years of expiring. Traders were too optimistic about the prospect of stock prices rising quickly.
"Should you find a warrant that costs too much, you can sell it short.
"Should you find a warrant that costs too much, you can sell it short.
37
37/ "Long-short trades are Kelly-optimal. They were in use in the stock market long before Kelly, though. Thorp’s innovation was to calculate exactly how much of the stock he had to buy to offset the risk of short-selling the warrant. This technique is now called delta hedging."
38
38/ "Thorp's hedging system worked as he’d hoped. By 1967, he had parlayed his original $40,000 into $100,000.
"There were relatively few warrants out there, so the market was illiquid. Someone who sells short too many warrants may find it difficult to buy them when needed.
"There were relatively few warrants out there, so the market was illiquid. Someone who sells short too many warrants may find it difficult to buy them when needed.
39
39/ "The “artificial” demand created by the deal itself can drive up the prices of these warrants. That is bad because Thorp was betting the warrants would get cheaper.
"Sometimes a company would change the terms of a warrant, and this could be disastrous for the trade.
"Sometimes a company would change the terms of a warrant, and this could be disastrous for the trade.
40
40/ "For these & other reasons, not every warrant deal turned a profit. Unlike other traders, Thorp understood the concept of gambler’s ruin. He was able to estimate the chances of profit & use the Kelly formula to make sure he was not committing too much money to any one deal."
41
41/ "Thorp's book seems to have been the first discussion in print of delta hedging. Yet as one of the hundreds of books of advice for the small investor that come out every year, the book received little notice from most academics."
42
42/ "The meaning of “hedge fund” drifted. Not all hedge funds hedge. Their distinction from mutual funds is now partly socioeconomic.
"Due to voluntary reporting, the public database for hedge funds (TASS) is rife with survivor bias."
More on this:
"Due to voluntary reporting, the public database for hedge funds (TASS) is rife with survivor bias."
Darren r-σ²/2@ReformedTrader
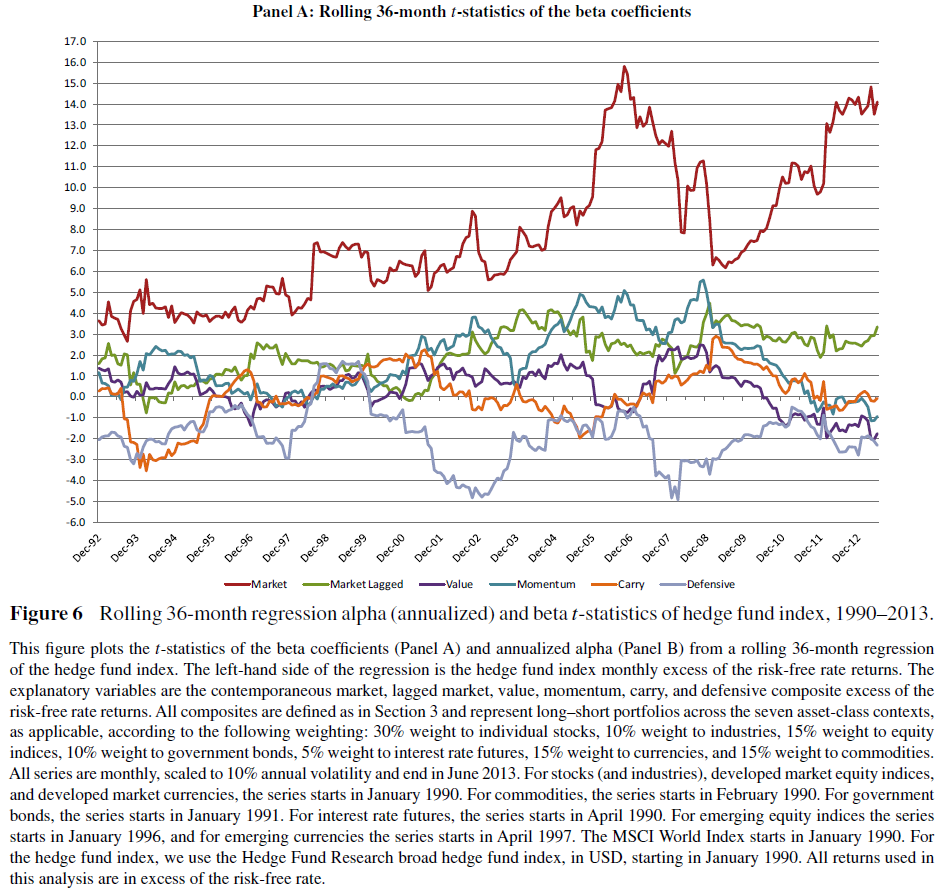
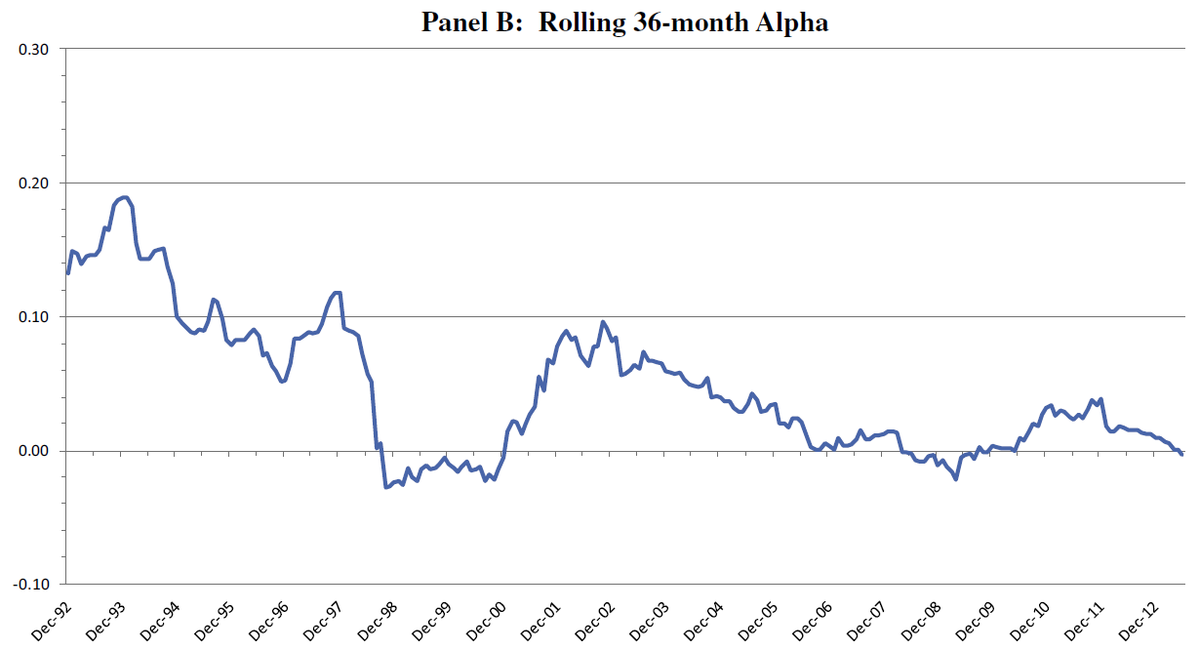
16/ Hedge funds have increased their market exposure over time while providing only moderate (and non-increasing) factor exposures, despite the growing literature on systematic strategies.
Hedge fund alphas have also declined with time and now sit at about zero.
Hedge fund alphas have also declined with time and now sit at about zero.
43
43/ "Thorp and wife met Buffett and wife for a night of bridge at the Buffetts’ home. Thorp was impressed with Buffett’s breadth of interests.
"Ed told Vivian he believed that Buffett would one day be the richest man in America. Buffett’s verdict on Thorp was also positive."
"Ed told Vivian he believed that Buffett would one day be the richest man in America. Buffett’s verdict on Thorp was also positive."
44
44/ "By 1967, Thorp had devised a version of what are now called the Black-Scholes pricing formulas for options and was thereby able to find mispriced convertible bonds and hedge the deals with the underlying stock."
45
45/ "The size of Thorp’s investment was limited by the market. The optimal position was “all you can get”—e.g., a mere $2,900 worth of warrants.
"In practice, Thorp could make a quick estimate to confirm that a position was well under the Kelly limit."
"In practice, Thorp could make a quick estimate to confirm that a position was well under the Kelly limit."
46
46/ "What Milken did with market inefficiencies was entirely different than Thorp did. He was such a superb salesman that, in time, junk bonds came to sell for elevated prices that largely nullified Hickman’s original reason for buying them.
47
47/ "Companies with doubtful credit issued junk bonds, buy other companies, and sell off their assets to pay the bond interest. When successful, corporate raiding was a form of arbitrage. The acquired companies were sometimes worth more than their irrationally low market values.
48
48/ "Milken surrounded himself with hardworking loyal people of mediocre talent. He wanted people who would owe everything to him.
"People in Milken’s circle had an almost creepy level of devotion: “Michael is the most important individual who has lived in this century.”
"People in Milken’s circle had an almost creepy level of devotion: “Michael is the most important individual who has lived in this century.”
49
49/ "Yet if his whole life was devoted to making money, he seemed not to care much about spending it. He lived in a relatively unpretentious Encino home, ate lunch off paper plates, wore a reasonably priced toupee, and drove an Oldsmobile.
50
50/ "Thorp and Regan began using Milken as their fund’s primary broker in the early 1970s. In all the time that Thorp’s fortunes were connected to Milken’s, the two men never met."
More on Milken:
More on Milken:
Darren r-σ²/2@ReformedTrader
79/ "Investors shunned fallen angels out of a fear of seeming imprudent. Like Alexander, Milken noticed investors were constrained by appearances and had left a window of opportunity open for a trader who was not. The herd instinct laid the foundation for a revolution in money."
51
51/ "In the early 1970s, Ross and Kimmel believed it might make sense to take Warner Communications private. They wanted to buy back most of the stock issued, limiting ownership to the few biggest shareholders. To get the necessary money, Warner would have to issue junk bonds.
52
52/ "Milken explained that Ross would have to give up 40% of Warner’s stock as an inducement to get people to buy the junk bonds. This was a standard equity kicker. Drexel would get another 35% cut as payment for services rendered, leaving 25% of the company for Ross’s group.
53
53/ "Ross had no intention of giving away 75% of the company and dropped the plan.
"Milken repeated this pitch to many clients. What they didn’t know was that the equity kicker was rarely offered to bond buyers. Instead, the stock quietly went into Milken’s private accounts."
"Milken repeated this pitch to many clients. What they didn’t know was that the equity kicker was rarely offered to bond buyers. Instead, the stock quietly went into Milken’s private accounts."
54
54/ "Thorp compared graphs produced by Black and Scholes’s formulas with those from his own. They were the same except for a factor incorporating the risk-free rate. Thorp had not included this because the OTC options he traded did not credit the trader with short-sale proceeds.
55
55/ " The rules were changed when options began trading on the CBOE. Black and Scholes accounted for this. Otherwise, the formulas were equivalent.
"The Black-Scholes formula, as it was christened, was published in 1973. That name deprived both Merton and Thorp of credit.
"The Black-Scholes formula, as it was christened, was published in 1973. That name deprived both Merton and Thorp of credit.
56
56/ "In Merton’s case, it was a matter of courtesy. Because he had built on Black and Scholes’s work, he delayed publishing his derivation until their article appeared.
"Thorp considers the Merton paper “a masterpiece.”
"Thorp considers the Merton paper “a masterpiece.”
57
57/ “I never thought about credit... I came from outside the economics and finance profession. The great importance that was attached to this problem wasn’t part of my thinking. What I saw was a way to make a lot of money.”
58
58/ "There are anomalies challenging every scientific theory ever propounded. It is a tough call knowing which to take seriously.
"EMH generally supposes that it is such a cinch to exploit arbitrage opportunities that prices never get significantly out of line for long.
"EMH generally supposes that it is such a cinch to exploit arbitrage opportunities that prices never get significantly out of line for long.
59
59/ "Thorp’s experience differed. Arbitrageurs were often constrained by trading costs, the supply of mispriced securities, the Kelly formula, and other factors. It took weeks, months, and more for mispricings to diminish, even with Thorp trying to profit at the maximum rate."
60
60/ "By Sharpe’s terminology, an active investor need not trade “actively.” A retired teacher with two shares of AT&T counts as an active investor operating on the assumption that AT&T is better to own than a total market index fund.
"Active investing is a zero-sum game."
"Active investing is a zero-sum game."
61
61/ "Thorp and Regan had turned a conviction that the market can be beaten into one of the most successful investment partnerships of all time, achieving greater-than-market returns over 13 consecutive years."
Thorp in Hedge Fund Market Wizards (thread):
Thorp in Hedge Fund Market Wizards (thread):
Darren r-σ²/2@ReformedTrader
92/ Ed Thorp:
Assuming winning and losing months are coin tosses, "the odds of getting at least one track record ≥ Thorp's would still be less than 1 out of 10^62. The odds of randomly selecting a specific atom in the earth would be about a trillion times better." (p. 162)
Assuming winning and losing months are coin tosses, "the odds of getting at least one track record ≥ Thorp's would still be less than 1 out of 10^62. The odds of randomly selecting a specific atom in the earth would be about a trillion times better." (p. 162)
62
62/ "Bet your entire net worth on the flip of a coin. You play against your neighbor, who has the same net worth. It’s double or nothing. Winner gets the loser’s house, car, savings, everything.
"Both of you would be nuts to agree. You have far more to lose than to gain.
"Both of you would be nuts to agree. You have far more to lose than to gain.
63
63/ "Compute the geometric mean by multiplying the two equally possible outcomes—$200,000 times $0—and taking the square root. Since zero times anything is zero, the geometric mean is zero. Accept that as the true value of the wager, and you’ll stick with your $100,000 net worth.
64
64/ "The geometric mean is almost always less than the arithmetic mean. (The exception is when all the averaged values are identical. Then the two kinds of mean are the same.) This means that the geometric mean is a more conservative way of valuing risky propositions."
65
65/ "A wager can make sense when the odds are slanted in one’s favor. It can also make sense when the parties differ in wealth.
"A poor merchant may improve his geometric mean by buying overpriced insurance; the wealthier insurance company is also improving its geometric mean.
"A poor merchant may improve his geometric mean by buying overpriced insurance; the wealthier insurance company is also improving its geometric mean.
66
66/ "Kelly’s prescription can be restated as this simple rule: When faced with a choice of wagers or investments, choose the one with the highest geometric mean of outcomes. This rule, of broader application than the edge/odds Kelly formula for bet size, is the Kelly criterion."
67
67/ "The geometric mean, also known as the compound return on investment, is approximately the arithmetic mean minus one-half the variance. This estimate may be made more precise by incorporating further statistical measures."
68
68/ "The worst wheel, by the Kelly philosophy, is the second. That’s because it has a zero as one of its outcomes. With each spin, you risk losing everything. Any long-term “investor” who lets money ride on the second wheel must eventually go bust: its geometric mean is zero.

69
69/ "The Kelly criterion would have you put your money on the first wheel (the highest geometric mean, not the highest arithmetic mean).
"A gambler who diversifies by betting on every horse achieves a higher geometric mean than someone who risks everything on a single horse."
"A gambler who diversifies by betting on every horse achieves a higher geometric mean than someone who risks everything on a single horse."
70
70/ "The arithmetic mean return is always higher than the geometric mean. Therefore, a volatile stock with zero geometric mean return must have a positive arithmetic mean return.
"Another good feature of the Kelly criterion is that it maximizes the _median_ wealth.
"Another good feature of the Kelly criterion is that it maximizes the _median_ wealth.
71
71/ "What the Kelley system cannot do is engineer luck. It is possible to be unlucky when using the Kelly system, to end up with less than the median. When you do, you may be worse off than you would have been with another system."
72
72/ "People’s feelings about wealth are fluid, inconsistent, and hard to identify with any neat mathematical function (including logarithmic ones). Preferences are often generated on demand. You do not know what you want until you go to a certain amount of trouble to find out.
73
73/ "This is hardly news to the organizers of opinion polls and focus groups. People have deep-seated opinions on some issues only. With other issues, you have to press them to decide—and a lot depends on how exactly you phrase the question."
For example,

For example,
Darren r-σ²/2@ReformedTrader
4/ "The correlation was .12 when the happiness question came first but rose to .66 when the order was reversed. Focusing attention on dating is apparently sufficient to induce the illusion that this aspect of life dominates one's well-being.
74
74/ "In stocks, it generally takes years to double your money—or lose practically everything. No buy-and-hold investor lives long enough for a high degree of confidence that the Kelly system will pull ahead of all others. Kelly has more relevance to _traders_ [larger N]."
75
75/ "Kelly betting is a way of making all gambles and investments interchangeable. Given any gambling or investment opportunity, the Kelly wager converts it into a capital-growth-optimal gamble/investment."
76
76/ "Betting half Kelly is appealing because it cuts volatility drastically while decreasing the return by only a quarter.
"The full (half) Kelly better stands a 1/3 (1/9) chance of halving her bankroll before she doubles it."
"The full (half) Kelly better stands a 1/3 (1/9) chance of halving her bankroll before she doubles it."
77
77/ "Bet sizes just to the left of the Kelly bet, and including the Kelly bet itself, are aggressive. Bet sizes to the right of Kelly are insane.
"There is always uncertainty about the true odds, and human nature may further bias estimation error in the direction desired.
"There is always uncertainty about the true odds, and human nature may further bias estimation error in the direction desired.
78
78/ "It is easy for the best computer models to overestimate edge by a factor of 2. This means someone attempting to place a Kelly bet might unintentionally at twice Kelly—which cuts the return rate to zero.
"Another method to tame the Kelly system is diversification.
"Another method to tame the Kelly system is diversification.
79
79/ "Pretend you are able to place simultaneous bets on hundreds of identically biased coins. Each coin has a 55% chance of coming up heads and pays even money. As we’ve seen, the Kelly wager for sequential bets on a single such coin is 10% of your bankroll.
80
80/ "With 100 coins tossed simultaneously, the Kelly wager is nearly 1/100 of the bankroll on each coin. (We don’t stake everything because it’s possible for all hundred coins to come up tails.) Diversification creates smooth exponential growth in which large moves are very rare.
81
81/ "Diversification works well for team blackjack players because there is no correlation between the luck at one table and the next.
"It worked for Princeton-Newport because the correlations between bets were low; Thorp designed his trades to be market- and volatility-neutral.
"It worked for Princeton-Newport because the correlations between bets were low; Thorp designed his trades to be market- and volatility-neutral.
82
82/ "In our global economy, virtually all stocks & stock markets are correlated to varying degrees. A crash in Tokyo depresses stocks in New York.
"Anyone who puts all her assets in stocks must accept large dips in wealth. This has weighed heavily on critics of Kelly investing.
"Anyone who puts all her assets in stocks must accept large dips in wealth. This has weighed heavily on critics of Kelly investing.
83
83/ "On October 19, 1987, the Dow lost 23% in a single day. Princeton-Newport’s $600 million portfolio shed only about $2 million in the crash. Thorp’s computer alerted him to rich opportunities in the panicked valuations. There were no buyers, making it impossible to sell.
84
84/ "Thorp made $2 million profit in new trades that day and the next. Princeton-Newport closed October about even for the month. Most mutual funds were down 20% or more.
"Black Monday was also a severe test of EMH and a clear counterexample to the random-walk model.
"Black Monday was also a severe test of EMH and a clear counterexample to the random-walk model.
85
85/ "It was difficult to see how a rational market could change 23% in a single day with no major bad news.
"Mark Rubinstein (coinventor of portfolio insurance, which played a role in the crash) estimated the chance of falling 29% (as S&P futures did) in one day as 1/10^160.
"Mark Rubinstein (coinventor of portfolio insurance, which played a role in the crash) estimated the chance of falling 29% (as S&P futures did) in one day as 1/10^160.
86
86/ Rubinstein: "Such an event that it would not be anticipated to occur even if the stock market were to last for 20 billion years. Indeed, such an event should not occur even if the stock market were to enjoy a rebirth for 20 billion years in each of 20 billion big bangs."
87
87/ "Over 19 years, Princeton-Newport Partners' compound return averaged 15.1% annually after fees with a SD of 4%. (Buffett’s & Soros’s returns were much more volatile.)
"A chart of Princeton-Newport’s return looks nothing like the the _sequential_ Kelly better’s jittery graph.
"A chart of Princeton-Newport’s return looks nothing like the the _sequential_ Kelly better’s jittery graph.
88
88/ "Through diversification, fractional Kelly position sizes, and a philosophy of erring on the side of caution, Thorp achieved a smooth exponential growth refuting the conventional trade-off of risk and return."
89
89/ "Thorp decided not to put money in LTCM. He was concerned that Merton and Scholes, though brilliant, had little experience. It didn’t help that Merton was second only to Samuelson as a critic of the Kelly criterion. Thorp also had heard that Meriwether was a “martingale man.”
90
90/ “The general chatter was that he was a high roller, and it wasn’t clear that the size of his bets were justified,” Thorp recalled. “The story was that if he got in the hole, if things went against him, he’d bet more. If things still went against him, he’d bet more.”
91
91/ "LTCM investors ranged from Merrill Lynch to the Kuwaiti state pension fund; the Bank of China to Hollywood agent Mike Ovitz.
"Some people were so desperate to own a piece of Wall Street’s hottest property that gray-market LTCM shares sold for 10% above asset value.
"Some people were so desperate to own a piece of Wall Street’s hottest property that gray-market LTCM shares sold for 10% above asset value.
92
92/ "After a lukewarm 1997, Meriwether decided to return the money of some of his investors in the hope of boosting future performance. Fortune magazine reported that “many went kicking and screaming, and at least one protested so angrily that LTCM allowed him to stay onboard.”
93
93/ "LTCM used leverage to multiply small profit opportunities to the point where they were big enough to matter. Paul Samuelson said he had doubts: the fund was placing a lot of faith in the random-walk model. The leverage left little room for any misfit of theory and reality.
94
94/ "With zero haircuts, LTCM was like a gambler whose pit boss extends him unlimited credit. You might think that with unlimited credit, it’s irrelevant how much money you have. The more you bet, the more you win. Any wager, no matter how high, seems justified.
95
95/ "This argument might hold water in the case of a casino with literally unlimited credit and bet size. You wouldn’t even need an edge in a casino like that. Martingale would work. In the real world, “unlimited credit” is only a figure of speech.
96
96/ "A stellar career can end in a few hours. Blown-up traders have failed at the most important judgment: how much money to commit to a trade.
"Should something terrible happen, the money manager pulls out the VaR report and point to cell D18, the 5% risk of a 37% loss.
"Should something terrible happen, the money manager pulls out the VaR report and point to cell D18, the 5% risk of a 37% loss.
97
97/ "Calculating VaR is a practical idea in a litigious society where well-off people don’t know much math.
"VaR reports give the impression that the numbers are reliable because smart people have worked them out, but numbers are only as good as the assumptions underlying them.
"VaR reports give the impression that the numbers are reliable because smart people have worked them out, but numbers are only as good as the assumptions underlying them.
98
98/ "VaR sidesteps the two central questions in John Kelly’s analysis: What level of risk will lead to the highest long-run return? What is the chance of losing everything? (A VaR report could address the second. In practice, it rarely does. Who wants to freak the client out?)
99
99/ "In July 1998, the IMF made a $17 billion loan package to Russian banks. $4.5 billion of it was wired to mobsters’ offshore bank accounts. The thug-controlled banks had no intention of repaying many of the Western loans. The Russian treasury was scarcely more credit-worthy.
100
100/ "Russia’s treasury bonds, called GKOs, were the junkiest of junk bonds, paying 40%+ interest. Half of Russia’s tax collections went to pay interest on treasury debt.
"Prime Minister Sergei Kiriyenko announced that Russia was devaluing the ruble and defaulting on the GKOs.
"Prime Minister Sergei Kiriyenko announced that Russia was devaluing the ruble and defaulting on the GKOs.
101
101/ "LTCM instantly lost millions. It was lucky; others did worse.
"Everyone shifted funds from riskier investments to safer, more liquid ones.
"LTCM’s philosophy was that people pay too much for safe, liquid investments. The Russian default temporarily changed that.
"Everyone shifted funds from riskier investments to safer, more liquid ones.
"LTCM’s philosophy was that people pay too much for safe, liquid investments. The Russian default temporarily changed that.
102
102/ "LTCM shed $551 million. It desperately needed collateral to cover its simultaneous losing trades.
“When you’re down by half, people figure you can go down all the way. They’re going to push the market against you. They’re not going to roll your trades. You’re finished.”
“When you’re down by half, people figure you can go down all the way. They’re going to push the market against you. They’re not going to roll your trades. You’re finished.”
103
103/ Mark Twain: “A banker lends you his umbrella when the sun is shining but wants it back the moment it rains.”
“They should have pulled down their leverage multiple. Instead, they allowed it to drift up to 60x. No Las Vegas gambler would make that mistake - no surviving one.”
“They should have pulled down their leverage multiple. Instead, they allowed it to drift up to 60x. No Las Vegas gambler would make that mistake - no surviving one.”
104
104/ "LTCM was simultaneously making nearly the same bets all over the world. This was supposed to be diversification, but it wasn’t. The Russian default affected credit all over the world.
"The banks would soon rush to seize such collateral & sell it, causing prices to plunge.
"The banks would soon rush to seize such collateral & sell it, causing prices to plunge.
105
105/ “I’m not worried about markets trading down. I’m worried they won’t trade at all.”
"Many of the partners had rolled substantial fortunes into LTCM. Hilibrand had taken out a personal loan of $24 million to buy his own fund, which was itself at nosebleed leverage levels.
"Many of the partners had rolled substantial fortunes into LTCM. Hilibrand had taken out a personal loan of $24 million to buy his own fund, which was itself at nosebleed leverage levels.
106
106/ "Hilibrand’s net worth went from $100 million to $20 million in debt. He requested that the bailout cover his personal debts. The consortium said no. Buffett marveled at how “ten or 15 guys with an IQ of 170” could get themselves “into a position to lose all their money.”
107
107/ "LTCM had based some models only four years of data. In that short period, the spread between junk bonds and treasuries hovered in the range of 3-4 percentage points. The fund essentially bet that it would not exceed this range. But as recently as 1990, it had topped 9%.
108
108/ Thorp: “People think that things are necessarily bounded in a historical range.” In 1998, when the spread widened suddenly to 6%, “they said this was a one-in-a-million-year event. A year or two later, it got wider, and two years after that, it got wider yet.”
109
109/ "Overbetting (unlike leverage or fat tails) is always bad. Thorp linked the LTCM collapse to Merton and Scholes’s intellectual critique of the Kelly system.
"Too little of the fund’s brainpower went to asking what could have gone wrong.
"Too little of the fund’s brainpower went to asking what could have gone wrong.
110
110/ "When financial models can be so incredibly wrong, the extreme downside caution of Kelly betting is not out of place. For mathematical, psychological, and sociological reasons, it is a good idea to use a money management system that is forgiving of estimation errors.
111
111/ "The University of British Columbia’s William Ziemba has estimated that LTCM’s leverage was somewhere around twice the Kelly level. If correct, that would imply that the fund’s true compound growth rate was hovering near zero."
More on LTCM:

More on LTCM:
Darren r-σ²/2@ReformedTrader
1/ Inventing Money: The Story of Long-Term Capital Management (Nicholas Dunbar)
Thread
"Market crises are created by human behavior. LTCM was not a ship tossed on the waves. It was more like an attempt to control the weather that went wrong." (p. xiii)
amazon.com/Inventing-Mone…
Thread
"Market crises are created by human behavior. LTCM was not a ship tossed on the waves. It was more like an attempt to control the weather that went wrong." (p. xiii)
amazon.com/Inventing-Mone…
112
112/ "The manager shares the upside but does not directly share the investors’ losses.
"Investors choose one fund over another on the strength of a few basis points of return. This creates the severest temptation for managers to boost return any way possible.
"Investors choose one fund over another on the strength of a few basis points of return. This creates the severest temptation for managers to boost return any way possible.
113
113/ "One way is to take “Russian roulette” risks likely to pay off in the short run but carry the possibility of disaster. Human nature and single-period financial models make it easy to blind oneself to long-term risk. It can take years for overbetting to blow up.

114
114/ "There is no better way of demonstrating the need for money management than seeing your own money vanish while making positive-expectation bets. It is impossible to make the same point so viscerally with mere stochastic differential equations."
115
115/ "Thorp continued to tinker with statistical arbitrage. He replaced the division by industry groups with a more flexible factor analysis system that analyzed stocks by correlations with factors such as market indexes, inflation, and gold. This better managed risks.
116
116/ "Because of their unpredictability, mergers, spin-offs, and reorganizations were bad for the scheme. At the announcement of such news, Mizusawa put the affected companies on a “restricted list” of stocks to avoid in new trades.
117
117/ "The inexplicable aspect of Thorp’s achievement was his continuing ability to discover new market inefficiencies as old ones played out.
"In May 1998, Thorp reported that his investments had grown at an average 20% annual return (with 6% SD) over 28.5 years."
"In May 1998, Thorp reported that his investments had grown at an average 20% annual return (with 6% SD) over 28.5 years."
118
118/ "Ziemba estimates that a first-rate Hong Kong computer team can make $100 million in a good season. Races are an instructive model of securities markets. The same fallible humans set prices for tech stocks & show bets. The profit motive does not guarantee market efficiency.
119
119/ "Hakansson estimates that no more than 10% of MBA programs mention the Kelly criterion.
Jarrod Wilcox: “You’ve heard of Kuhn’s paradigm shift? This is what’s going on. Until you get leading lights at MIT or Stanford to endorse it, you’re not going to have a paradigm shift.
Jarrod Wilcox: “You’ve heard of Kuhn’s paradigm shift? This is what’s going on. Until you get leading lights at MIT or Stanford to endorse it, you’re not going to have a paradigm shift.
120
120/ “At one point, I was so daring as to submit a paper to The Journal of Finance. The review said, ‘This contradicts everything we’ve learned in finance.’
“It really doesn’t. But it contradicts so many things that the claws come out.”
More on Kuhn:
“It really doesn’t. But it contradicts so many things that the claws come out.”
More on Kuhn:
Darren r-σ²/2@ReformedTrader
1/ Structure of Scientific Revolutions (Thomas Kuhn)
"A new theory is not chosen because it is true but because of a worldview change. Progress is not a simple line leading to the truth. It is progress away from less adequate conceptions of the world."
amazon.com/Structure-Scie…
"A new theory is not chosen because it is true but because of a worldview change. Progress is not a simple line leading to the truth. It is progress away from less adequate conceptions of the world."
amazon.com/Structure-Scie…
121
121/ "There's a BIG difference between *arithmetic* (serial) and *geometric* (compounded) expectations.
"The *arithmetic* expectation of a '50/50 doubling or halving' bet is +25%.
"The *geometric* expectation of the SAME bet is ZERO."

"The *arithmetic* expectation of a '50/50 doubling or halving' bet is +25%.
"The *geometric* expectation of the SAME bet is ZERO."
10-K Diver@10kdiver
1/
Get a cup of coffee.
In this thread, I'll walk you through Shannon's Demon.
This is an investing "thought exercise" -- posed by the great scientist Claude Shannon.
Solving this exercise can teach us a lot about favorable vs unfavorable long-term bets, position sizing, etc.
Get a cup of coffee.
In this thread, I'll walk you through Shannon's Demon.
This is an investing "thought exercise" -- posed by the great scientist Claude Shannon.
Solving this exercise can teach us a lot about favorable vs unfavorable long-term bets, position sizing, etc.
122
122/ Related reading:
Red-Blooded Risk: The Secret History of Wall Street
x.com/ReformedTrader…
Hedge Fund Market Wizards
x.com/ReformedTrader…
More Money Than God: Hedge Funds and the Making of a New Elite
x.com/ReformedTrader…
Leveraged Trading
Red-Blooded Risk: The Secret History of Wall Street
x.com/ReformedTrader…
Hedge Fund Market Wizards
x.com/ReformedTrader…
More Money Than God: Hedge Funds and the Making of a New Elite
x.com/ReformedTrader…
Leveraged Trading
Darren r-σ²/2@ReformedTrader
1/ Leveraged Trading (Robert Carver)
Thread with quotes from the book
"Because leverage is so dangerous [due to blow-up risk and higher trading costs], deciding how much to use is the single most important decision any trader has to make." (p. xv)
amazon.com/Leveraged-Trad…
Thread with quotes from the book
"Because leverage is so dangerous [due to blow-up risk and higher trading costs], deciding how much to use is the single most important decision any trader has to make." (p. xv)
amazon.com/Leveraged-Trad…
123
123/


124
124/

125
125/
Darren r-σ²/2@ReformedTrader
1/ How do you maximize compound returns?
A. Don't use too much risk.
B. Don't rely on bounce-backs.
C. Appropriate risk depends on expected Sharpe ratios.
D. Diversification increases Sharpes.
E. Hedge the (relevant) tails.
"Rule #1: Never lose money."
x.com/ReformedTrader…
A. Don't use too much risk.
B. Don't rely on bounce-backs.
C. Appropriate risk depends on expected Sharpe ratios.
D. Diversification increases Sharpes.
E. Hedge the (relevant) tails.
"Rule #1: Never lose money."
x.com/ReformedTrader…
126
126/ Jamie Mai:
Darren r-σ²/2@ReformedTrader
158/ "You have the option to keep 20% of your P&L this year, but you also want to own the serial option of being able to do that every year. You can't blow up.
"The two biggest mistakes traders make is that they don't do enough homework and are too casual about risk." (p. 282)
"The two biggest mistakes traders make is that they don't do enough homework and are too casual about risk." (p. 282)
127
127/

Taylor Pearson@TaylorPearsonMe
Fortune's Formula should be a top 5 investing book.
Fantastically written and explains diversification and position sizing (the most important, yet poorly understood concepts by amount most investors IMO)
Fantastically written and explains diversification and position sizing (the most important, yet poorly understood concepts by amount most investors IMO)
128
128/


129
129/

Wayne Himelsein@WayneHimelsein
NASA has a perfect phrase for when they miss something that causes the plan to go very wrong:
Critical Oversight
Amongst 100mm parts of the Space Shuttle, a tiny expanding washer led to its explosion.
In Portfolio or Strategy building, exhaust the search for Critical Oversights
Critical Oversight
Amongst 100mm parts of the Space Shuttle, a tiny expanding washer led to its explosion.
In Portfolio or Strategy building, exhaust the search for Critical Oversights
130
130/

Jim Carroll@vixologist
@WayneHimelsein “If you don’t lose money, most of the remaining alternatives are good ones!” Joel Greenblatt
“While others attempt to win every lap around the track, it is crucial to remember that to succeed at investing, you have to be around at the finish.” Seth Klarman
“While others attempt to win every lap around the track, it is crucial to remember that to succeed at investing, you have to be around at the finish.” Seth Klarman
131
131/ "Be skeptical. Don't trust anybody.
"Be pessimistic. Don't trust backtests, even if you haven't overfitted them, and even if they've been done on a rolling out-of-sample basis. The future is unlikely to be quite as good as the past."
"Be pessimistic. Don't trust backtests, even if you haven't overfitted them, and even if they've been done on a rolling out-of-sample basis. The future is unlikely to be quite as good as the past."
Darren r-σ²/2@ReformedTrader
104/ "A good systematic trader is humble, underestimating intelligence, skill, and luck. Assume your trading will go badly; be prepared for that, and be pleasantly surprised if it doesn't. Don't try anything too clever: it is probably unnecessary and is more likely to go wrong.
132
132/ "Partially a reason why I love trading tails…. You realize how much unsophisticated agents underprice these type of events actually occurring."

Kris Sidial🇺🇸@Ksidiii
Biggest mistake a trader can make is martingaling something that has moved “2 sigma to 4 sigma”.
Markets are dynamic and don’t work this way. You will eventually blow up.
I took ugly losses during my rookie years trading the Z score (stat arb pairs) it really opened my eyes.
Markets are dynamic and don’t work this way. You will eventually blow up.
I took ugly losses during my rookie years trading the Z score (stat arb pairs) it really opened my eyes.
133
133/
Darren r-σ²/2@ReformedTrader
120/ "When a firm has to sell in a market without buyers, prices run to the extremes beyond the bell curve.
"Long-term thinking is a luxury not always available to the highly leveraged; they may not survive that long."
More on this:
x.com/ReformedTrader…
"Long-term thinking is a luxury not always available to the highly leveraged; they may not survive that long."
x.com/ReformedTrader…
134
134/

Darren r-σ²/2@ReformedTrader
1/ When Genius Failed: The Rise and Fall of Long-Term Capital Management (Roger Lowenstein)
"If there was one article of faith that John Meriwether had discovered at Salomon Brothers, it was to ride your losses until they turned into gains."
amazon.com/When-Genius-Fa…
"If there was one article of faith that John Meriwether had discovered at Salomon Brothers, it was to ride your losses until they turned into gains."
amazon.com/When-Genius-Fa…
135
135/ "I suspect The Big Short did a lot of damage to traders of that generation. (Do a bunch of research; put on massive, concentrated contrarian position; get super-rich) Unfortunately, that's an absolutely terrible way to go about making money."

Robot James 🤖🏖@therobotjames
Putting on a massively negative carry, illiquid OTC position, marked by your counterparty is honestly the worst trading approach I can think of.
You don't have the luxury of that kind of thing if you're serious about making money.
You don't have the luxury of that kind of thing if you're serious about making money.
136
136/
Darren r-σ²/2@ReformedTrader
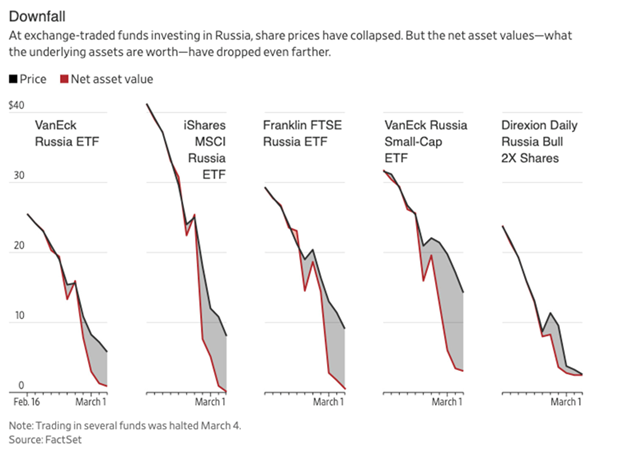
193/ "Moscow’s stock market has been shut down. Russian shares first plummeted on other exchanges, then were frozen. It’s a reminder that government policy can’t always keep markets afloat; sometimes it devastates them, and markets can die altogether."
blog.validea.com/sometimes-stoc…
blog.validea.com/sometimes-stoc…
137
137/ Be prepared for the unexpected:
Darren r-σ²/2@ReformedTrader
"LME has been forced to suspend trading in its nickel contract.
"All Tuesday's trades up until 0815 GMT will be cancelled.
"Tsingshan Holding Group is struggling to meet margin calls. None of its metal is in the right form for LME delivery."
nasdaq.com/articles/colum…
"All Tuesday's trades up until 0815 GMT will be cancelled.
"Tsingshan Holding Group is struggling to meet margin calls. None of its metal is in the right form for LME delivery."
nasdaq.com/articles/colum…
138
138/
Robot James 🤖🏖@therobotjames
This is crucial in trading too.
"I know I'm wrong,
How can I be in roughly the right place so I'm likely to make money?
How can I minimize the cost of the worst case scenario?"
"I know I'm wrong,
How can I be in roughly the right place so I'm likely to make money?
How can I minimize the cost of the worst case scenario?"
139
139/

Thomas Kopelman 💵@TKopelman
Most don't realize the risk you are taking by holding onto employer stock
They pay you your income
And they are a large investment of yours for the future
What if they fail?
Most of your eggs are in that one basket
They pay you your income
And they are a large investment of yours for the future
What if they fail?
Most of your eggs are in that one basket
140
140/ The song of a martingale
x.com/davidbelle_/st…
x.com/davidbelle_/st…
141
141/

Dr. Parik Patel, BA, CFA, ACCA Esq.@ParikPatelCFA
The number #1 piece of advice for a bear market is:
Survive.
Survive.
142
142/
143
143/

Clifford Asness@CliffordAsness
“You only need one” isn’t quite right. Yes, u may only need one Amazon, if u let it ride the whole way up becoming an “only Amazon” portfolio. If you rebalance the Amazon helps but doesn’t necessarily rescue u. U have to pick Amazon and then let it ride the whole way. Good luck.
144
144/

Corey Hoffstein 🏴☠️@choffstein
The thing they don’t teach you about portfolio management is that humans are involved.
Which means that, rarely, Very Big Broker will ignore your wire instructions and send the money to Wrong Bank, and you’re shit out of luck until they can reverse it.
Which means that, rarely, Very Big Broker will ignore your wire instructions and send the money to Wrong Bank, and you’re shit out of luck until they can reverse it.
145
145/


Mike Lawler@mikeandallie
1/10 (or so) A short thread sharing some playing around I did after reading Mark Spitznagel's Safe Haven last weekend. The idea I was playing around with is that buying - and even paying above loss cost - for crash protection can actually increase your expected return.
146
146/ "Pensions, endowments, retail investors, target-date funds, and target-vol funds have similar and highly correlated portfolios. The last decade has been great for equities, but when a melt-down occurs, we may see fast losses due to deleveraging."
Darren r-σ²/2@ReformedTrader
"We believe the same factors we mentioned that drove the market up will play a role in driving it down.
"But if you have excess cash when your competitors are under stress, you have the ability to buy them out or take business they no longer have the ability to serve." @Ksidiii
"But if you have excess cash when your competitors are under stress, you have the ability to buy them out or take business they no longer have the ability to serve." @Ksidiii
147
147/

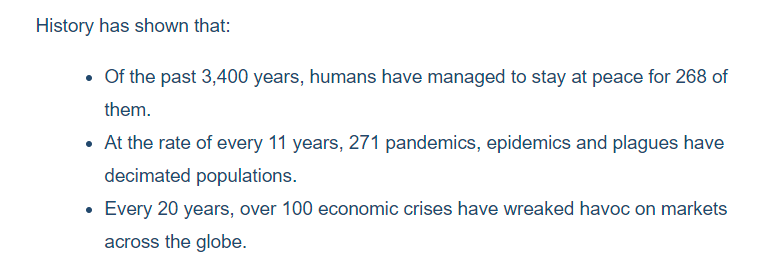
Wes Gray 🇺🇸@alphaarchitect
The current situation is normal; all funkied up.
~90% of the time we are at war.
~every decade there is a pandemic.
~economic crisis hits every 20 years.
From @GlobalFinData
~90% of the time we are at war.
~every decade there is a pandemic.
~economic crisis hits every 20 years.
From @GlobalFinData
148
148/

Frederik Gieschen@FrederikNeckar
He also reiterated his key learning from George Soros.
"I thought I was gonna learn what made the yen and the Mark go up and down. What I learned was sizing is probably 70-80% of the equation. It's how much you make when you're right and how much you lose when you're wrong.”
"I thought I was gonna learn what made the yen and the Mark go up and down. What I learned was sizing is probably 70-80% of the equation. It's how much you make when you're right and how much you lose when you're wrong.”
149
149/
Darren r-σ²/2@ReformedTrader
@chipflare @MetacriticCap Poundstone does a good job of explaining the material but only hints at some of the potential implications and applications. I've tried to hit on some of those things in this thread:
x.com/ReformedTrader…
x.com/ReformedTrader…
150
150/
Darren r-σ²/2@ReformedTrader
Corollary:
One of the worst things an investor can do is to become confident about a strategy because of its performance over the past couple of years and then go all-in on that strategy.
This is a way to lose the farm if the past couple of years were an exception to the rule.
One of the worst things an investor can do is to become confident about a strategy because of its performance over the past couple of years and then go all-in on that strategy.
This is a way to lose the farm if the past couple of years were an exception to the rule.
151
151/
Darren r-σ²/2@ReformedTrader
15/ "With wider strikes, you can get a good period with great Sharpe even with negative edge. It is more likely that testing the same idea on straddles or other structures give more representative distributions over arbitrarily short time periods."
Thread
x.com/HangukQuant/st…
Thread
x.com/HangukQuant/st…
152
152/
Darren r-σ²/2@ReformedTrader
Portfolios with large changes in returns (e.g., +100% one year and -50% the next) are probably using too much leverage.
Volatility is more predictable than returns (x.com/ReformedTrader…), so a 100% return is not something to be proud of unless it's from a high Sharpe ratio.
Volatility is more predictable than returns (x.com/ReformedTrader…), so a 100% return is not something to be proud of unless it's from a high Sharpe ratio.
153
153/ "Bitcoin had a negative return of 20% but a positive Sharpe Ratio of 0.2.
"You have to both correctly judge the quality of the investment and size your investment accordingly.
"Getting either materially wrong generally results in losses."
elmwealth.com/bitcoin-alloca…
"You have to both correctly judge the quality of the investment and size your investment accordingly.
"Getting either materially wrong generally results in losses."
elmwealth.com/bitcoin-alloca…
154
154/
Corey Hoffstein 🏴☠️@choffstein
@darjohn25 @SinclairEuan "Taking less risk than is optimal is not safer; it just locks in a worse outcome.
Taking more risk than is optimal also results in a worse outcome, and often leads to complete disaster."
— Aaron Brown, Red Blooded Risk (2011)
Taking more risk than is optimal also results in a worse outcome, and often leads to complete disaster."
— Aaron Brown, Red Blooded Risk (2011)
155
156
156/ Thread:
x.com/vihan13singh/s…
x.com/vihan13singh/s…
157
157/

Darren r-σ²/2@ReformedTrader
21/ "Consistently compounding positive returns leads to strong long-term performance, whereas significant, even if infrequent, drawdowns destroy performance.
"Big losses are very hard to recover from. A loss of 50% requires a gain of 100% just to break even." (p. 28).
"Big losses are very hard to recover from. A loss of 50% requires a gain of 100% just to break even." (p. 28).
158
158/
Frederik Gieschen@FrederikNeckar
Julian Robertson: "If you really look at how to do a good record over the years, it's not to make the huge amounts of money. It's to avoid big losses. That's the way to really make money over the years."
159
159/ "We went into a terrible recession. The bonds never traded there again. It was the luck of the draw.
"If I had started in a different moment, I would have had a bad year and probably would have gone out of business."
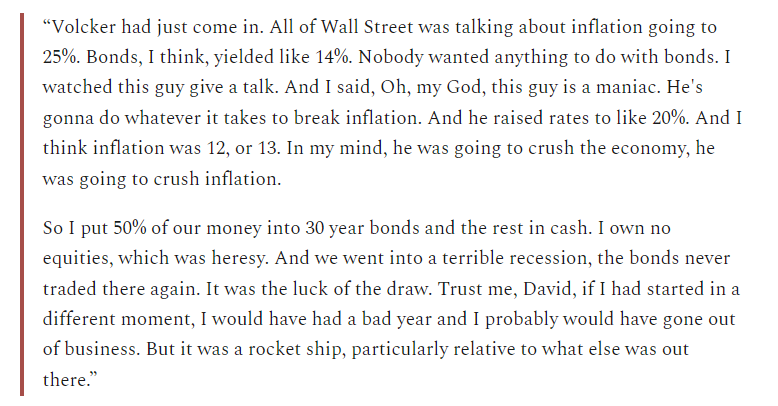
"If I had started in a different moment, I would have had a bad year and probably would have gone out of business."
Frederik Gieschen@FrederikNeckar
Druckenmiller on luck and Volcker:
"Wall Street was talking about inflation going to 25%. I watched this guy give a talk. My God, this guy is a maniac. He was going to crush the economy and inflation. I put our money into bonds and cash. No equities, which was heresy."
"Wall Street was talking about inflation going to 25%. I watched this guy give a talk. My God, this guy is a maniac. He was going to crush the economy and inflation. I put our money into bonds and cash. No equities, which was heresy."
160
160/


Liz Thomas@LizThomasStrat
Long-term UK Gilt bonds have posted a total return of -52.3% since Dec 2021. An entire decade of gains wiped out.
161
161/
Darren r-σ²/2@ReformedTrader
Thinking about what could go wrong is an underappreciated priority.
Design systems for high Sortino ratios, and you are more likely to get them.
But a high Sortino doesn't help in an extreme crisis, though it may eventually earn enough to buy an extreme-crisis hedge.
Design systems for high Sortino ratios, and you are more likely to get them.
But a high Sortino doesn't help in an extreme crisis, though it may eventually earn enough to buy an extreme-crisis hedge.
162
162/ ...
"It’s like playing Russian roulette. Hand me a revolver with one bullet and say, “Pull it for a million dollars.” I say, “No.”
"You say, “What is your price?”
"The answer is that there is no price."
...


"It’s like playing Russian roulette. Hand me a revolver with one bullet and say, “Pull it for a million dollars.” I say, “No.”
"You say, “What is your price?”
"The answer is that there is no price."
...
Frederik Gieschen@FrederikNeckar
Buffett in 1999 on LTCM and leverage: “Whenever a really bright person that has a lot of money goes broke, it’s because of leverage. It would be almost impossible to go broke without borrowed money being in the equation."
163
163/ "Being long pork bellies when they were limit down every day taught me the importance of risk controls. I never wanted to experience that pain again. It enhanced my fear of being wrong & taught me to make sure no bet could cause an unacceptable loss."
Darren r-σ²/2@ReformedTrader
45/ "Diversifying to a thousand stocks will only reduce the risk by about 15%, since the average stock has about a 0.60 correlation to another stock.
"With zero correlation, by the time you reach only 15 assets, you can cut volatility by 80%, a factor of five." (p. 57)
"With zero correlation, by the time you reach only 15 assets, you can cut volatility by 80%, a factor of five." (p. 57)
164
164/

Darren r-σ²/2@ReformedTrader
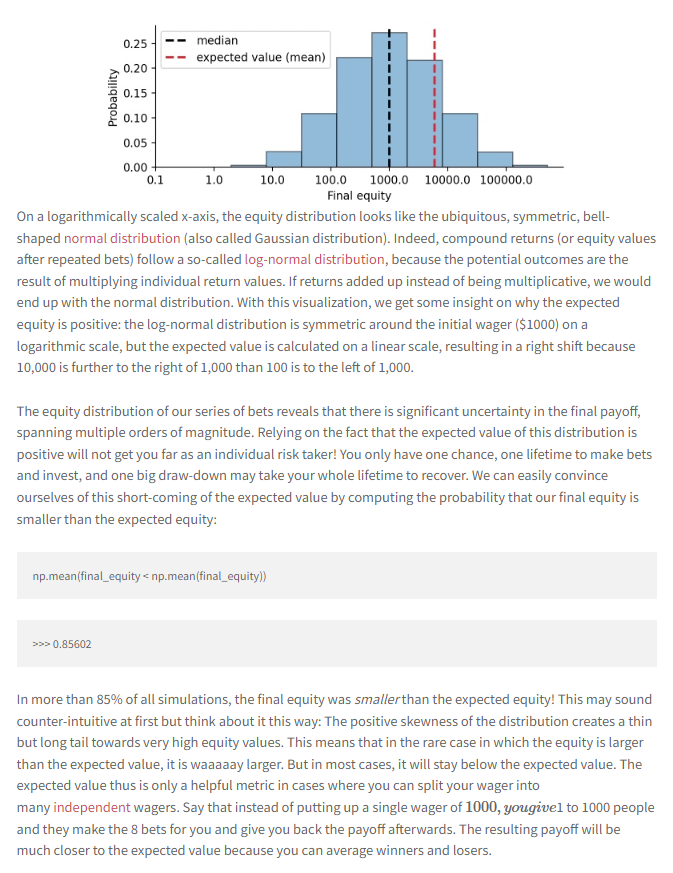
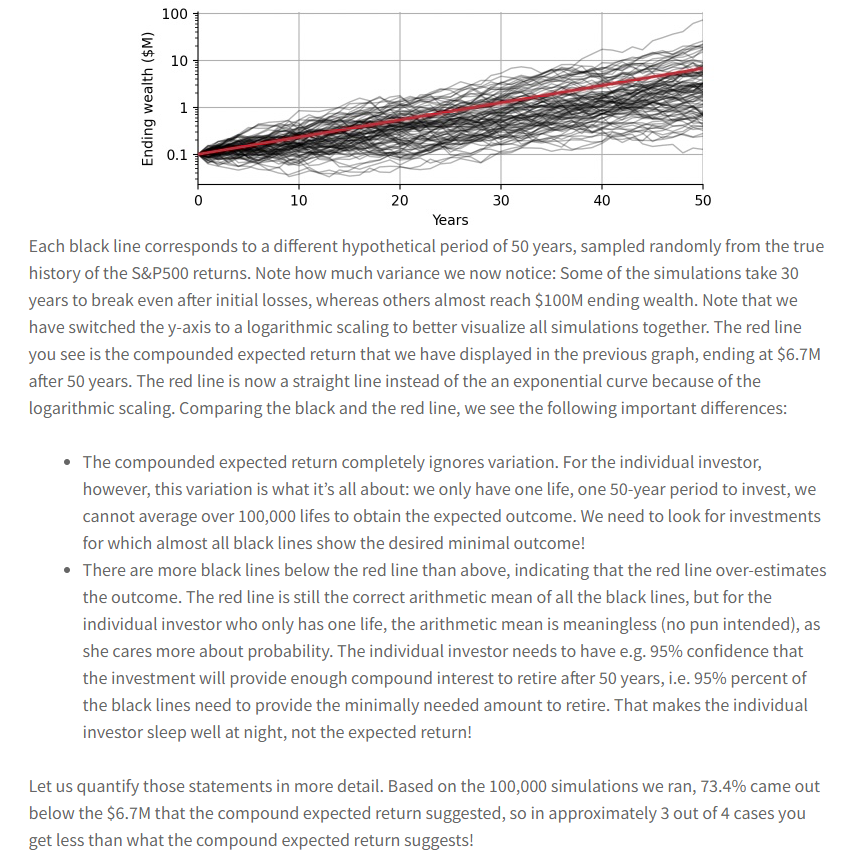
"The expected return that is reported ignores the uncertainty that comes from only having one chance, one life to invest.
"It takes a long time to make up for a large loss. Avoiding large drawdowns unleashes the power of compounding."
artifact-research.com/risk-mitigatio…
"It takes a long time to make up for a large loss. Avoiding large drawdowns unleashes the power of compounding."
artifact-research.com/risk-mitigatio…
165
165/ "It took 17 years of dedicated work to build Knight Capital Group into one of the leading trading houses on Wall Street. It all nearly ended in less than one hour.
"A simple error, nearly impossible to predict in advance, threatened to end the firm."
henricodolfing.com/2019/06/projec…
"A simple error, nearly impossible to predict in advance, threatened to end the firm."
henricodolfing.com/2019/06/projec…
166
166/ Thread:

Matt Hollerbach@breakingthemark
So keep this in mind with your own investing.
Don't personally bet past Kelly.
And don't invest with people who flaunt the idea of proper bet sizing, ignoring the concept of a Kelly maximum bet, instead believing "better is bigger."
Don't personally bet past Kelly.
And don't invest with people who flaunt the idea of proper bet sizing, ignoring the concept of a Kelly maximum bet, instead believing "better is bigger."
167
167/

the ghost of groditi’s future 👹@GRoditiD
the FTX thing lacks novelty in the incredibly constant part that institutions assumed to be or known to be risky are never really the problem, its always institutions assumed to be safe. GFC is littered with rescuers being drowned by recuees, too. and this is a useless platitude.
168
168/

169
169/ Interview with William Poundstone
* Kelly formuls
* If there’s a small chance of losing everything, you'll eventually lose everything
* Ed Thorp, blackjack, and card counting
* LTCM
* Martingale vs. Kelly
* Early version of the Black-Scholes formula

* Kelly formuls
* If there’s a small chance of losing everything, you'll eventually lose everything
* Ed Thorp, blackjack, and card counting
* LTCM
* Martingale vs. Kelly
* Early version of the Black-Scholes formula
Michael Covel@Covel
@ReformedTrader @RichB118 trendfollowing.com/2014/07/06/ep-…
170
170/

Frederik Gieschen@FrederikNeckar
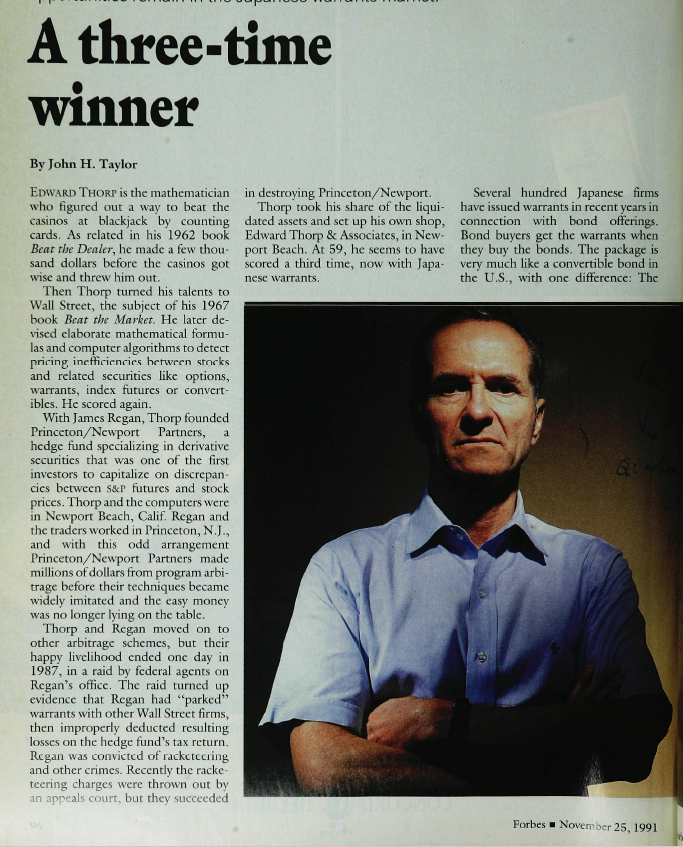
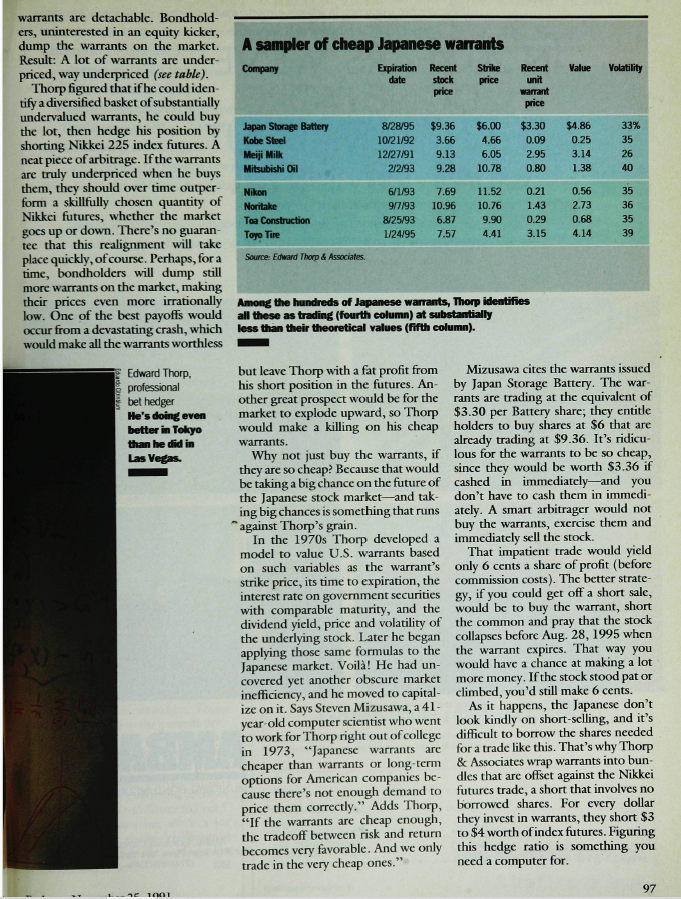
Ed Thorp in 1991, after Princeton/Newport Partners: "The only way I get an edge is by finding something that larger players like Goldman, Sachs or Bear, Steams haven't dissected yet. It makes me work a lot harder, but it's always challenging and exciting to be on the cutting edgeof something new."
Japanese warrants: "Bondholders, uninterested in an equity kicker, dump the warrants on the market.
Result: A lot of warrants are underpriced, way underpriced.
If he could identify a diversified basket of substantially
undervalued warrants, he could buy the lot, then hedge his position by shorting Nikkei 225 index futures."
"In Japan people are more interested in bonds than warrants, so they will sell them for whatever they can get."
"There's not enough demand to price them correctly."
"The key is buying the warrants very cheaply and making sure we have a diversified portfolio of
different warrants," Thorp says.
"I'm trying to maximize my position in time, money and health," says Thorp, sounding like the math professor he used to be. "If you do it well, you can use each variable to enhance the other two."
Japanese warrants: "Bondholders, uninterested in an equity kicker, dump the warrants on the market.
Result: A lot of warrants are underpriced, way underpriced.
If he could identify a diversified basket of substantially
undervalued warrants, he could buy the lot, then hedge his position by shorting Nikkei 225 index futures."
"In Japan people are more interested in bonds than warrants, so they will sell them for whatever they can get."
"There's not enough demand to price them correctly."
"The key is buying the warrants very cheaply and making sure we have a diversified portfolio of
different warrants," Thorp says.
"I'm trying to maximize my position in time, money and health," says Thorp, sounding like the math professor he used to be. "If you do it well, you can use each variable to enhance the other two."
171
171/ "If you lose a lot in your portfolio, it takes a higher required gain to make up the difference.
"If you are down 20%, you not only need to make 25% to get even, but you also need to generate 12% for 2 years to win back those loses."
mrzepczynski.blogspot.com/2024/03/decomp…
"If you are down 20%, you not only need to make 25% to get even, but you also need to generate 12% for 2 years to win back those loses."
mrzepczynski.blogspot.com/2024/03/decomp…
172
172/
Darren r-σ²/2@ReformedTrader
Jason Buck: Investing Russian Roulette - An Ergodicity Masterclass @InvestReSolve
"If I offer you $1M to play Russian Roulette, you might think about it.
"But if you had to do all six in succession, you're not going to do it [regardless of the pay]."
youtube.com/watch?v=xT_M0e…
"If I offer you $1M to play Russian Roulette, you might think about it.
"But if you had to do all six in succession, you're not going to do it [regardless of the pay]."
youtube.com/watch?v=xT_M0e…
173
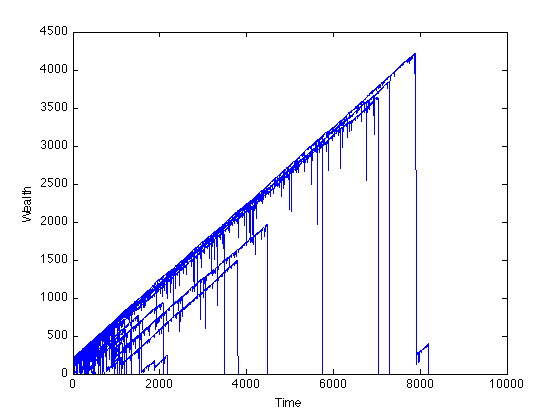
173/ "Someone on stack exchange ran a simulation of 100 players starting with $100 all using a Martingale betting strategy. This is the result."


ʎllǝuuop ʇuǝɹq@donnelly_brent
Someone on stack exchange ran a simulation of 100 players starting with $100 all using a Martingale betting strategy. This is the result.
Cool graph.
math.stackexchange.com/questions/8390…
Cool graph.
math.stackexchange.com/questions/8390…
174
174/ "I know many short sellers who refuse to learn that point about leverage + crowded shorts. Over and over again they have awful drawdowns that ruin their long term results. Each time it happens, they blame the irrational market."

David Orr@orrdavid
I personally know many short sellers who seemingly refuse to learn that point about leverage + crowded shorts. Over and over again they have awful drawdowns that would prevent them from having a fund, and ruin their long term results. Each time it happens they blame the irrational market. No sir. It's *you* who is irrational.
175
175/ "Edward Thorp is an American mathematics professor, author, hedge fund manager and blackjack player who has a net worth of $800 million dollars."
celebritynetworth.com/richest-busine…
celebritynetworth.com/richest-busine…
176
176/
Darren r-σ²/2@ReformedTrader
Successful trading is gambling with a well-researched, positive edge and in which the outcomes can have large absolute values of skewness and kurtosis.
But at its core, it's still gambling, and if you bet too much, you may get lucky for a while but will eventually blow up.
But at its core, it's still gambling, and if you bet too much, you may get lucky for a while but will eventually blow up.
177
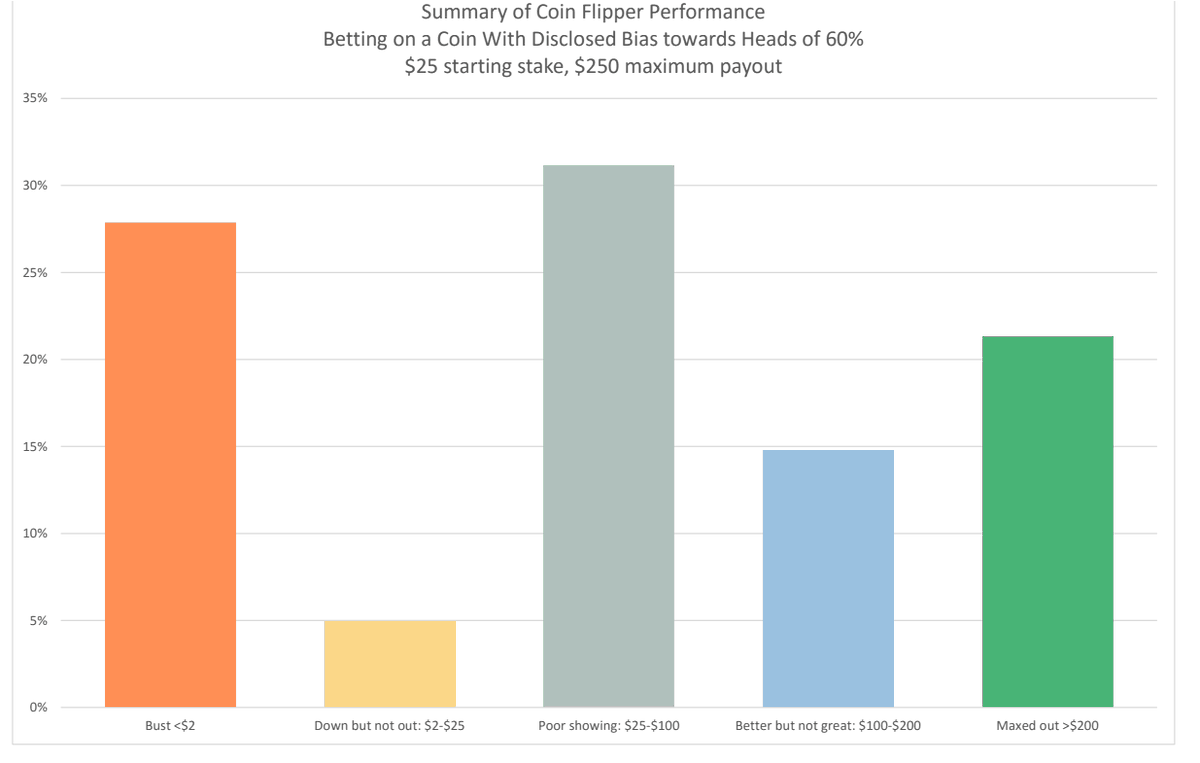
177/ Rational Decision-Making under Uncertainty: Observed Betting Patterns on a Biased Coin
Darren r-σ²/2@ReformedTrader
1/ Rational Decision-Making under Uncertainty: Observed Betting Patterns on a Biased Coin (Haghani, Dewey)
"The majority of young, quantitatively trained players did not bet very well, displaying a panoply of behaviorial/cognitive biases. 30% went bust."
semanticscholar.org/paper/Rational…
"The majority of young, quantitatively trained players did not bet very well, displaying a panoply of behaviorial/cognitive biases. 30% went bust."
semanticscholar.org/paper/Rational…
178
178/ Tail Risk Adjusted Sharpe Ratio
x.com/ReformedTrader…
Geometric Mean Approximations of Individual Security and Portfolio Performance
x.com/ReformedTrader…
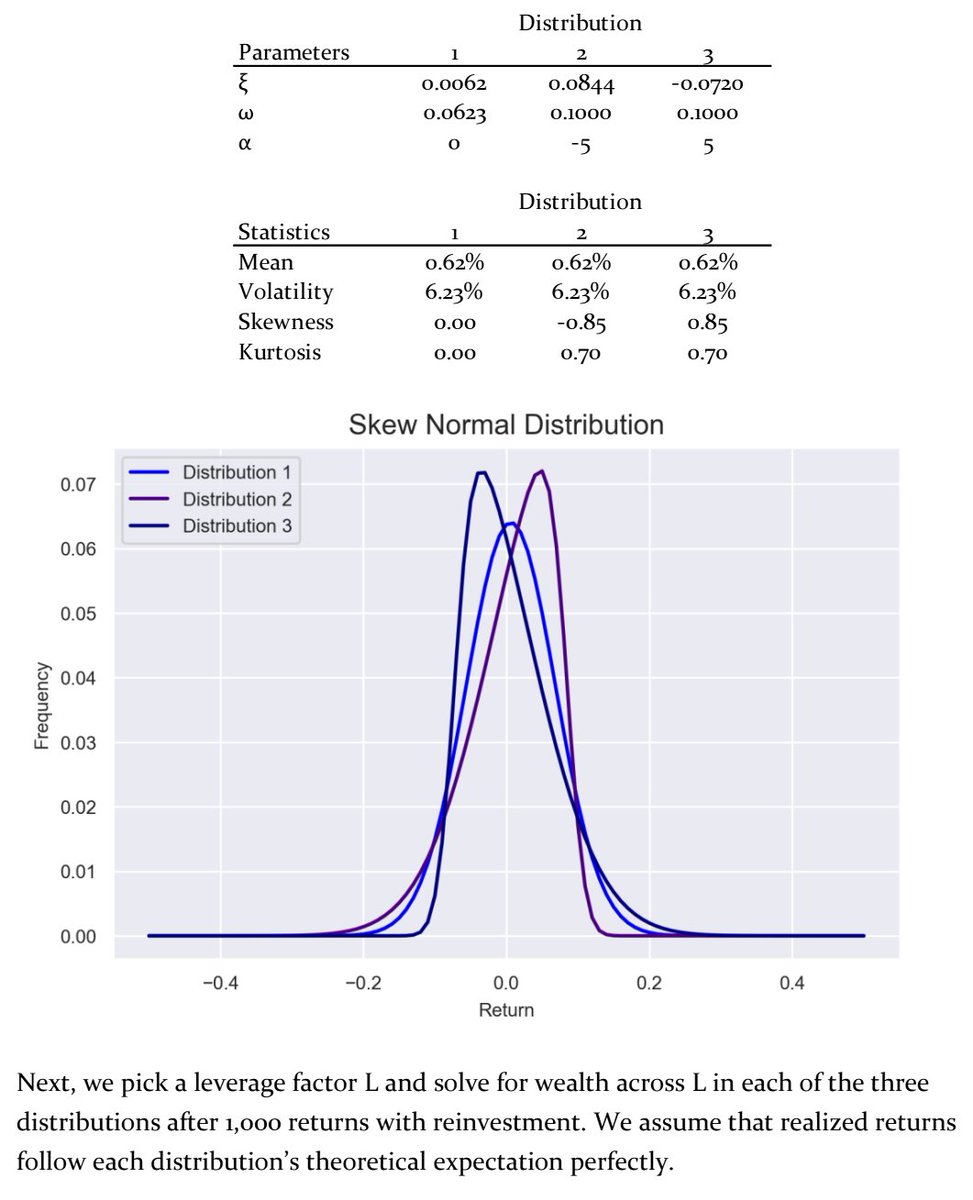
Give me a moment: Optimal leverage in the presence of volatility, skewness, and kurtosis


x.com/ReformedTrader…
Geometric Mean Approximations of Individual Security and Portfolio Performance
x.com/ReformedTrader…
Give me a moment: Optimal leverage in the presence of volatility, skewness, and kurtosis
Darren r-σ²/2@ReformedTrader
Give me a moment: Optimal leverage in the presence of volatility, skewness, and kurtosis (Kestner)
"We introduce a new method to determine optimal leverage to maximize wealth when investment returns are not normally distributed."
papers.ssrn.com/sol3/papers.cf…
"We introduce a new method to determine optimal leverage to maximize wealth when investment returns are not normally distributed."
papers.ssrn.com/sol3/papers.cf…
179
179/
Darren r-σ²/2@ReformedTrader
This thread makes the math in Fortune's Formula explicit so it can be easily applied to publicly traded markets.
IMO, it is the most powerful formula in finance.
IMO, it is the most powerful formula in finance.
180
180/ Thread:

Benn Eifert 🥷🏴☠️@bennpeifert
Hopefully the lessons are obvious here:
1) Never short uncapped variance or a replication thereof, even if "hedged"
2) Monster positive returns are a red flag from a risk standpoint unless they come from asymmetric long-convexity positions
1) Never short uncapped variance or a replication thereof, even if "hedged"
2) Monster positive returns are a red flag from a risk standpoint unless they come from asymmetric long-convexity positions
181
181/

Darren r-σ²/2@ReformedTrader
When a Crystal Ball Isn’t Enough to Make You Rich (Haghani, White)
"We gave 118 young adults trained in finance information on the front page of the Wall Street Journal one day in advance but with stock and bond price data blacked out."
papers.ssrn.com/sol3/papers.cf…
"We gave 118 young adults trained in finance information on the front page of the Wall Street Journal one day in advance but with stock and bond price data blacked out."
papers.ssrn.com/sol3/papers.cf…
182
182/


Giuliano@Giuliano_Mana
Ed Thorp:
- Invented a system to count cards in Blackjack.
- Invented a system that beats the roulette.
- Traded options with a model that preceded Black-Scholes.
- Ran a fund for 20 years and only had 3 down months (<1%).
"If I don't have an edge, I don't play"
- Invented a system to count cards in Blackjack.
- Invented a system that beats the roulette.
- Traded options with a model that preceded Black-Scholes.
- Ran a fund for 20 years and only had 3 down months (<1%).
"If I don't have an edge, I don't play"
183
183/ Ed Thorp!


Victor Haghani@ElmWealth
Had the wonderful pleasure of meeting Ed Thorp (@EdwardOThorp) of Beat The Dealer and Beat The Market fame and his son Jeff for lunch yesterday. Ed wrote a kind blurb for The Missing Billionaires and hopefully will again for our new book coming out next year!

