🚨 THE PHOTONICS COMPANY POWERING AI SCALE AI factories are entering...

Gaetano@Gaetano2026
138 views
Dec 15, 2025
~4 min read
Advertisement
1
🚨 THE PHOTONICS COMPANY POWERING AI SCALE
AI factories are entering a phase where connectivity determines scale.
Coherent $COHR supplies the photonic hardware that allows massive GPU clusters to communicate at extreme bandwidth with manageable power and heat.
As clusters grow, optical links become core system architecture inside the AI factory.
Let’s unpack one of my largest photonics positions 🧵
AI factories are entering a phase where connectivity determines scale.
Coherent $COHR supplies the photonic hardware that allows massive GPU clusters to communicate at extreme bandwidth with manageable power and heat.
As clusters grow, optical links become core system architecture inside the AI factory.
Let’s unpack one of my largest photonics positions 🧵
2
THE COPPER WALL IS THE SETUP $COHR
As signaling speeds rise, electrical connections face hard physical limits.
At 200G per lane, loss, noise, and heat compound rapidly over short distances.
This forces architectural changes inside data centers and accelerates the migration toward optical links across racks, rows, and clusters.
As signaling speeds rise, electrical connections face hard physical limits.
At 200G per lane, loss, noise, and heat compound rapidly over short distances.
This forces architectural changes inside data centers and accelerates the migration toward optical links across racks, rows, and clusters.
3
OPTICS BECOMES THE DEFAULT $COHR
Optical fiber solves the distance and bandwidth problem simultaneously.
Photons travel farther with minimal attenuation and lower thermal cost.
As training clusters scale, the optic attach rate rises across GPUs, switches, and fabrics, creating sustained demand for transceivers and embedded laser content.
Optical fiber solves the distance and bandwidth problem simultaneously.
Photons travel farther with minimal attenuation and lower thermal cost.
As training clusters scale, the optic attach rate rises across GPUs, switches, and fabrics, creating sustained demand for transceivers and embedded laser content.
4
COHERENT’S BUSINESS HAS BEEN REBUILT AROUND THIS
$COHR reshaped itself into a concentrated photonics platform aligned with AI capex.
Datacenter & Communications now represents ~69% of revenue, growing 26% YoY.
This mix shift changes margin structure, customer concentration, capital allocation, and how the market values the business.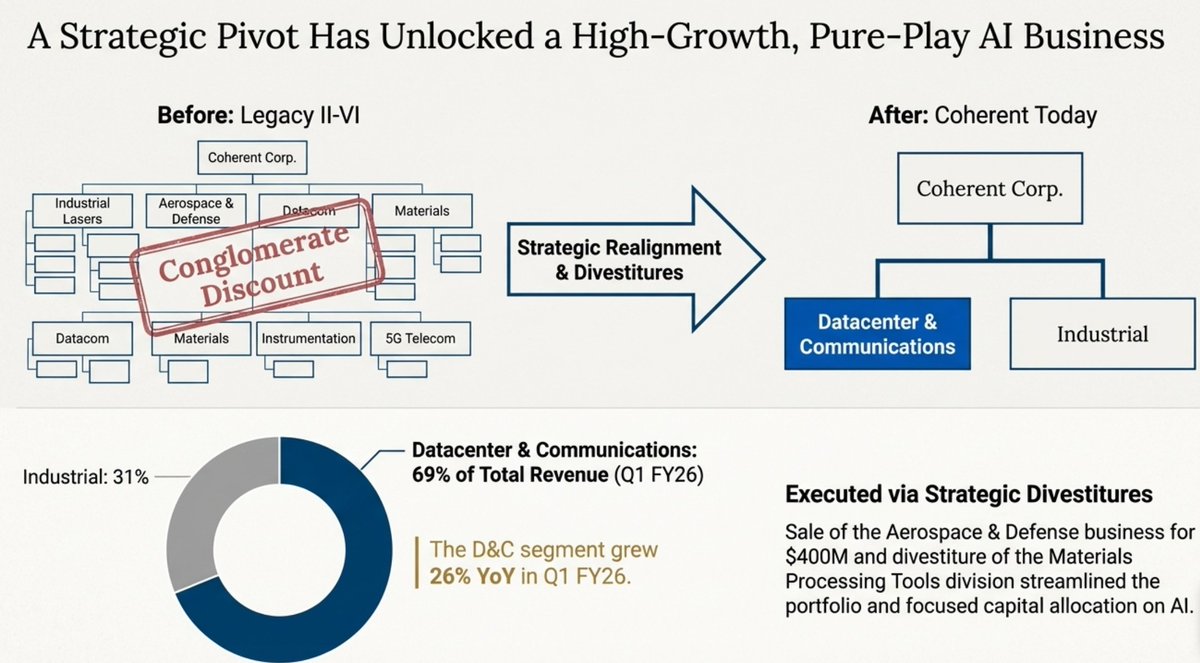
$COHR reshaped itself into a concentrated photonics platform aligned with AI capex.
Datacenter & Communications now represents ~69% of revenue, growing 26% YoY.
This mix shift changes margin structure, customer concentration, capital allocation, and how the market values the business.
5
VERTICAL INTEGRATION IS THE MOAT $COHR
Coherent controls the most constrained inputs in advanced optics.
It fabricates Indium Phosphide wafers and manufactures high-speed lasers internally.
As data rates climb, laser performance and yield dominate cost curves.
Owning the fab allows faster iteration, tighter supply, and margin capture upstream.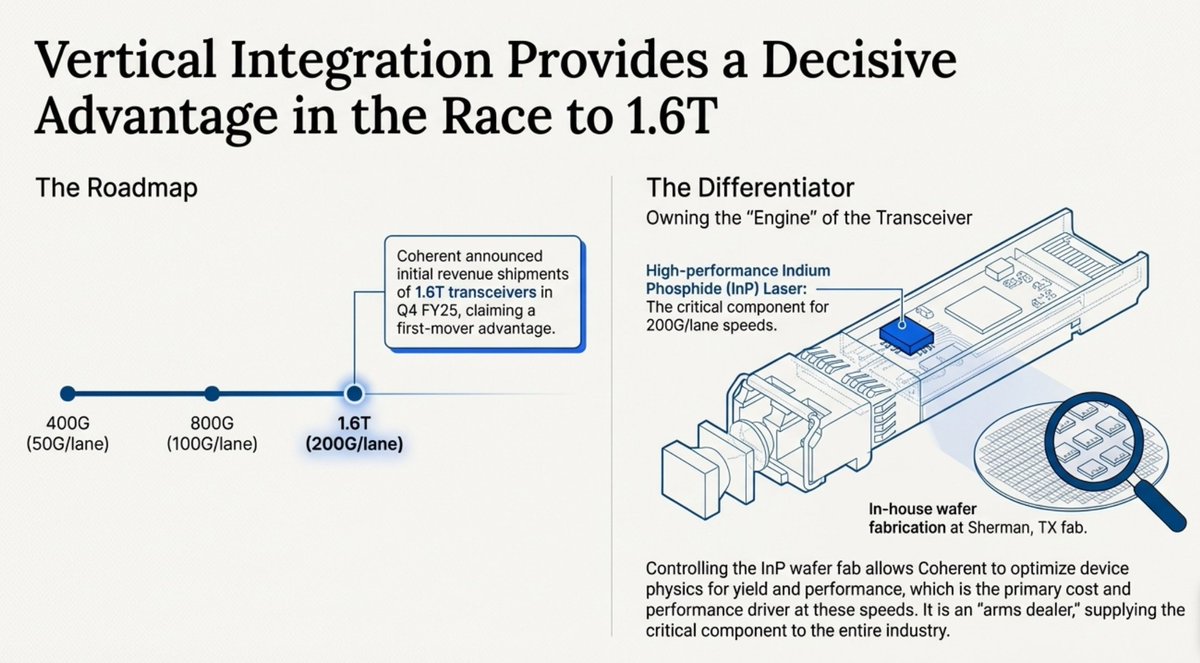
Coherent controls the most constrained inputs in advanced optics.
It fabricates Indium Phosphide wafers and manufactures high-speed lasers internally.
As data rates climb, laser performance and yield dominate cost curves.
Owning the fab allows faster iteration, tighter supply, and margin capture upstream.
6
YIELD CURVES DRIVE MARGINS AT 1.6T $COHR
At 1.6T, economics hinge on yield improvement.
Early-cycle laser yields start low.
Every incremental yield gain flows directly into gross margin.
This creates hidden operating leverage that favors vertically integrated suppliers over assemblers dependent on third-party laser sources.
At 1.6T, economics hinge on yield improvement.
Early-cycle laser yields start low.
Every incremental yield gain flows directly into gross margin.
This creates hidden operating leverage that favors vertically integrated suppliers over assemblers dependent on third-party laser sources.
7
800G WAS THE RAMP, 1.6T IS THE INFLECTION $COHR
800G deployments drove the current growth phase.
1.6T defines the next step-function.
200G per lane signaling pushes lasers, packaging, and thermal limits simultaneously.
Coherent has already shipped initial 1.6T products, positioning it early in the transition curve.
800G deployments drove the current growth phase.
1.6T defines the next step-function.
200G per lane signaling pushes lasers, packaging, and thermal limits simultaneously.
Coherent has already shipped initial 1.6T products, positioning it early in the transition curve.
8
THE “ARMS DEALER” REVENUE MODEL $COHR
Coherent participates even when competitors win module share.
It sells laser components into the broader ecosystem, including rival transceiver manufacturers.
This creates volume participation across the entire market and reduces dependence on any single OEM or design win.
Industry growth matters more than isolated share swings.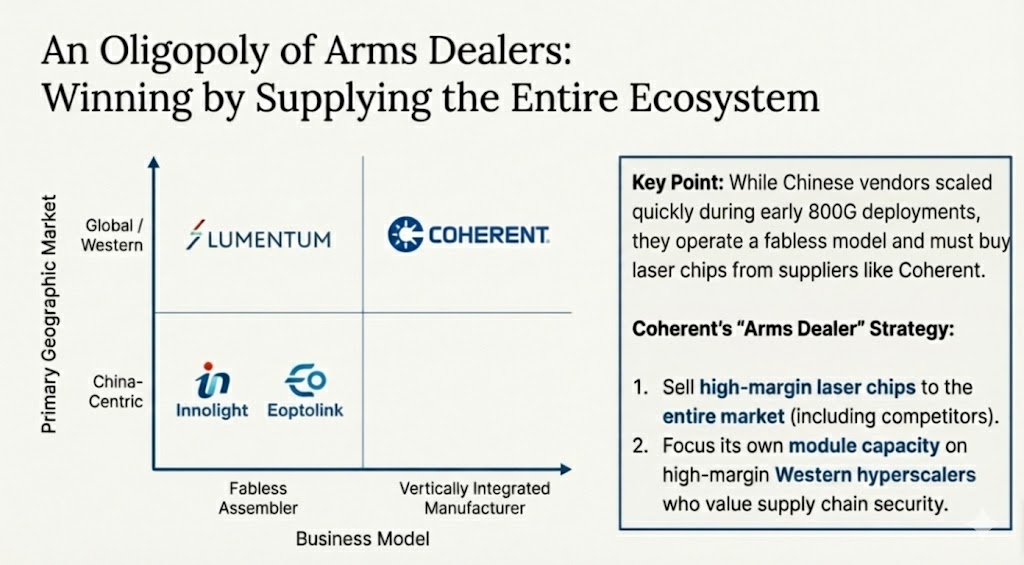
Coherent participates even when competitors win module share.
It sells laser components into the broader ecosystem, including rival transceiver manufacturers.
This creates volume participation across the entire market and reduces dependence on any single OEM or design win.
Industry growth matters more than isolated share swings.
9
PACKAGING AND TEST ARE REAL BOTTLENECKS $COHR
At higher speeds, assembly becomes as critical as design.
Tighter alignment tolerances.
More extensive burn-in and reliability testing.
Lower tolerance for variation.
Coherent’s Southeast Asia expansion is throughput insurance, ensuring it can scale production as demand accelerates.
At higher speeds, assembly becomes as critical as design.
Tighter alignment tolerances.
More extensive burn-in and reliability testing.
Lower tolerance for variation.
Coherent’s Southeast Asia expansion is throughput insurance, ensuring it can scale production as demand accelerates.
10
OPTICAL CIRCUIT SWITCHING EXPANDS THE PLAYBOOK $COHR
OCS adds a second growth vector.
OCS routes photons directly, reducing power draw and latency by eliminating repeated conversions.
Initial customer shipments signal movement beyond pilots, and management frames OCS as a multi-billion-dollar TAM expansion over time.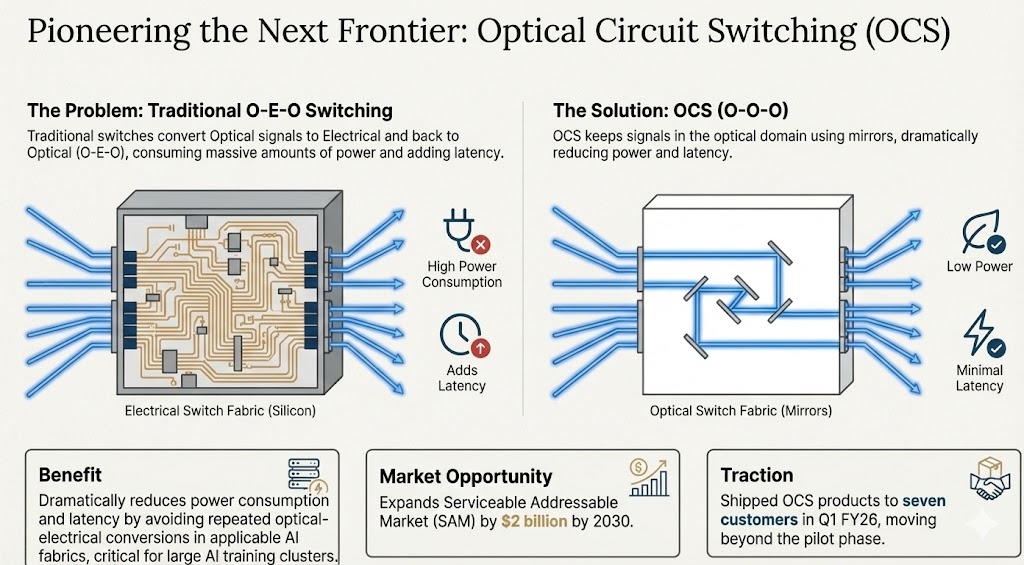
OCS adds a second growth vector.
OCS routes photons directly, reducing power draw and latency by eliminating repeated conversions.
Initial customer shipments signal movement beyond pilots, and management frames OCS as a multi-billion-dollar TAM expansion over time.
11
FINANCIALS CONFIRM THE STRUCTURAL SHIFT $COHR
The income statement reflects the transformation.
FY25 revenue: $5.81B, +23% YoY
Non-GAAP gross margin ~38%, expanding
Earnings power rising through mix shift and operating leverage
Datacenter growth is pulling margins higher while reducing the influence of industrial cyclicality on overall results.
The income statement reflects the transformation.
FY25 revenue: $5.81B, +23% YoY
Non-GAAP gross margin ~38%, expanding
Earnings power rising through mix shift and operating leverage
Datacenter growth is pulling margins higher while reducing the influence of industrial cyclicality on overall results.
12
DELEVERAGING IS A STRATEGIC FEATURE $COHR
I view Coherent's capital discipline as a strength.
Coherent directed divestiture proceeds and operating cash flow toward rapid debt reduction, including a $400M paydown in a single quarter.
Lower leverage improves resilience, reduces interest drag, and increases flexibility for future reinvestment or shareholder returns.
I view Coherent's capital discipline as a strength.
Coherent directed divestiture proceeds and operating cash flow toward rapid debt reduction, including a $400M paydown in a single quarter.
Lower leverage improves resilience, reduces interest drag, and increases flexibility for future reinvestment or shareholder returns.
13
GEOPOLITICS CREATES A WESTERN SUPPLY PREMIUM $COHR
AI infrastructure increasingly rewards secure, trusted supply chains.
Coherent fabricates wafers in the US and Europe and assembles in Southeast Asia.
As hyperscalers prioritize supply certainty and jurisdictional alignment, this footprint becomes a competitive advantage.
AI infrastructure increasingly rewards secure, trusted supply chains.
Coherent fabricates wafers in the US and Europe and assembles in Southeast Asia.
As hyperscalers prioritize supply certainty and jurisdictional alignment, this footprint becomes a competitive advantage.
14
CAPEX WAVES AND ORDER TIMING $COHR
AI infrastructure spending arrives in waves.
Hyperscalers build capacity ahead of utilization, which can create temporary pauses in ordering even during strong long-term trends.
Understanding this cadence helps separate short-term volatility from structural demand embedded in cluster expansion.
AI infrastructure spending arrives in waves.
Hyperscalers build capacity ahead of utilization, which can create temporary pauses in ordering even during strong long-term trends.
Understanding this cadence helps separate short-term volatility from structural demand embedded in cluster expansion.
15
WHERE CPO FITS INTO THE STORY $COHR
Co-packaged optics reshapes form factors.
Even with CPO, high-performance lasers and CW light sources remain essential.
Packaging complexity increases, reinforcing the value of component depth and materials expertise rather than eliminating optical demand.
Co-packaged optics reshapes form factors.
Even with CPO, high-performance lasers and CW light sources remain essential.
Packaging complexity increases, reinforcing the value of component depth and materials expertise rather than eliminating optical demand.
16
WHAT MATTERS GOING FORWARD $COHR
Three indicators define the next phase:
1.6T yield and volume ramp
OCS converting pilots into recurring revenue
Sustained hyperscaler build activity
At 1.6T, optics behave less like components and more like capacity-constrained infrastructure.
Coherent sits directly inside that constraint.
Three indicators define the next phase:
1.6T yield and volume ramp
OCS converting pilots into recurring revenue
Sustained hyperscaler build activity
At 1.6T, optics behave less like components and more like capacity-constrained infrastructure.
Coherent sits directly inside that constraint.
17
Disclaimer: None of this is financial advice.
This post is designed to serve as a starting point, not the complete picture. Also, these images are all AI generated and have some flaws. Please treat them as illustrative to add some visual context even if they aren't perfect.
This post is designed to serve as a starting point, not the complete picture. Also, these images are all AI generated and have some flaws. Please treat them as illustrative to add some visual context even if they aren't perfect.
