ECB's #RatesCancelCulture, France’s Spending Profligacy, and...

Domenico De Giorgio, EU. Capre Diem (not a typo).@degiorgiod
16 views
Sep 05, 2025
~3 min read
Advertisement
1
ECB's #RatesCancelCulture, France’s Spending Profligacy, and Italy’s No-Spend/No-Growth Wonder: a long thread
Over the years I have repeatedly argued that the ECB’s excessively prolonged interventions to control long-end yields of key Eurozone sovereign debt sowed the seeds 1/

Over the years I have repeatedly argued that the ECB’s excessively prolonged interventions to control long-end yields of key Eurozone sovereign debt sowed the seeds 1/
Domenico De Giorgio, EU. Capre Diem (not a typo).@degiorgiod
Yeah, #RatesCancelCulture ((C) YoursTruly) IS fun.
Take Italy.
Based on ECB Data, the unreal conclusion's that IT Debt Supply's actually been negative from Dec.'15 on, now @ - 368bn Eur once PSPP (Principal + Reinvestments), PEPP (Principal) are accounted for.
@INArteCarloDoss
Take Italy.
Based on ECB Data, the unreal conclusion's that IT Debt Supply's actually been negative from Dec.'15 on, now @ - 368bn Eur once PSPP (Principal + Reinvestments), PEPP (Principal) are accounted for.
@INArteCarloDoss
2
of political irresponsibility and short-term, short-sighted spending profligacy.
Between March 2015 (when Mario Draghi’s ECB launched the first batch of the PSPP to shore up debt-ridden PIGS) and July 2025 – chart 1 – net issuance of euro-denominated debt instruments by key 2/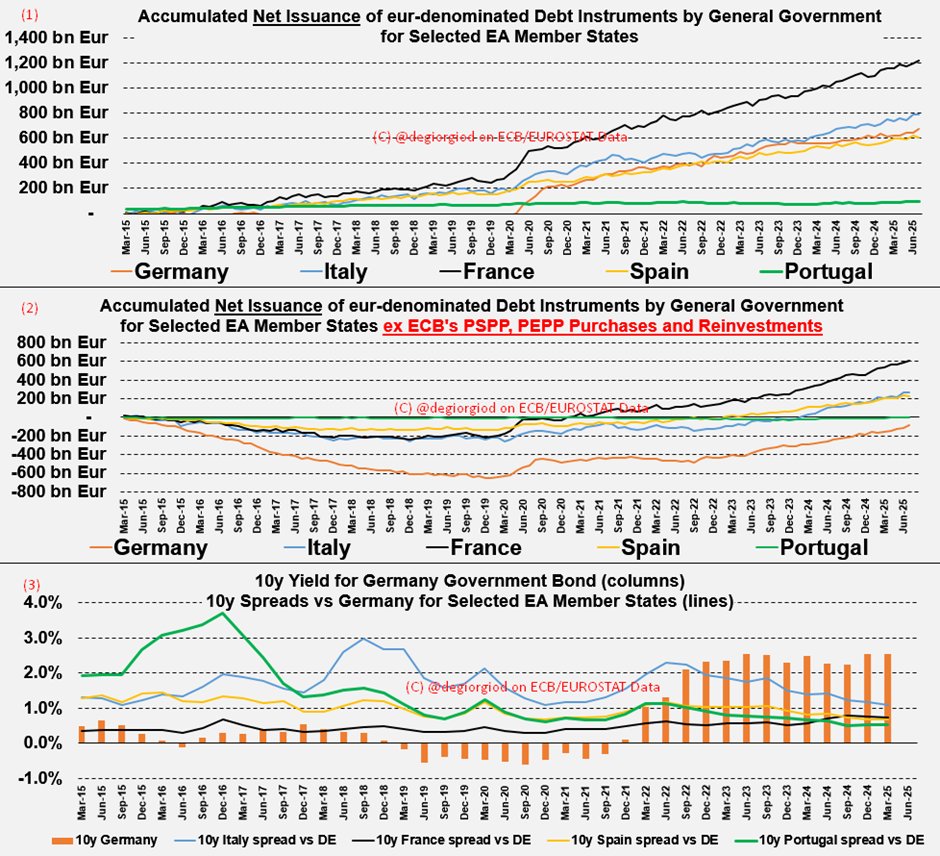
Between March 2015 (when Mario Draghi’s ECB launched the first batch of the PSPP to shore up debt-ridden PIGS) and July 2025 – chart 1 – net issuance of euro-denominated debt instruments by key 2/
3
EU sovereigns increased by €1.2tn for France, €0.8tn for Italy, €0.65tn for Germany, €0.6tn for Spain, and €0.1tn for Portugal. Yet, thanks to the combination of the ECB’s PSPP, PEPP, and massive redemption reinvestments (PEPP’s gigantic reinvestments ended in Dec 2024; 3/
4
PSPP’s in July 2023), the actual net supply that reached the market – chart 2 – was only a fraction of what these high-spending governments had issued: €0.6tn for France, €0.3tn for Italy, minus €0.10tn for Germany, €0.2tn for Spain, and €0.0tn for Portugal.
Not only did 4/
Not only did 4/
5
political irresponsibility become the hallmark of European politicians (see Italy’s Five Star Movement-sponsored plan to subsidize a debt-funded €135bn residential housing renewal programme that added nothing to GDP), but to add insult to injury, negative yields on German 5/
6
10-year debt finally came to an end by late 2021.
It was then – chart 3 – that market pressure brought some belated discipline to Italy’s crony-spending habitus, leading to the “savvy” no-spend/no-growth approach adopted by the Meloni government (from 2022 onward), bolstered 6/
It was then – chart 3 – that market pressure brought some belated discipline to Italy’s crony-spending habitus, leading to the “savvy” no-spend/no-growth approach adopted by the Meloni government (from 2022 onward), bolstered 6/
7
by the Draghi government’s credibility boost (2021–2022). Chart 3 shows how, from summer 2022, this no-spend/no-growth strategy began to pay off as the spread versus Germany steadily declined.
The political tremors shaking today’s France are rooted in a long-standing lack of 7/
The political tremors shaking today’s France are rooted in a long-standing lack of 7/
8
spending restraint. The country’s very generous welfare state has shown multiple cracks over the past decade: it has failed to foster inclusiveness among second- and third-generation immigrants while preserving an unsustainable pension system that has proved politically toxic 8/
9
for anyone trying to rein in its largesse. Chart 2 illustrates how, generous ECB purchases notwithstanding, France’s net supply turned positive as early as March 2020—four years before Italy’s. Italy’s unwritten rule of running a “primary surplus” did pay off, at least by this 9/
10
accounting metric.
Today’s tensions in the French debt market are entirely legitimate—and could not come at a worse time. Spending must be kept under control, even at the expense of growth. That is the lesson learned from Italy, where stagnant economic growth has been placed 10/
Today’s tensions in the French debt market are entirely legitimate—and could not come at a worse time. Spending must be kept under control, even at the expense of growth. That is the lesson learned from Italy, where stagnant economic growth has been placed 10/
11
in second position, in exchange for prudent fiscal policy and political stability, despite a €3.0tn public debt.
And yet this is still not enough. The baseline for euro-area yields is now much higher, as the “Re-arm EU” plan and structural delays in growth-oriented 11/
And yet this is still not enough. The baseline for euro-area yields is now much higher, as the “Re-arm EU” plan and structural delays in growth-oriented 11/
12
investments (AI among them) argue for German yields that are unlikely to fall back from current levels—if anything, they may climb higher.
Fiscal consolidation is for sunny days: making hay while the sun shines to prepare for winter. And winter is now, even if Europeans /12
Fiscal consolidation is for sunny days: making hay while the sun shines to prepare for winter. And winter is now, even if Europeans /12
13
find it hard to face.
@gianlucac1bis @HannoLustig @jeuasommenulle @INArteCarloDoss @albertobisin @HayekAndKeynes @ThManfredi @CarloStagnaro @micheleboldrin @VeroDeRomanis @helentbiz @TwainsMustache @komileva @patrick_saner @SirOfFinance @ericlchaney
@gianlucac1bis @HannoLustig @jeuasommenulle @INArteCarloDoss @albertobisin @HayekAndKeynes @ThManfredi @CarloStagnaro @micheleboldrin @VeroDeRomanis @helentbiz @TwainsMustache @komileva @patrick_saner @SirOfFinance @ericlchaney
14
@threadreaderapp unroll please
15
Scusami se ho scordato di metterti in cc @Phastidio. Leggo di come taluni si ispirino senza citarti ai tuoi lavori, da sempre eccezionali come ti testimonio da un quindicennio circa.
Per il lavoro sulla Francia che hai redatto forse questi miei dati ti suoneranno utili.
🫂
Per il lavoro sulla Francia che hai redatto forse questi miei dati ti suoneranno utili.
🫂