For shitzngigguls... a followup... Among others, I look at A...

Baufinanciaphaster 👹@bauhiniacapital
15 views
Jan 07, 2025
~2 min read
Advertisement
1
For shitzngigguls... a followup...
Among others, I look at A Particular Index (not gonna tell you which, but using this one as less esoteric than most (to most of fintwit)). We try to predict inclusions and deletions.
We start months ahead.
In This Particular Index...
Among others, I look at A Particular Index (not gonna tell you which, but using this one as less esoteric than most (to most of fintwit)). We try to predict inclusions and deletions.
We start months ahead.
In This Particular Index...
Baufinanciaphaster 👹@bauhiniacapital
Some MORE comments about index construction.
1) Generically speaking, there are VERY few large US stocks which issue large amounts of new equity in order to buy something. It happens from time to time, but it is reasonably rare.
When a company like MSTR issues new shares to
1) Generically speaking, there are VERY few large US stocks which issue large amounts of new equity in order to buy something. It happens from time to time, but it is reasonably rare.
When a company like MSTR issues new shares to
2
At end-Sep, calcs showed 4 likely Deletions in December with a possible extra 2-3 deletions over the quarter. So we started with four names, and sure enough, two got the boot, and as time passed, some of those we thought would get the boot somehow rescued themselves from that
3
indignation, replaced by others. Numbers changed. At the end, we had X expected, and X were announced to be deleted, and we got X-1 correct (kinda bummed about that actually).
The portfolio of those shorts (red line) was volatile. To hedge that portfolio, we could go long
The portfolio of those shorts (red line) was volatile. To hedge that portfolio, we could go long
4
a basket of several names of the same sector, or long the index they were in. So we track both as a long-short portfolio (long the sector or index, short the names on your deletion list at any given time).
It was doing OK. In early November the sector-neutral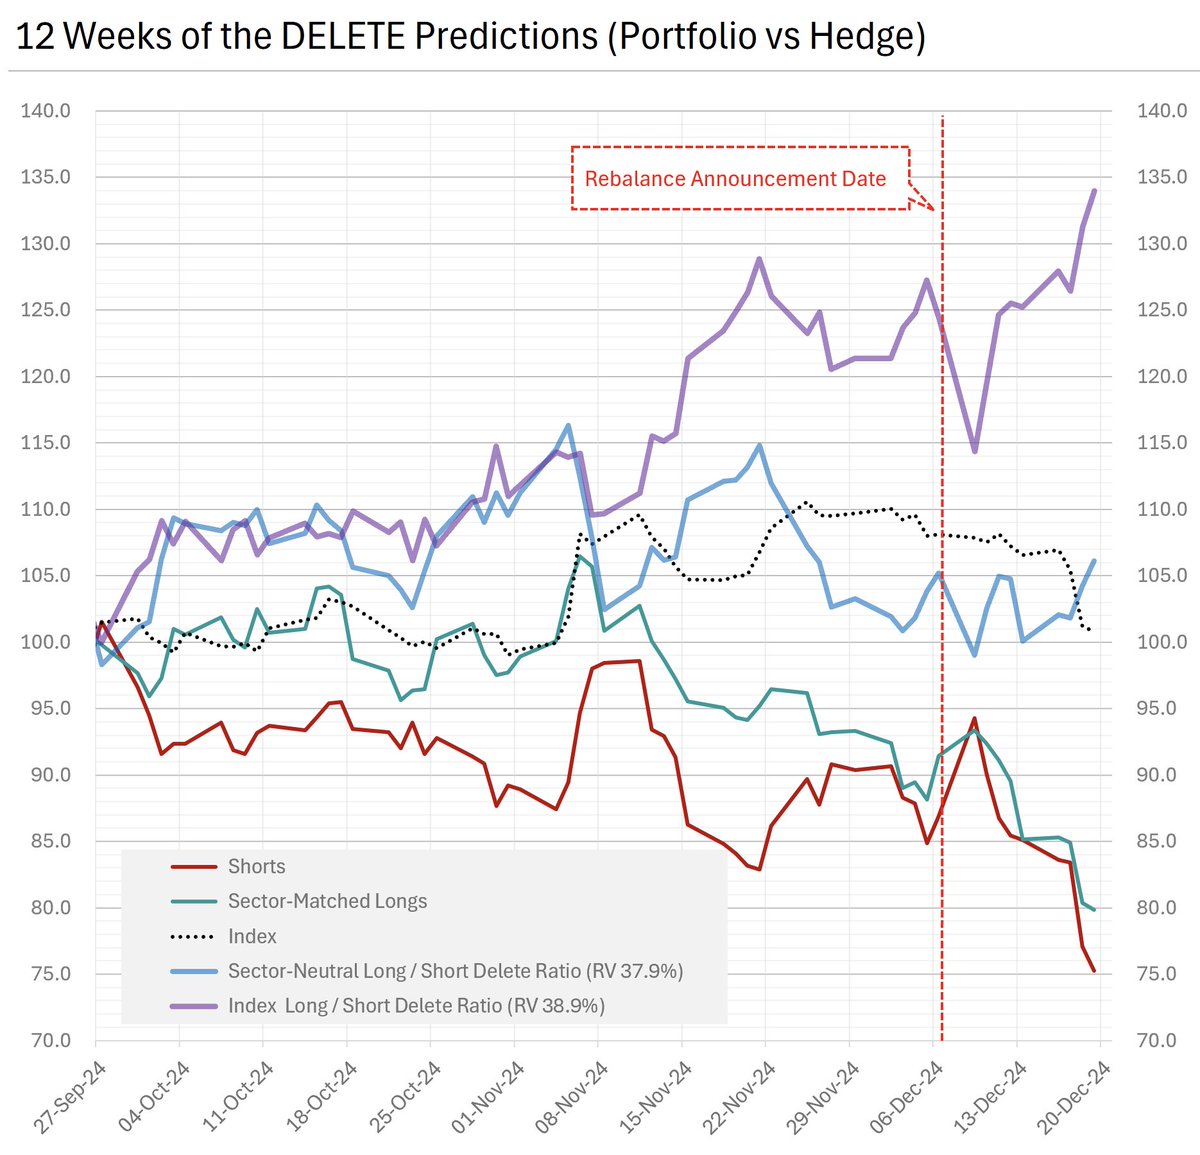
It was doing OK. In early November the sector-neutral
5
long-short portfolio (light blue) got slammed. Bias risk.
Long Particular Index vs Expected Deletes (Purple) only came off a bit.
On the announcement of index changes, the shorts bounced, P&L would have been awful that day, but it came back. In that case, sector hedge was
Long Particular Index vs Expected Deletes (Purple) only came off a bit.
On the announcement of index changes, the shorts bounced, P&L would have been awful that day, but it came back. In that case, sector hedge was
6
safer. Now with a day left, it is either +6% for the quarter or +34%, with roughly the same volatility.
We'll watch today.
The chart above shows a simple (quick & dirty hedge basket) equal-weighted portfolio (not value-to-trade-weighted, or volatility-weighted or beta-adjusted
We'll watch today.
The chart above shows a simple (quick & dirty hedge basket) equal-weighted portfolio (not value-to-trade-weighted, or volatility-weighted or beta-adjusted
7
- just EW) rebalanced every day. The hedge could be selected better.
But this is why one trades these events across a broader swath of events and manages one's portfolio risk. 37% vol in a long-short portfolio is a recipe for near-certain seat loss in a big MM fund.
But this is why one trades these events across a broader swath of events and manages one's portfolio risk. 37% vol in a long-short portfolio is a recipe for near-certain seat loss in a big MM fund.
8
Nota bene: this is just one index pulled out of the hat as an example. The Long Index/Short Expected Deletion Names performance is due to radical bias exposure. The mixed sector-neutral performance tells you sector momentum bias has been dramatic.